


EN
Earnings Beat Could Be A Turning Point For Ryman Hospitality Properties Stock
- Ryman Hospitality Properties reported third quarter 2026 revenue of US$655.8 million and net income of US$40.21 million, with both basic and diluted earnings per share from continuing operations above the prior year period.
- The business also posted higher revenue, net income, and earnings per share for the first nine months of 2026 compared with the same stretch of 2025, reinforcing how its current operations are translating into stronger reported profitability.
- We will now explore how Ryman Hospitality Properties' quarterly earnings beat, including the FFO surprise, could influence its broader investment narrative.
Ryman Hospitality Properties Investment Narrative Recap
To own Ryman Hospitality Properties, you need to believe in large scale group travel, conventions and country music entertainment remaining attractive uses of time and budget. The latest quarter showed higher revenue, net income and EPS versus a year ago, which supports that thesis but does not radically change it. The near term swing factor still looks like how effectively the portfolio absorbs new rooms, meeting space and entertainment capacity.
The biggest operational risk is execution on heavy capital projects such as Grande Lakes Orlando and the wider resort upgrade pipeline, while carrying meaningful debt and interest costs. Strong recent FFO and the earnings beat help the story, yet they do not remove concerns about capex creep, refinancing terms or any slowdown in group bookings that would make those investments harder to earn back.
The most relevant update tied to this print is the funds from operations figure. Ryman Hospitality Properties reported quarterly FFO of US$1.79 per share, which outpaced the Zacks Consensus Estimate. For a REIT built around large resorts and entertainment venues, that cash driven metric often matters more than GAAP earnings when you think about dividend capacity and future reinvestment.
That FFO surprise sits next to revenue of US$655.8 million, which also came in above expectations and reflected Same Store RevPAR metrics that outperformed analyst models. For investors watching catalysts such as the Grande Lakes Orlando integration, higher 2026 capex and interest coverage, this combination of stronger FFO and top line outturn provides more room for execution, while still leaving balance sheet and project return risks firmly on the table.
Ryman Hospitality Properties Analyst Expectations in Focus
Ryman Hospitality Properties' narrative projects revenues of US$3.7 billion and earnings of US$466.3 million by 2029. This is based on an annual revenue growth rate of 10.3% and an earnings increase of about US$194 million from current earnings of US$271.9 million.
Uncover how Ryman Hospitality Properties' fair value indicates a 4% potential upside to its current price that could narrow quickly.
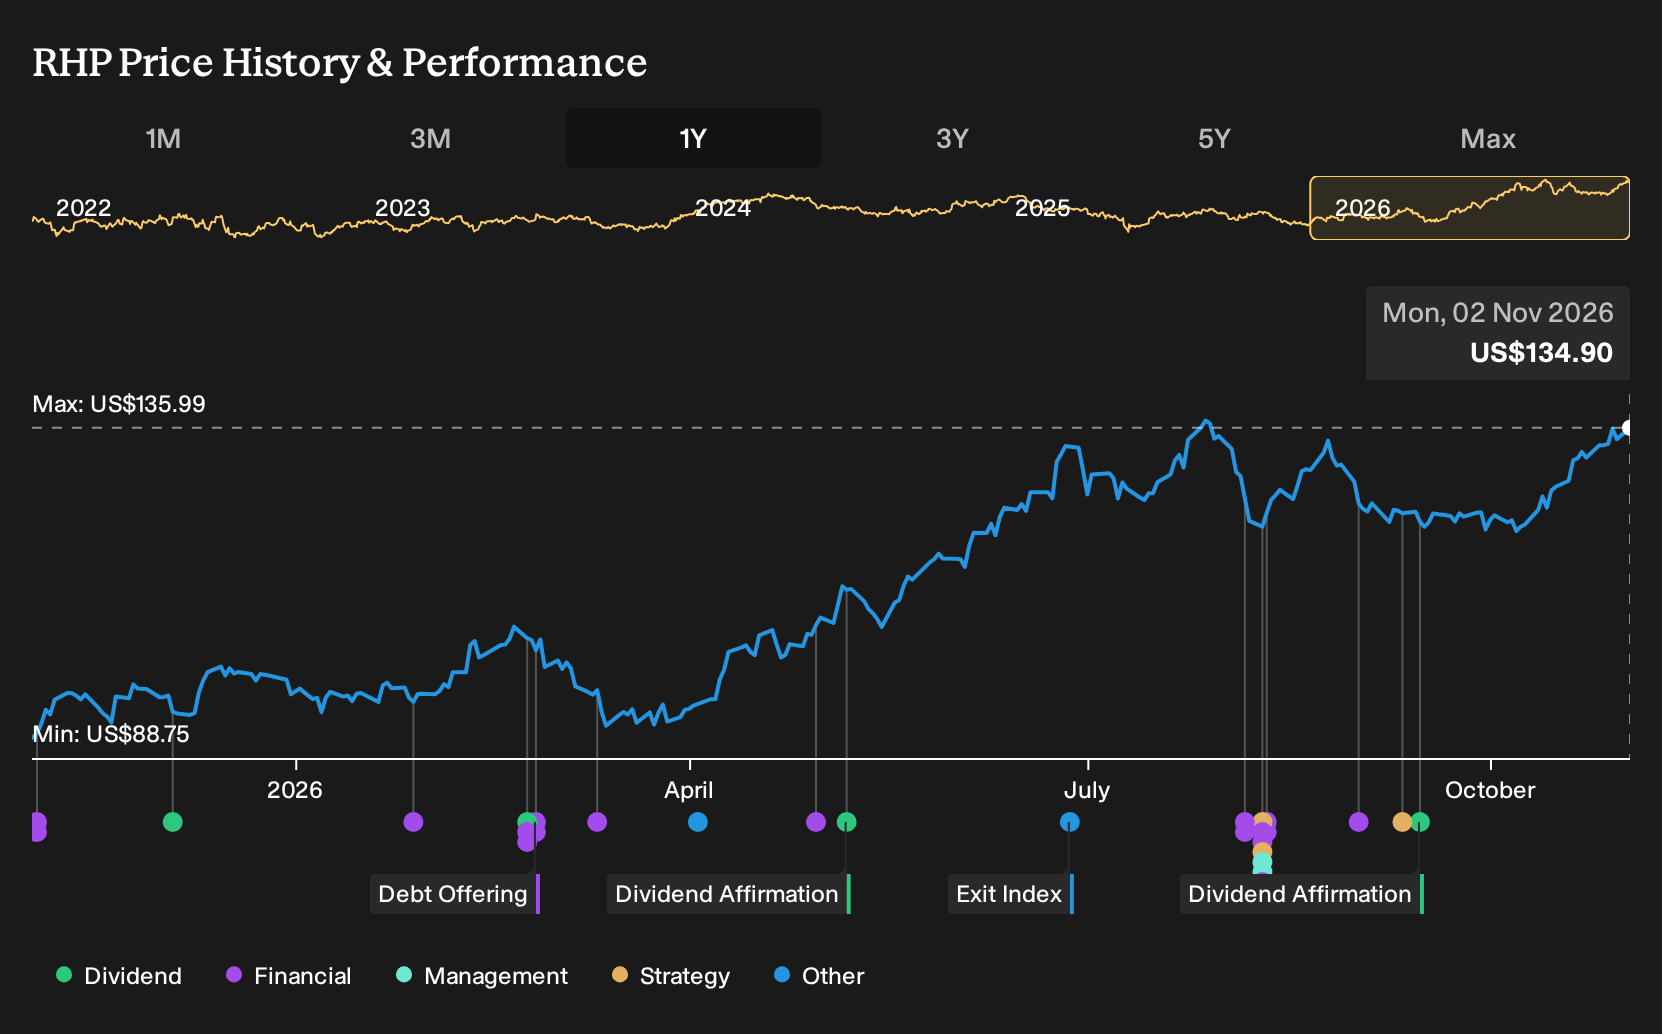
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community bracket Ryman Hospitality Properties between about US$140 and US$214 per share, which is a wide band for just a pair of retail models. Before updated forecasts land after the latest earnings surprise and higher capex plans, recognise how far investor opinions can spread, and explore several alternative viewpoints.
Explore another Ryman Hospitality Properties fair value estimate, including one that suggests it could be worth just $139.79.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Ryman Hospitality Properties research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ryman Hospitality Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ryman Hospitality Properties' overall financial health at a glance.
Looking for more Ryman Hospitality Properties style investment ideas?
If the Ryman Hospitality Properties story has sharpened your thinking, use that momentum to widen your watchlist. A focused screener can help you spot other businesses with balance sheets, cash flows and income profiles that suit your approach.
- For investors who want potential mispricing on their side, scan a curated set of 34 high quality undervalued stocks that combine solid fundamentals with room for sentiment to shift.
- If resilience matters most to you, filter for companies in our 29 resilient stocks with low risk scores and concentrate on businesses that score well on financial strength and volatility.
- When you prefer quality that is not yet crowded, look through a targeted pool of 19 high quality undiscovered gems that pair strong metrics with relatively low investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com