


EN
3 Australian Quality Stocks With ROE Over 50%
AustralianSuper’s recent focus on AI “picks and shovels” shows how big money is still trying to work out where to place its chips. That leaves smaller Australian companies with solid balance sheets and real earnings power trading off the radar. This article walks through three underfollowed high quality local stocks from a specialist screener so you can see what professional investors might be missing today.
The three stocks highlighted below are only a starting sample from this High-Quality Undiscovered Gems idea, and the full screen surfaced 11 more businesses with equally compelling stories that are not covered here. If you want to move faster than the upgrade notes and actively spot potential future leaders before the crowd, head straight into the High-Quality Undiscovered Gems screener to identify, filter and analyze the highest conviction opportunities.
Australian Ethical Investment (ASX:AEF)
Overview: Australian Ethical Investment is a Sydney based fund manager running ethical equity, fixed income and balanced funds, including active small cap strategies targeting under researched opportunities.
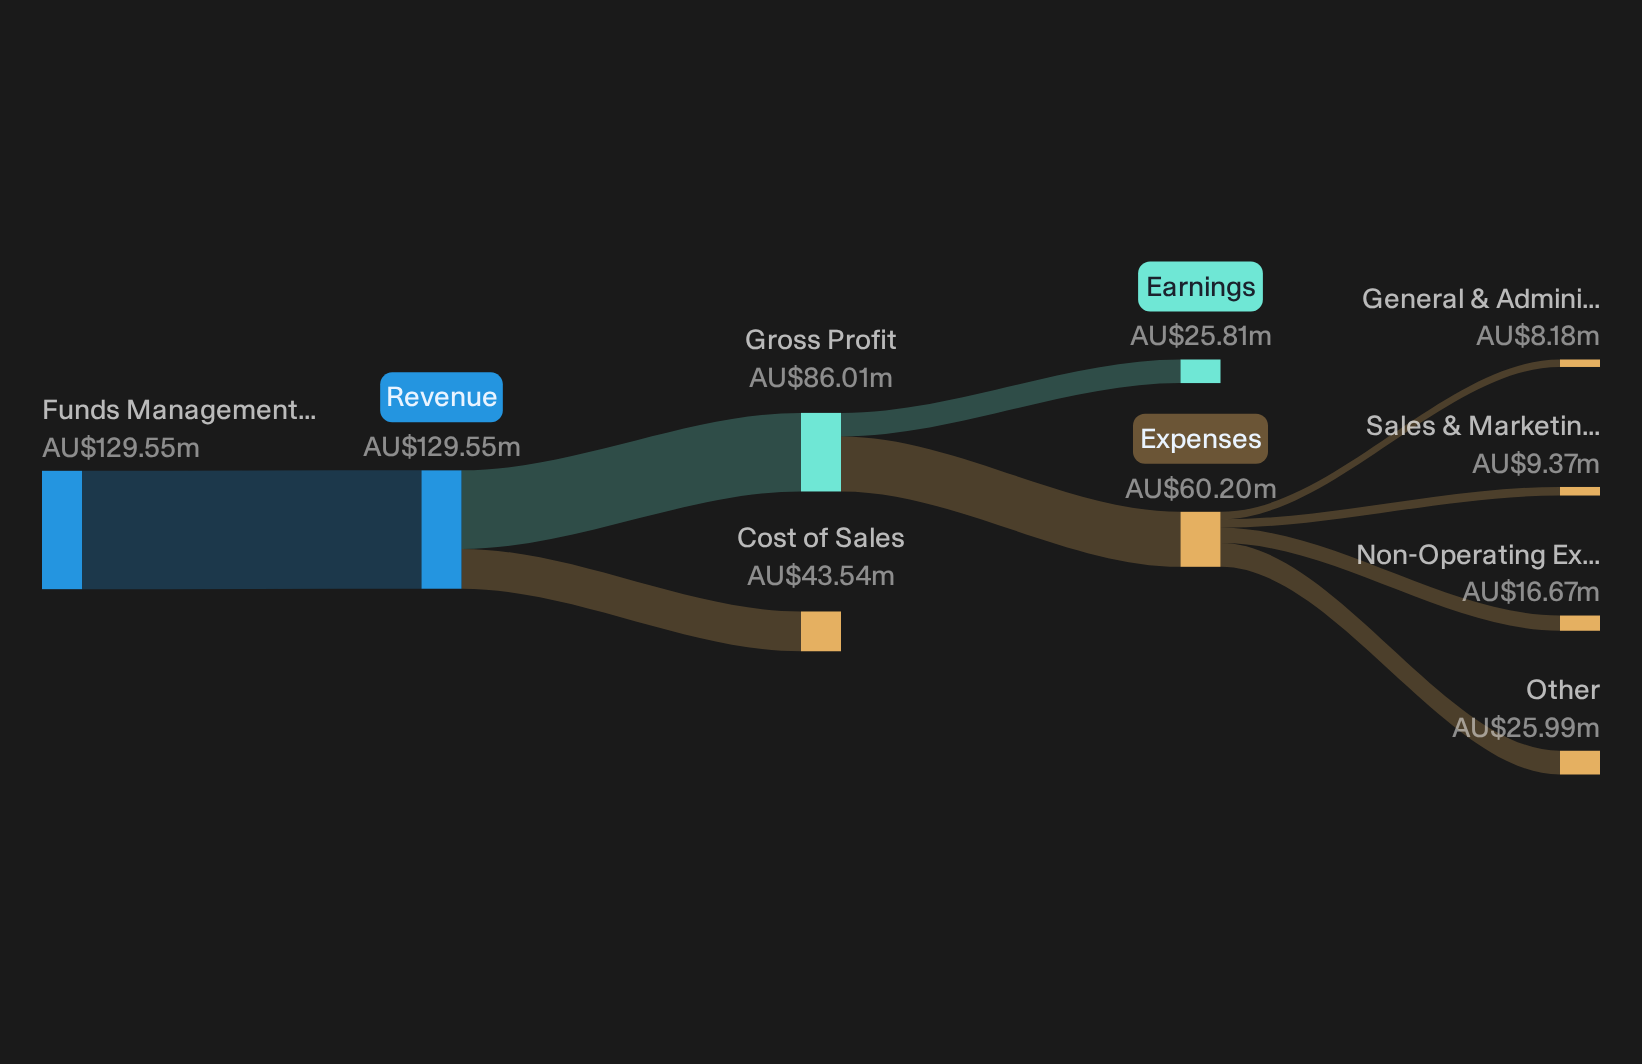
Operations: The group generates A$129.55 million in revenue from funds management activities, all sourced from Australian clients and products.
Market Cap: A$499 million
Australian Ethical Investment matters for this High Quality Undiscovered Gems theme because its small cap funds are specifically built to focus on the under the radar companies many big institutions overlook.
"Growing preference for ethical investment continues to support Australian Ethical Investment, with rising interest from NGOs, charities, foundations and family offices and an estimated A$50b Australian foundation pool, which can support higher net inflows and revenue growth if more of this segment allocates to its values aligned products."
For investors watching Australian Ethical Investment, a single unresolved pressure on revenue margins could end up mattering far more than headline inflows.
That pressure point is exactly where the thesis gets interesting, and the full narrative for Australian Ethical Investment unpacks how Australian Ethical Investment’s margin story could decouple from headline flows.
SKS Technologies Group (ASX:SKS)
Overview: SKS Technologies Group designs and installs audiovisual, electrical and communications systems for Australian boardrooms, stadiums and large commercial sites.
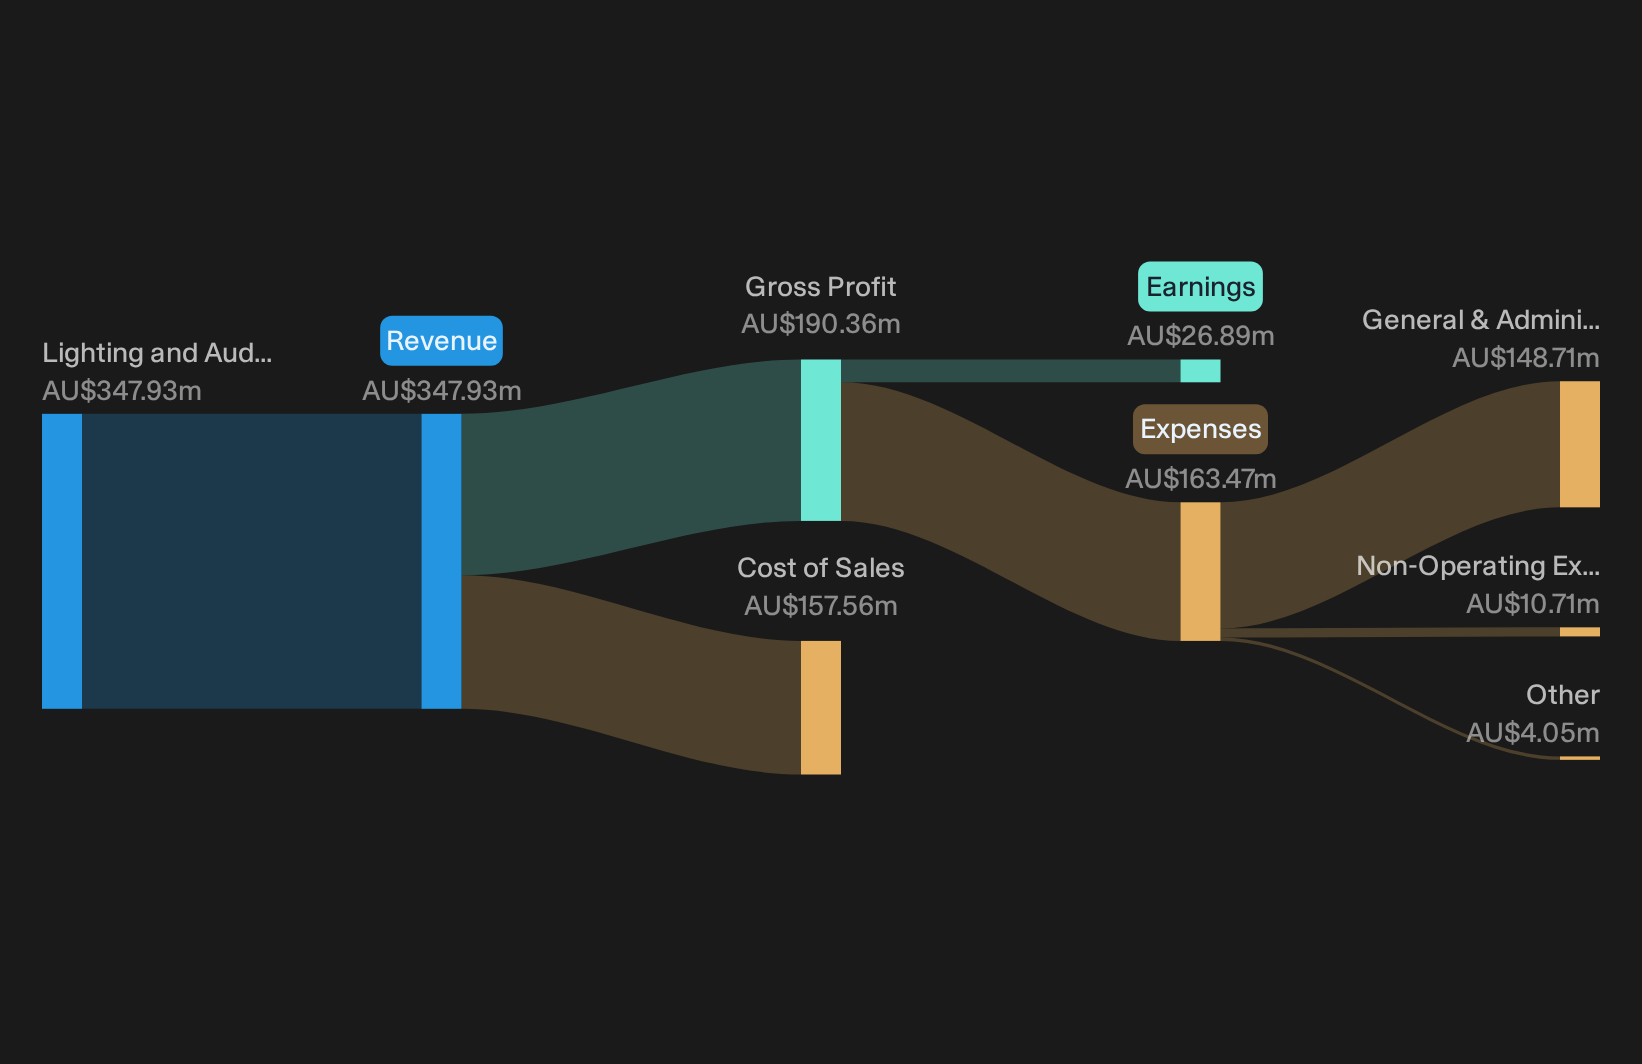
Operations: SKS Technologies Group generates about A$347.93 million in revenue from lighting and audiovisual markets, all from Australian projects and clients.
Market Cap: A$685.3 million
SKS Technologies Group fits this High-Quality Undiscovered Gems theme through its workhorse role behind AV-over-IP projects that power smart boardrooms, stadium screens and enterprise control rooms, turning underappreciated infrastructure spending into potentially scalable earnings.
"The rapid acceleration of digital transformation and surging demand for data centers is driving significant growth in SKS Technologies' project pipeline, as evidenced by a 92% increase in revenue and a 46% rise in tender activity year-on-year, which the company views as pointing to strong revenue growth prospects over the coming years."
What really tests that upbeat picture is how one unseen cost and pricing pressure shapes future contract quality rather than just contract volume.
That contract quality question is exactly what the full narrative for SKS Technologies Group tackles, separating accelerating headline activity from the real profit drivers SKS Technologies Group investors need to watch.
EDU Holdings (ASX:EDU)
Overview: EDU Holdings runs higher education and vocational colleges in Australia, training domestic and international students for skills-shortage fields like counselling, community services and early childhood education.
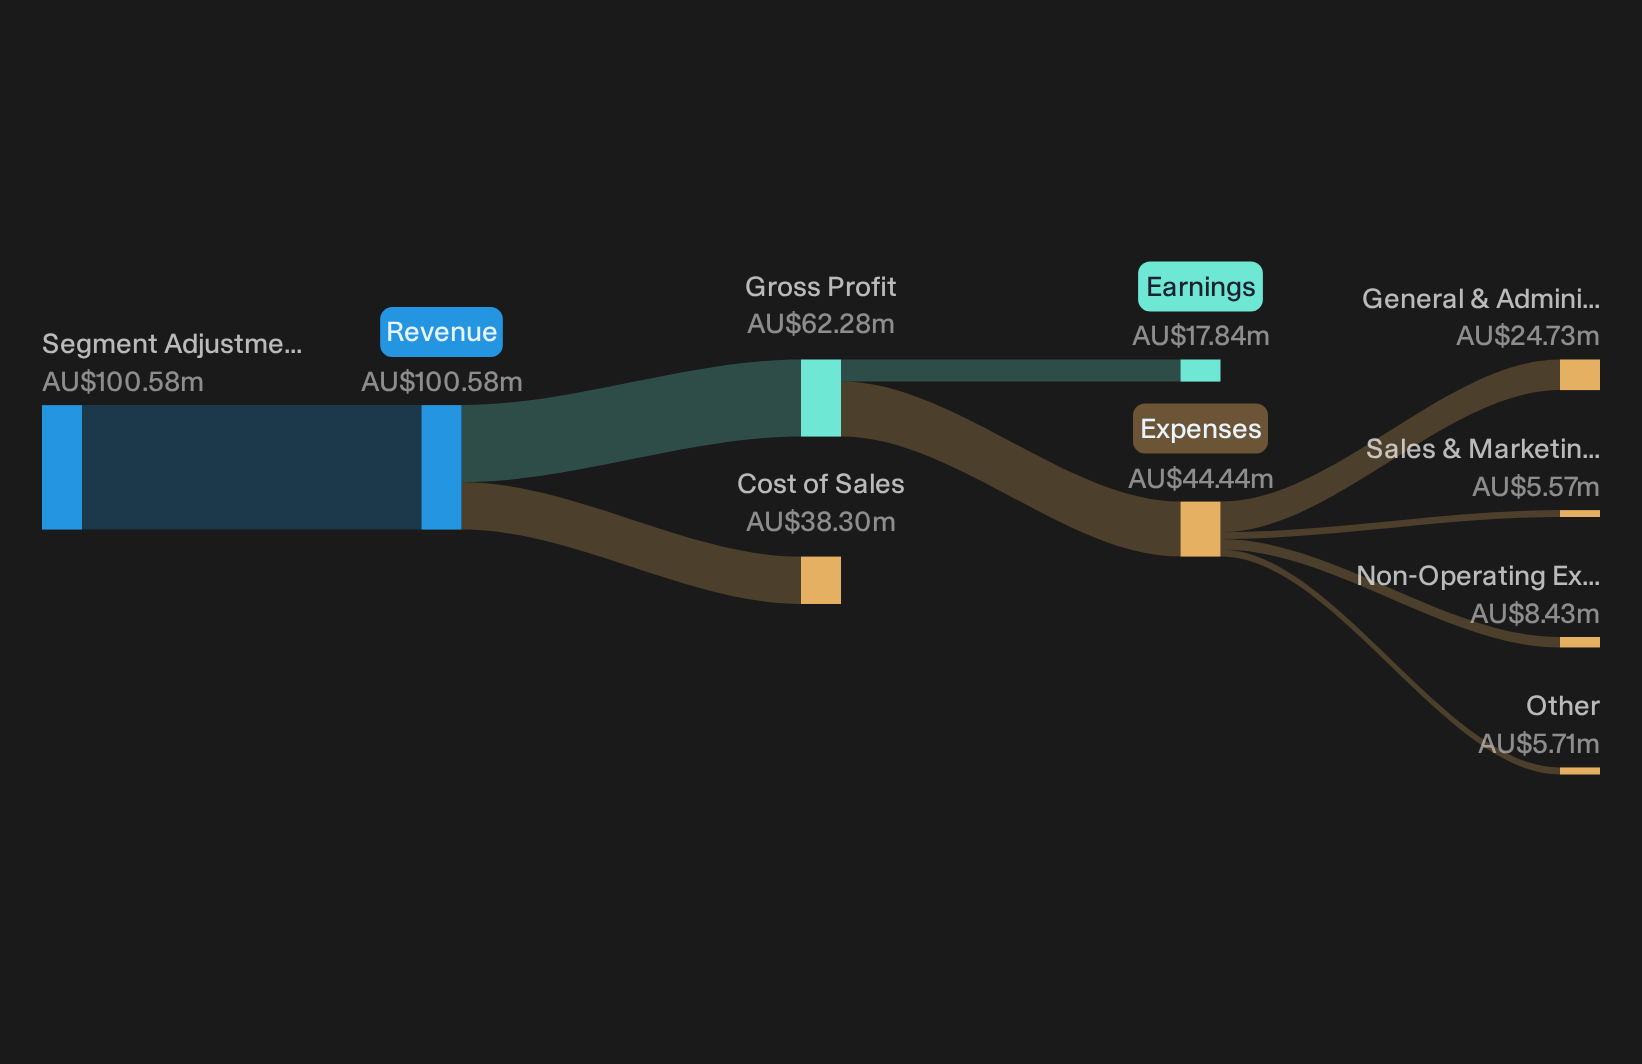
Operations: EDU Holdings generates A$100.583 million in education revenue, all from Australian operations across its tertiary and vocational training offerings.
Market Cap: A$108 million
EDU Holdings fits the High-Quality Undiscovered Gems theme through its Ikon and ALG units, where practical degrees and training in shortage occupations quietly underpin a repeatable, fee-paying student base that big funds often overlook.
"The single biggest risk is regulatory. A minister can wake up tomorrow and decide private education providers are politically inconvenient."
What really shapes EDU Holdings’ long term appeal is how one future policy call filters through to student demand, pricing power and profitability.
That policy risk is exactly why the full narrative for EDU Holdings looks at how EDU Holdings could turn regulation, pricing and student demand into accelerating earnings power beyond the headline worry.
Seeking Alternatives Before The Crowd Moves?
Fresh ideas get crowded fast. Once momentum builds and capital flies in, the cleanest entry points vanish. Scan these under the radar picks while it matters and get in early.
- Target resilient cash generators before wider attention drives interest higher by combing through the 2 high quality undervalued stocks that filters for quality businesses with support from both earnings and balance sheets.
- Ride the structural push into machine intelligence by tracking the 53 AI infrastructure stocks powering data centers, chips and networks while many investors are still focused on front end AI stories.
- Position ahead of potential supply crunches by checking the curated 33 best rare earth metal stocks geared to companies tied to critical minerals for batteries, electrification and advanced manufacturing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com