


EN
Is Century Communities (CCS) Undervalued After Lower Earnings And Cut 2026 Guidance?
Century Communities (CCS) has drawn fresh attention after reporting lower third quarter and nine month revenue and net income, along with trimmed 2026 home delivery and sales guidance linked to weaker orders in a higher mortgage rate backdrop.
Recent trading reflects that pressure. Century Communities’ share price has fallen 22.43% over the past 90 days and is down 7.43% on a year-to-date basis. The 1-year total shareholder return has declined 4.74%, pointing to weakening momentum despite ongoing community launches and new projects.
Compare Century Communities’ recent pullback with other housing-focused builders that our analysts have already filtered for balance sheet strength and fundamentals in the list of solid balance sheet and fundamentals (24 results).
Century Communities is still building and selling thousands of homes, yet the share price has slid hard on weaker earnings and guidance. Is that slump giving you a fair entry or a value trap at US$54.56?
Most Popular Narrative: 24% Undervalued
At a last close of $54.56 against a widely followed fair value of $72, the current Century Communities share price reflects a sharp discount that the prevailing narrative links to earnings pressure, incentives and a higher discount rate.
Century Communities has assembled more than 60,000 owned and controlled lots and a record 330 open communities, which management believes can support multi year delivery growth once demand improves and could lift homebuilding revenue if volumes rise against a largely fixed overhead base.
Company wide initiatives that brought cycle times down to roughly 112 to 115 days and cut direct construction costs sequentially through late 2025 and early 2026 may allow Century Communities to convert future revenues into stronger gross and net margins as incentive levels eventually reflect healthier affordability.
See why 5 investors see Century Communities as 24% undervalued.
Result: Fair Value of $72 (UNDERVALUED)
Still, Century Communities faces real pressure if elevated incentives and a BB minus credit rating keep funding costs high and prevent margins from matching the upbeat narrative.
Find out about the key risks to this Century Communities narrative.
Another View: Century Communities Through A Cash Flow Lens
The earlier narrative leans on earnings forecasts and a US$72 fair value, yet Simply Wall St’s DCF model paints a very different picture. On that cash flow view, Century Communities at US$54.56 is trading above an estimated future cash flow value of US$24.52, which frames the stock as expensive rather than discounted. Which story do you treat as your anchor?
Before leaning too heavily on either lens, it helps to understand how long term cash flows, discount rates and terminal assumptions feed into that gap. Then compare them with your own expectations for Century Communities’ cycle, orders and margins, plus how long you think incentives and higher funding costs might hang around. Look into how the SWS DCF model arrives at its fair value.
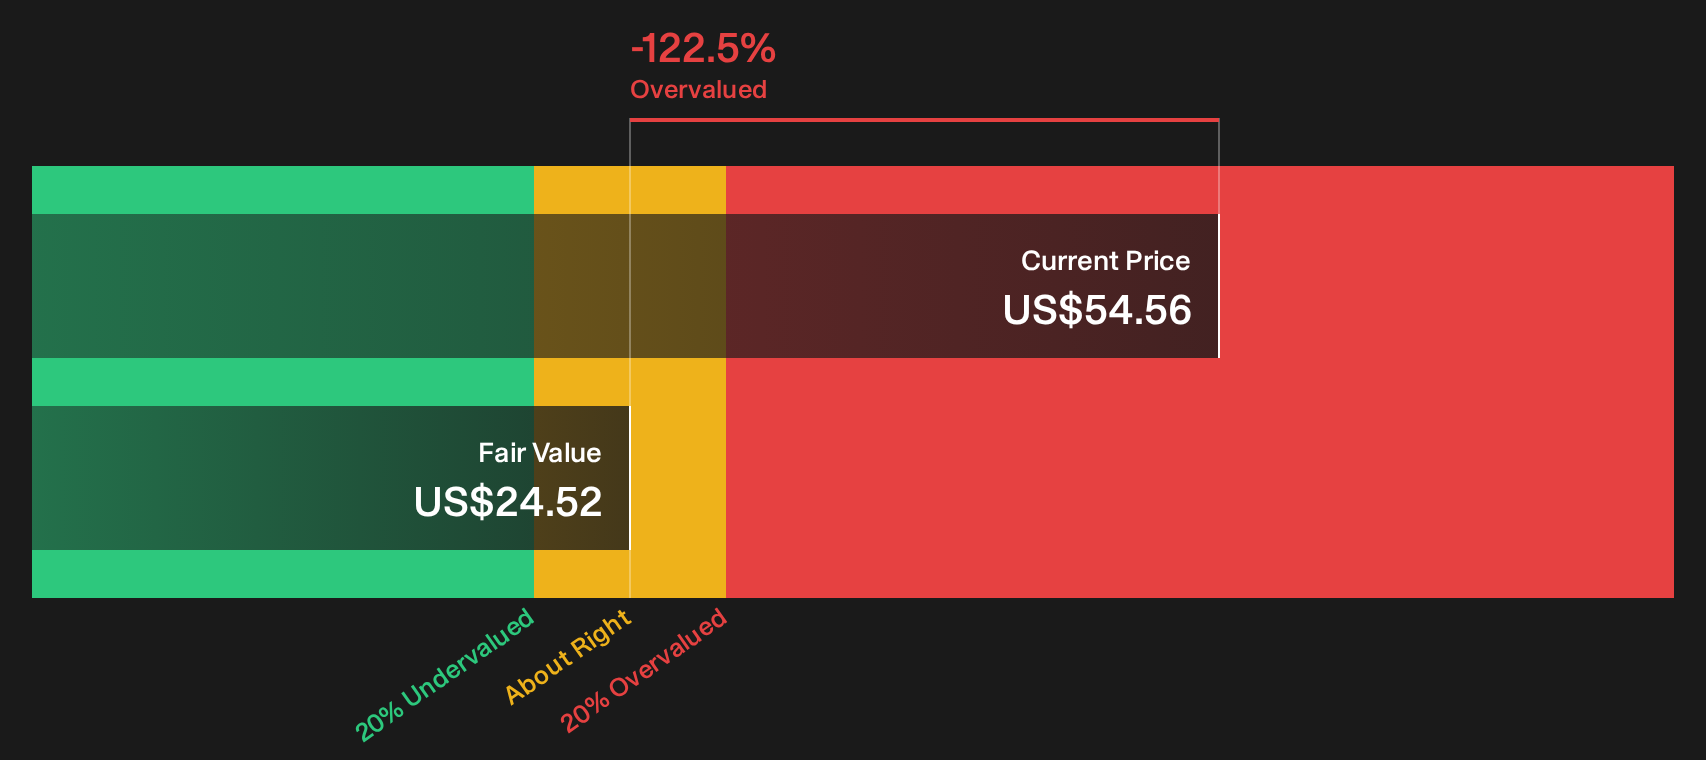
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Century Communities for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Century Communities is clearly mixed right now, so move quickly, review the full data set and weigh both sides of the story yourself with 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Century Communities?
If Century Communities has sharpened your focus, do not stop with a single builder when plenty of other potential opportunities are just a filter away.
- Target quality at a discount by scanning companies our analysts flag as attractively priced through the 34 high quality undervalued stocks.
- Prioritise resilience by reviewing a curated 29 resilient stocks with low risk scores that aims to keep drawdowns in check when conditions get choppy.
- Hunt for future leaders early by checking the 19 high quality undiscovered gems while they still fly under most investors’ radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com