


EN
Mohawk Industries (MHK) Holds Margins In Q3, Is The Rally Already Priced In?
Mohawk Industries (MHK) is back in focus after third quarter 2026 results showed earnings holding up against softer volumes and higher input costs, with an adjusted EBITDA margin of 12.7% and a sharper focus on cash.
The latest move in Mohawk Industries' share price helps explain why the stock is back on investors' radar. A 6.6% one-day share price return and a 20.5% seven-day share price return around the Q3 release, alongside the buyback update and portfolio review, point to improving momentum. This comes after a 35.7% year-to-date share price return and a three-year total shareholder return of 79.7%, even though the five-year total shareholder return is still down 15.5%.
Scan how Mohawk Industries stacks up against other building products and materials stocks by reviewing our hand picked list of solid balance sheet and fundamentals (24 results).
Bulls see Mohawk Industries using solid cash generation and portfolio pruning to justify the rally. Bears focus on softer volumes and a five year return still in the red. Which side does the current valuation support?
Most Popular Narrative: 9% Overvalued
The most followed narrative pegs Mohawk Industries' fair value at $136.47, which sits below the last close of $148.58 and frames the recent rally as pricing in a lot of good news already, including restructuring and capital returns.
The current valuation, along with the view that Mohawk Industries is fairly valued and seen positively, suggests that the share price already reflects both the cyclical risks and the potential benefits of restructuring, capital returns, and any future flooring demand recovery.
See why 8 investors see Mohawk Industries as 9% overvalued.
Result: Fair Value of $136.47 (OVERVALUED)
Still, the Mohawk Industries story can shift quickly if flooring demand stays weak or if higher input costs squeeze margins and cash generation more than expected.
Find out about the key risks to this Mohawk Industries narrative.
Another View: Mohawk Industries Through The P/E Lens
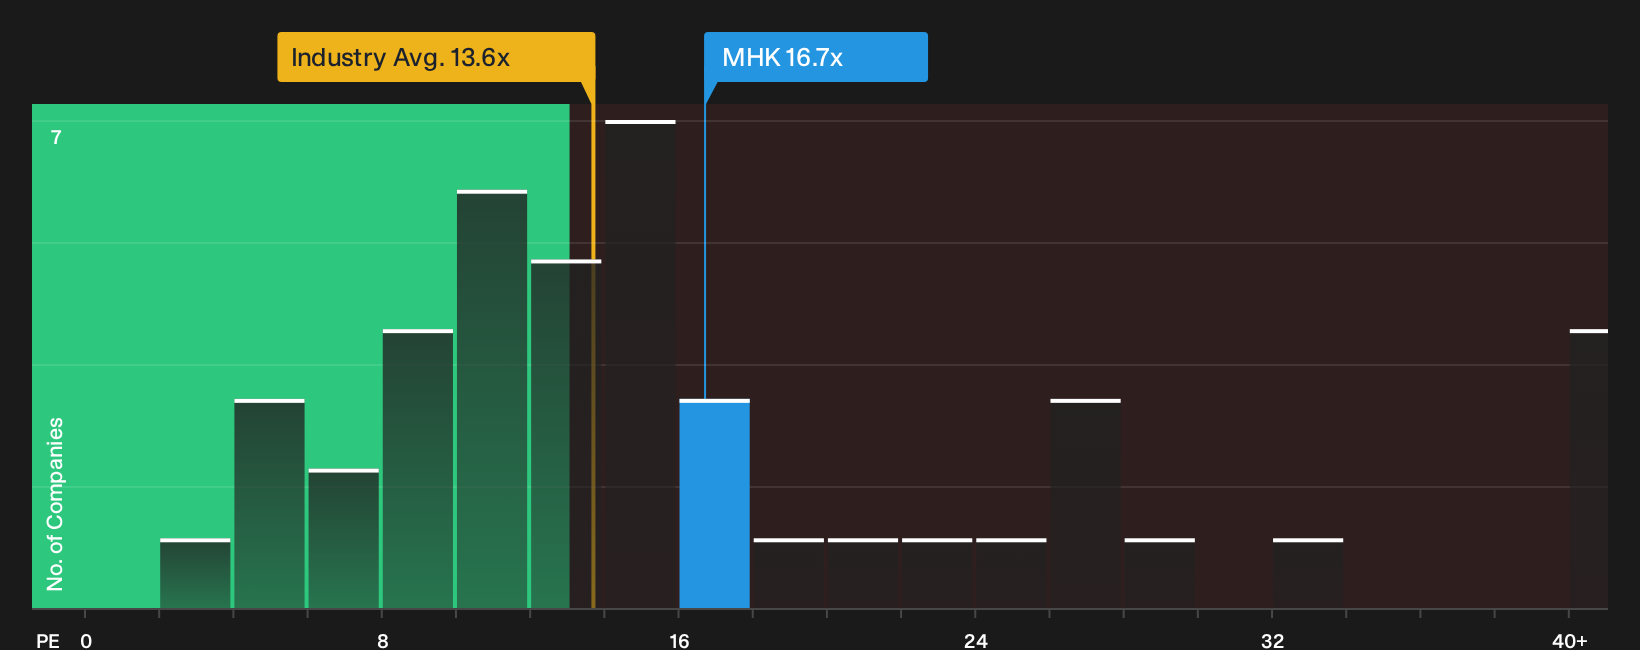
A different lens tells a different story. On a P/E of 16.7x, Mohawk Industries trades richer than the US Consumer Durables sector at 13.6x and also above its peer average of 15.9x. Yet the fair ratio of 18.4x implies the market could still move higher before the stock looks stretched by this yardstick.
That mix of a higher headline multiple and room to close the gap to the fair ratio points to a trade off for investors between paying up today and the risk that sentiment later swings back toward the industry and peer averages. The key question is how investors weigh that balance.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Mohawk Industries' valuation make this a judgment call rather than a foregone conclusion, so move quickly through the data and decide where you land. To see the balance of concerns and potential upside in one place, review the 3 key rewards and 2 important warning signs
Looking for more Mohawk Industries sized ideas?
If Mohawk Industries has you rethinking your watchlist, do not stop here. Broader opportunity sits in how you filter the market, not just in one ticker.
- Target resilience first and scan for companies with steadier profiles using our 29 resilient stocks with low risk scores.
- Zero in on value by reviewing a curated pool of potential mispriced opportunities through the 34 high quality undervalued stocks.
- Lean into staying power and income by checking out companies on the 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com