


EN
CGN Mining (SEHK:1164) Reported Third Quarter Uranium Output, Is The Stock Still Expensive?
CGN Mining (SEHK:1164) has released new operational data, reporting unaudited third quarter natural uranium output of 642.4 tU for the period ended September 30, 2026.
At a share price of HK$2.095, CGN Mining has seen short term momentum pick up, with a 1 day share price return of 1.21% and a 7 day gain of 3.20%. However, the stock remains down 35.34% on a year to date share price basis, and the 1 year total shareholder return has declined 42.15%. This comes after a 3 year total shareholder return of 53.37% and a 5 year gain of 99.67%, which point to a much stronger longer run.
Scan CGN Mining alongside hand picked peers exposed to the nuclear fuel cycle by checking out the 16 nuclear energy infrastructure stocks in the same session.
After the recent bounce in CGN Mining despite a steep one year decline, the stock still trades well below analyst targets and an estimated intrinsic value. Is the market’s caution sensible, or has it swung too far?
Preferred P/E of 36.2x: Is it justified for CGN Mining?
On earnings multiples, CGN Mining looks expensive. The stock trades on a P/E of 36.2x while the current price is HK$2.095, compared with both sector and peer averages that sit close to 10x.
The P/E ratio compares what investors are paying for each dollar of profit. For a uranium trading specialist like CGN Mining, a higher multiple usually signals the market is factoring in strong profit expansion or a quality earnings profile rather than just today’s income statement.
Here, the numbers pull in different directions. On one side, 1164 has what is described as high quality earnings, net profit rose 30.1% over the past year, and earnings have grown 11.4% per year over 5 years, with margins improving from 5.4% to 6.1%. Revenue is forecast to rise 23.2% per year and earnings are expected to increase 32.5% per year, with Return on Equity projected at 20.8% in three years. On the other side, the current Return on Equity is 9.8%, which is considered low, the value score is 2 out of a possible higher score, and all liabilities come from higher risk funding sources rather than customer deposits.
Relative to other measures, the premium looks even steeper. The P/E of 36.2x is described as expensive versus the Asian Oil and Gas industry average of 10.6x and also expensive when set against the peer average of 10.1x. It is also high compared with an estimated fair P/E of 11.3x, which is a level the market could move towards if sentiment cools and growth execution disappoints expectations.
Explore the SWS fair ratio for CGN Mining.
Result: Price-to-earnings of 36.2x (OVERVALUED)
Still, CGN Mining faces clear risks if uranium demand softens or funding costs rise. These factors could pressure margins and challenge the case for a premium P/E.
Find out about the key risks to this CGN Mining narrative.
Another View on CGN Mining’s Value
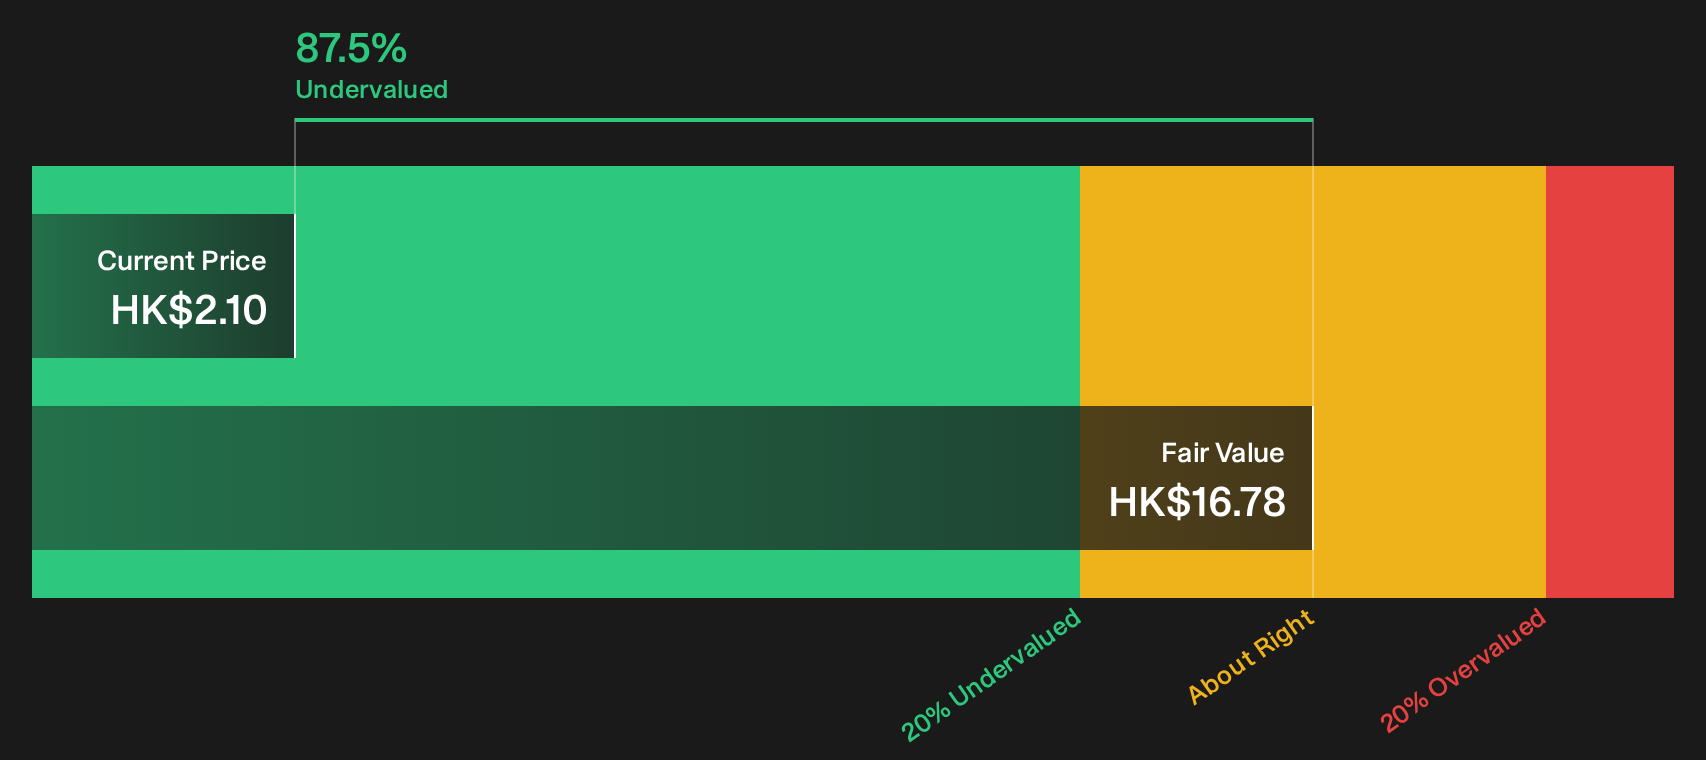
The high P/E paints CGN Mining as expensive, yet the SWS DCF model points the other way. On that approach, the shares trade around 87.5% below an estimated future cash flow value of HK$16.78 per share, which frames today’s HK$2.095 price as heavily undervalued. Which signal do you trust more?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CGN Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 193 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on CGN Mining so far. If the cross currents feel confusing, move quickly and test the thesis against the data yourself. Then weigh those positives by checking the 3 key rewards
Looking for more investment ideas beyond CGN Mining?
If CGN Mining has sharpened your thinking, do not stop there. Broaden your watchlist and put more opportunities on your radar while this research is fresh.
- Target potential mispricings by scanning a carefully filtered set of 193 high quality undervalued stocks that combine stronger fundamentals with appealing valuations.
- Build a more dependable income stream by focusing on 221 dividend fortresses that aim to pair higher yields with resilient business models.
- Sleep a little easier by reviewing 216 resilient stocks with low risk scores chosen for sturdier balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com