


EN
How Investors May Respond To Morgan Sindall Group Stock Stable UK Partnerships
- Morgan Sindall Group has been highlighted for its broad UK construction and regeneration exposure, covering infrastructure, social and affordable housing, and long-term maintenance and refurbishment work that reflects a sizeable secured and preferred-bidder pipeline.
- An extensive regeneration and housing pipeline of about 55,000 homes, alongside long-duration public-sector partnerships, underlines how a large portion of Morgan Sindall Group’s future workload is already identified. This can help frame expectations around revenue visibility and project delivery.
- We will now look at how Morgan Sindall Group’s long-term regeneration pipeline shapes the investment narrative built around its diversified UK operations.
Scan other UK-focused contractors and regeneration specialists built around long-term public-sector work by checking out the curated 5 resilient stocks with low risk scores alongside Morgan Sindall Group.
Morgan Sindall Group Investment Narrative Recap
To own Morgan Sindall Group, you need to believe its broad UK footprint in construction, infrastructure and regeneration keeps feeding that secured and preferred bidder pipeline into work on site. The key short term swing factor is how quickly regeneration schemes and the 55,000 home pipeline convert from planning into build phases, given viability checks and funding hurdles.
The biggest operational risk right now is that projects within Partnership Housing and Mixed Use Partnerships tie up capital for longer than expected or see further delays, which can hold back returns and margin progress. The recent news about long term regeneration visibility mainly reinforces the existing thesis rather than changing it.
Recent commentary around an enlarged infrastructure and energy workload, with about £5.8b of line of sight work including roughly £4b in Energy & Power, feels most relevant to this regeneration story. It points to Morgan Sindall Group leaning on multi year public frameworks that can offset timing bumps in housing led schemes.
For you as a shareholder, the operational question is execution. If infrastructure frameworks ramp cleanly while regeneration phases through planning without extended resequencing, the group has multiple levers to support earnings, even if Fit Out activity normalises from recent levels. If viability challenges persist, the risk is more about timing of profit recognition than about pipeline quantity.
What The Analyst Framework Implies For Morgan Sindall Group
Morgan Sindall Group's long regeneration pipeline sits against analyst assumptions that are fairly steady rather than aggressive. The consensus view points to revenue rising by 3.1% a year over the next three years while profit margins ease from 3.6% today to 3.3% by 2029. Earnings are pegged at £189.0 million now and are also expected to be about £189.0 million in 2029, so the implied earnings change is flat in both value and growth terms over that period. The forecast year matters because those 2029 estimates anchor a price target that assumes the business can turn a £5.7b revenue line into that same £189.0 million profit figure.
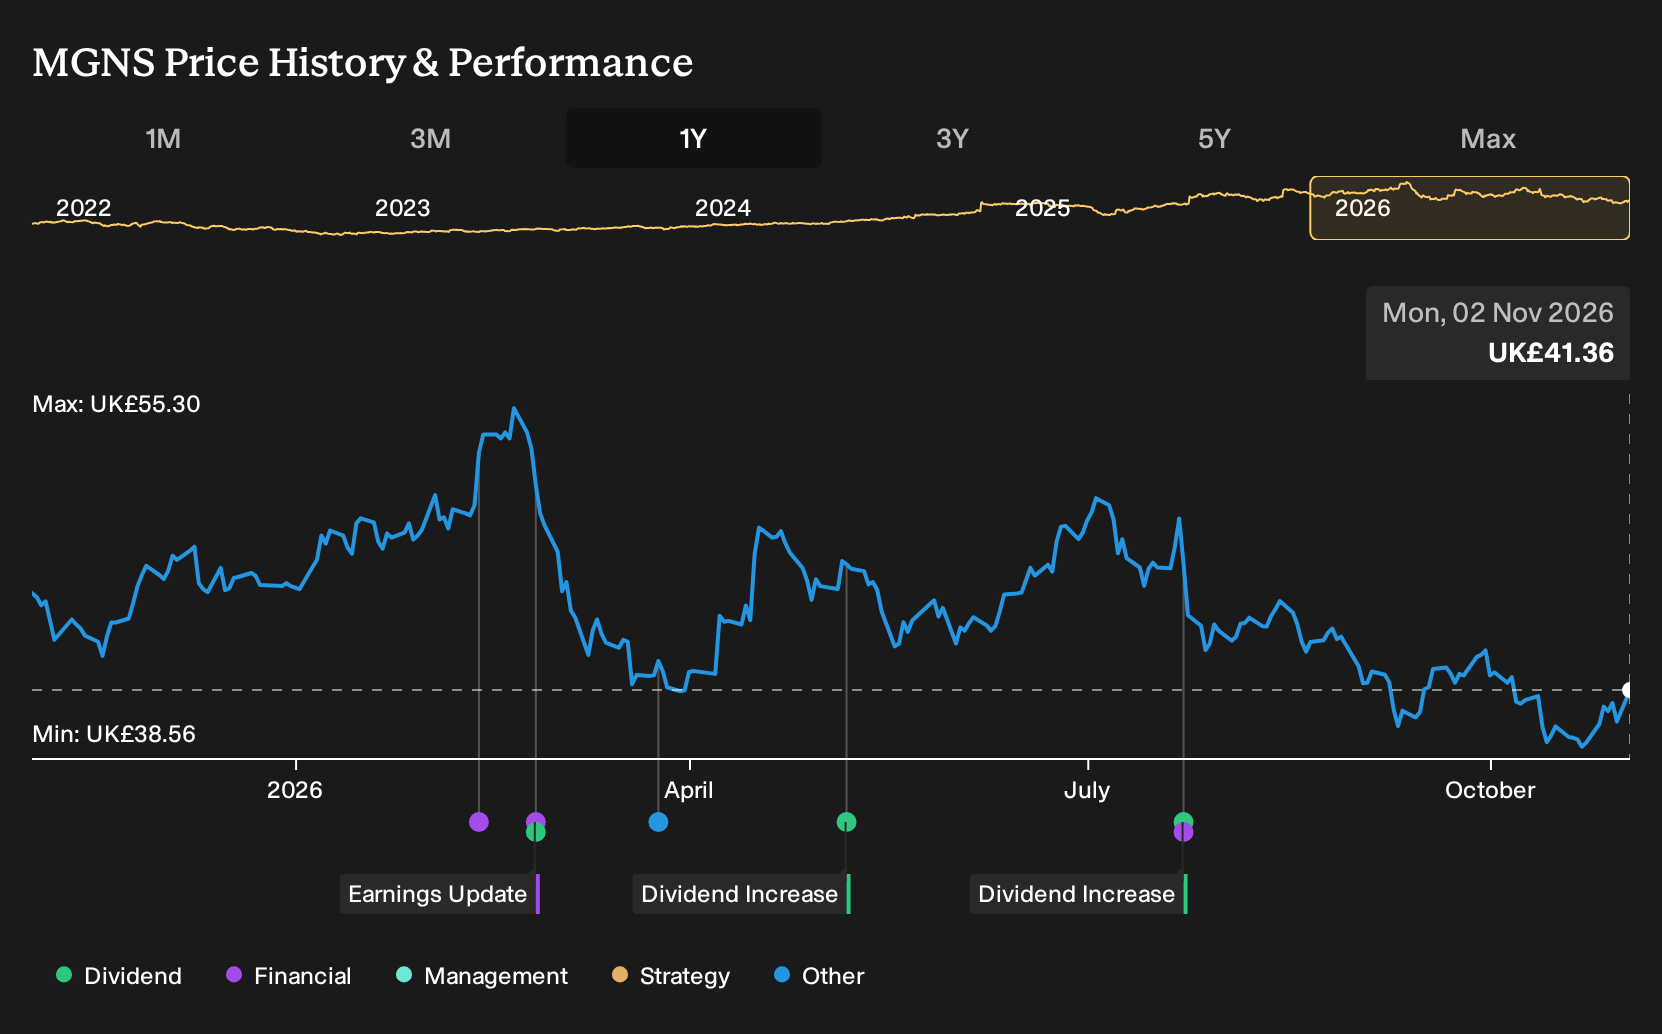
On those forecasts, the future multiple does the heavy lifting. To line up with the analyst target, Morgan Sindall Group would need to trade on a P/E of 18.3x those 2029 earnings, compared with 9.6x today and above the current 16.3x for the wider UK construction peer group. The consensus price target of £56.21 sits 31.0% above the current £38.76 share price as of late 2026, framed by a bullish end of £62.0 and a cautious end of £48.0. All of that is discounted back using a cost of capital of about 9.4% to 9.42%. The key swing factor for you is whether those inputs feel realistic given the regeneration exposure, the capital tied up in housing schemes and the potential for timing friction in getting projects on site.
Morgan Sindall Group's narrative projects £5.7b revenue and £189.0 million earnings by 2029. This requires 3.1% yearly revenue growth and no earnings change from the current £189.0 million level.
Uncover why Morgan Sindall Group's fair value indicates a 36% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between £49.34 and about £56.21, so private investors are working with a relatively tight band around Morgan Sindall Group. Those opinions were formed before the latest regeneration news, and risks around Fit Out normalisation and tied up housing capital could still reshape future sentiment. Readers can use this spread of views as a prompt to test their own assumptions against several alternative perspectives.
Explore 3 other Morgan Sindall Group fair value estimates, including one that suggests it could be worth just £49.34.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Morgan Sindall Group research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Morgan Sindall Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Morgan Sindall Group's overall financial health at a glance.
Looking For More Ideas Beyond Morgan Sindall Group?
Once you have formed a view on Morgan Sindall Group, it can help to stress test that conviction against other companies with different balance sheets, income profiles and risk levels using the Simply Wall St Screener.
- If you want to focus on companies that aim for steadier profiles, start with a 5 resilient stocks with low risk scores that puts resilience and lower risk scores front and centre.
- If you prefer to concentrate on fundamental strength and financial solidity, use the list of solid balance sheet and fundamentals (10 results) to see which businesses combine robust balance sheets with sound operating metrics.
- If your interest leans toward finding under-the-radar ideas, scan the 5 high quality undiscovered gems that highlight high quality businesses which are not yet widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com