


EN
What Mega Lifesciences Buyers Were Betting On
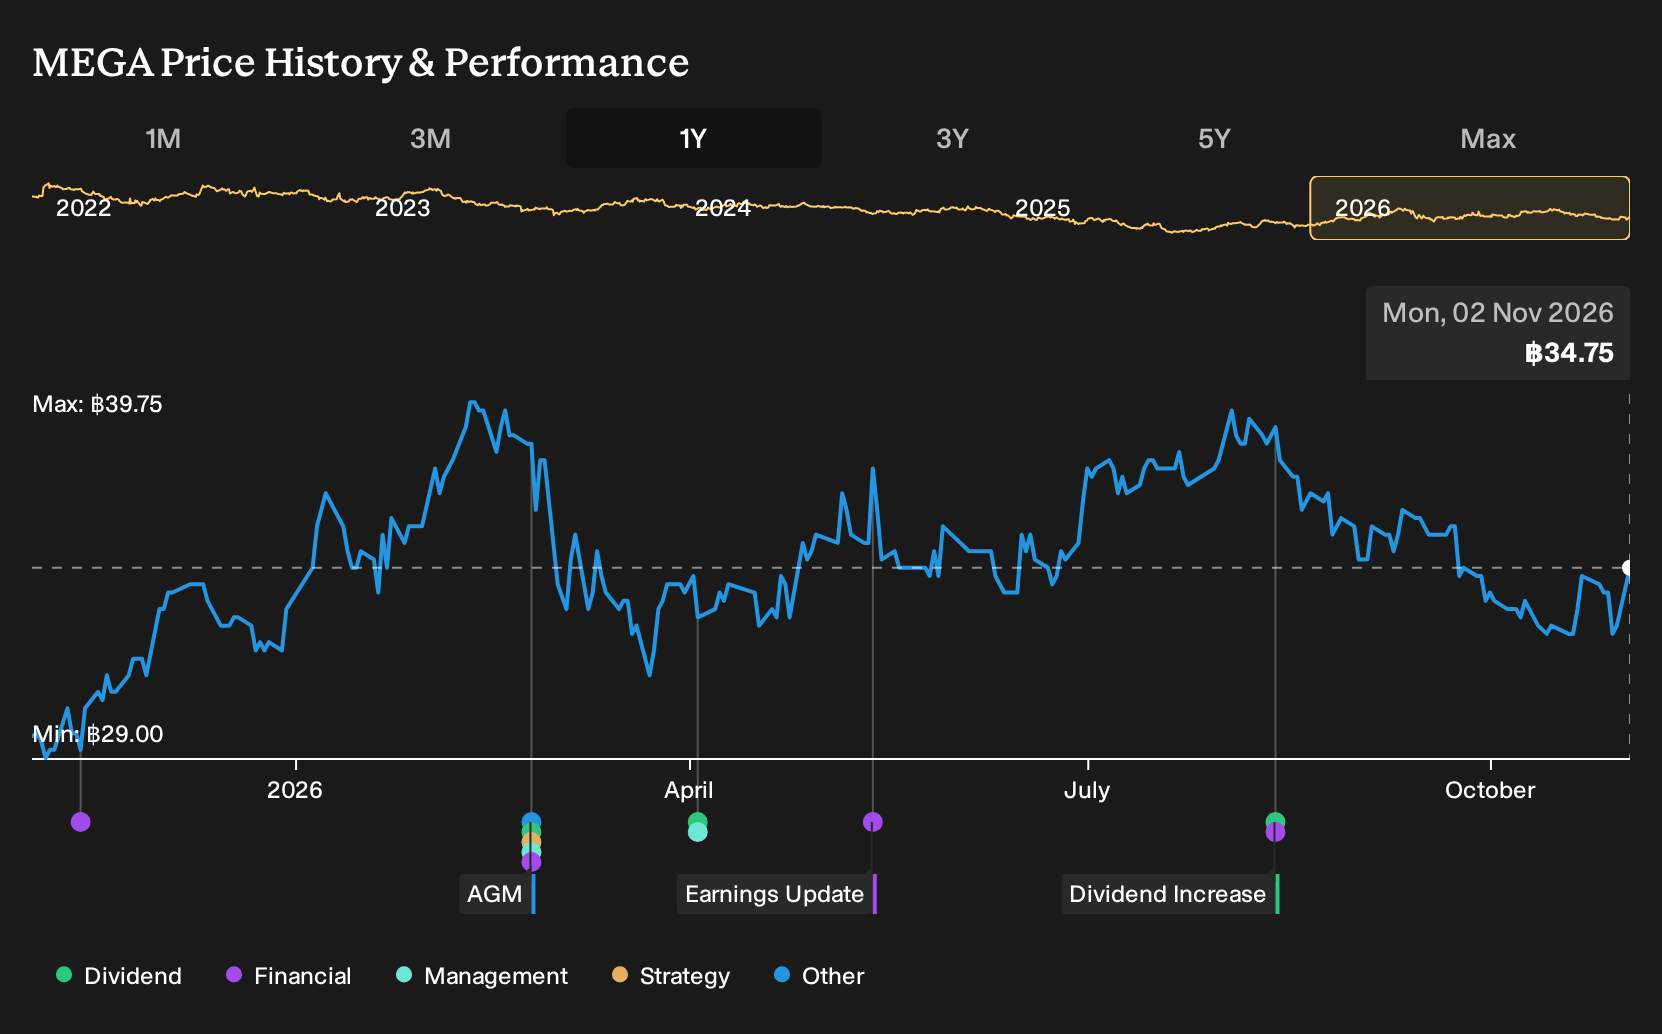
If Mega Lifesciences was on your watchlist rather than in your portfolio, the return may sting. Investors who held Mega Lifesciences over the past year are up 22.3%, including dividends. That outcome lands against a split view from mid 2025, with some analysts arguing aging populations and emerging markets would support wellness demand while others focused on Myanmar scrutiny and FX risks. If you rewind to that disagreement, what might have signalled that the aging and self care thesis deserved more weight?
If the move has made Mega Lifesciences harder to judge, start where the gap is still open and scan 193 high quality undervalued stocks.
The Two Mega Lifesciences Stories Investors Had To Weigh
The shares cost THB29.5 at the start of the period, and anyone looking at Mega Lifesciences then had to choose between two very different but reasonable stories.
On the bullish side, the Narrative argued that aging populations and emerging markets would support wellness demand. The Fair Value of THB39 reflected what those assumptions implied, built on manufacturing expansion in Indonesia and Vietnam and over 120 products in the pipeline.
The bearish view put more weight on Myanmar scrutiny and FX exposure, with a Fair Value of THB26 based on expectations that revenue would gradually decline 0.8% a year and that regulatory pressure and currency swings could keep earnings volatile.
What The Results Changed For The Mega Lifesciences Debate
The clearest fresh fact was Mega Lifesciences lifting both profit and net margin, with net income rising from THB390.918 million to THB514.611 million and net margin moving from 11.4% to 14.5%. That pattern leaned toward the optimistic thesis that discussed stronger profitability, even though both bullish and bearish cases had already pencilled in higher margins.
The takeaway for other stocks is simple. When a story hinges on better profitability, keep checking whether net margin and absolute earnings move together in the reported numbers, rather than relying on revenue alone.
What Mega Lifesciences Buyers Are Being Asked To Believe Now
With Mega Lifesciences now at THB34.75, the selected Narrative frames today’s level as below its own Fair Value figure rather than fully pricing in its thesis.
The argument leans on new manufacturing capacity and steady branded growth, so you need to judge whether disciplined SG&A and cash conversion can actually support that expansion.
"Key Takeaways: Bullish analysts expect Mega Lifesciences to keep compounding its branded and distribution earnings power as new manufacturing capacity comes on line across Indonesia, Vietnam, Myanmar, Thailand and Australia, with gross margins holding near recent ranges. The main thing that has to go right is that the company executes its THB 2.6 to 2.7b capex plan while maintaining disciplined SG&A at about 32 to 33% of sales and sustaining low double digit growth in its branded business across Southeast Asia, Africa and Latin America."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Mega Lifesciences And A Wider Health Bet
The Mega Lifesciences story leans on aging, chronic conditions and self care. That same tide also supports demand for prescription medicines targeting those conditions directly.
Instead of vitamins and supplements, another drug maker focuses on diabetes, obesity, cancer and immune diseases. It develops treatments that doctors prescribe when lifestyle products are not enough.
Its pipeline ranges across cardiometabolic drugs, oncology, neuroscience and genetic medicine. New therapies aim to treat weight, blood sugar, tumors and some brain disorders.
If chronic disease pressure keeps building, that broad treatment portfolio could influence how healthcare investors view pure drug development stories.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 17% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com