


EN
Capstone Copper (TSX:CS) Could Be 37% Undervalued After Soft Q3 Results
Capstone Copper’s softer quarter puts guidance in focus
Capstone Copper (TSX:CS) reported third quarter copper production of 45,218 tonnes, an 18% decline from a year earlier, and a drop in net income, while reaffirming its full year output target.
At around CA$11.39, Capstone Copper’s share price has bounced 3.55% over the last day but remains under pressure, with a 30 day share price return down 21.07% and year to date share price return down 16.06% as investors weigh softer output against reaffirmed guidance. Over a longer stretch, the picture shifts, with total shareholder return down 7.32% over one year yet very strong over three and five years, which suggests recent momentum has faded even though longer term holders have still seen substantial gains.
Spot potential rebounds and under pressure producers alongside Capstone Copper by scanning our hand picked 16 top copper producer stocks that share similar operational and guidance storylines.Capstone Copper has given long term holders strong multi year gains, yet the share price has fallen hard into this softer quarter. Is most of the rerating already in the rear view mirror or still ahead?
Most Popular Narrative: 37% Undervalued
Capstone Copper’s most followed valuation story pegs fair value around CA$18.01, well above the last close at CA$11.39. This puts the focus on whether the Chile and Arizona project slate can support that gap.
The imminent execution of the Mantoverde Optimized project, which management continues to describe as on budget and on schedule with key tie ins targeted for completion during the September maintenance period, is expected to lift sustained sulphide throughput to about 45,000 tonnes per day from early 2027. Investors who believe the current share price underestimates this step up may see upside as higher volumes work through revenue and EBITDA.
See why 36 investors see Capstone Copper as 37% undervalued.
Result: Fair Value of CA$18.01 (UNDERVALUED)
Still, the Capstone Copper story depends on big Chilean builds landing on time and on budget, and on Pinto Valley avoiding another drought driven hit to throughput and costs.
Find out about the key risks to this Capstone Copper narrative.
Another View: SWS DCF Puts Capstone Copper On A Tighter Leash
Capstone Copper looks cheap against the CA$18.01 analyst fair value, yet the Simply Wall St DCF model points the other way, with an estimate of CA$8.76. One approach frames upside, while the other flags downside. Which yardstick do you trust more when hard cash flows call the shots?
Look into how the SWS DCF model arrives at its fair value.
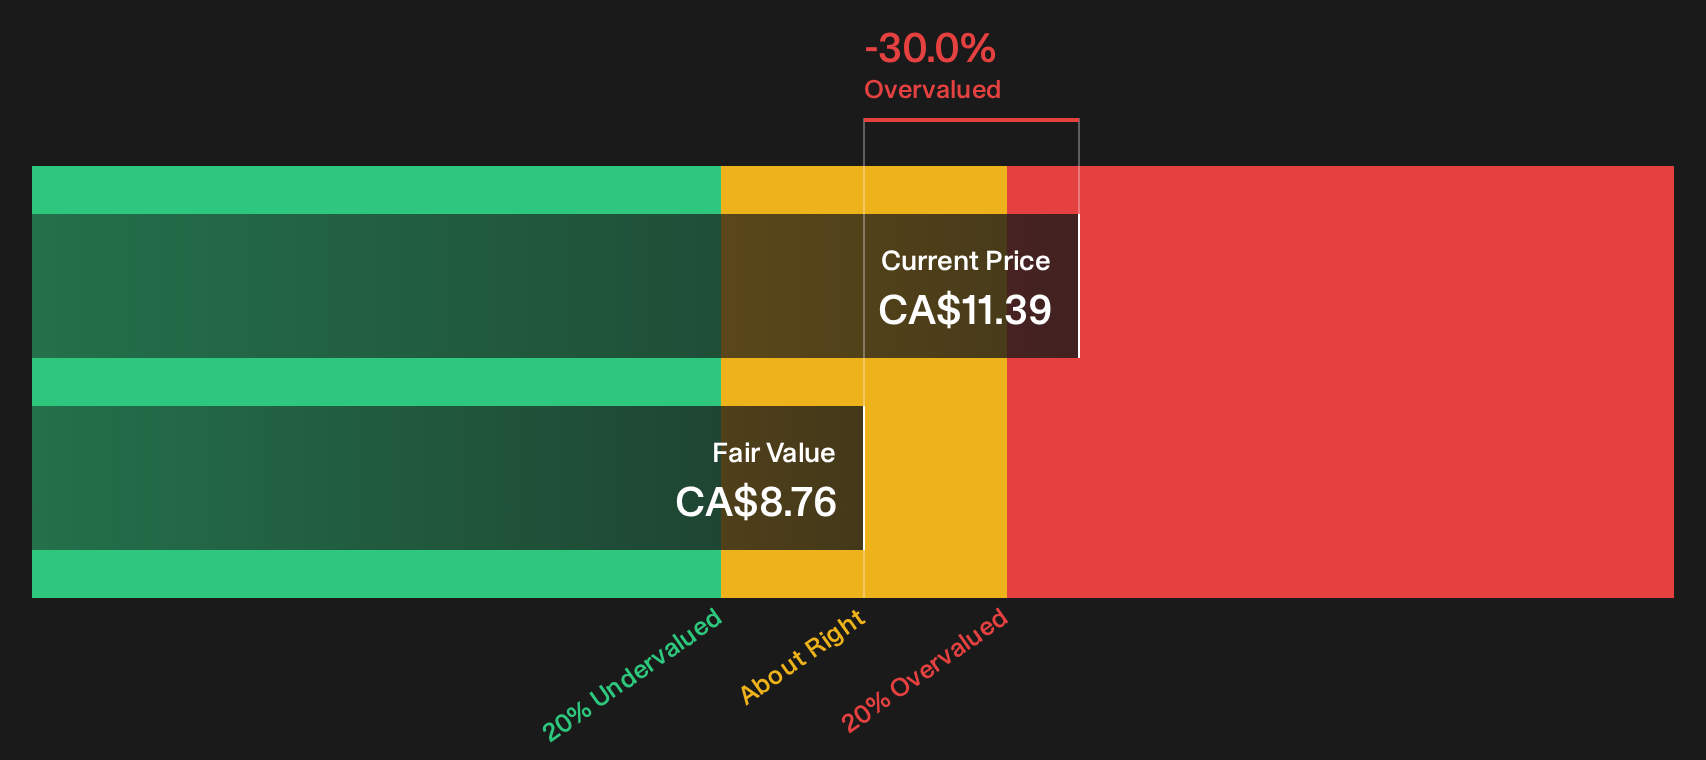
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Capstone Copper for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The sentiment so far has been mixed, with Capstone Copper showing both pressure and pockets of optimism. Consider moving quickly and reviewing the numbers yourself before the story develops further. To see what those optimistic signals are pointing to, check out the 3 key rewards.
Looking for more investment ideas beyond Capstone Copper?
Do not stop your research with Capstone Copper. Broader opportunity often sits in places you are not actively watching, and missing that can be costly over time.
- Target potential mispricing by scanning the 5 high quality undervalued stocks that surface companies with quality fundamentals trading below their estimated worth.
- Strengthen your income focus by reviewing the 3 dividend fortresses built around businesses offering higher yields with an emphasis on resilience.
- Protect the downside first by filtering for the 9 resilient stocks with low risk scores that highlight enterprises with sturdier balance sheets and fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com