


EN
Missed Casio ComputerLtd's 84% Rally? Here Is What Holders Saw
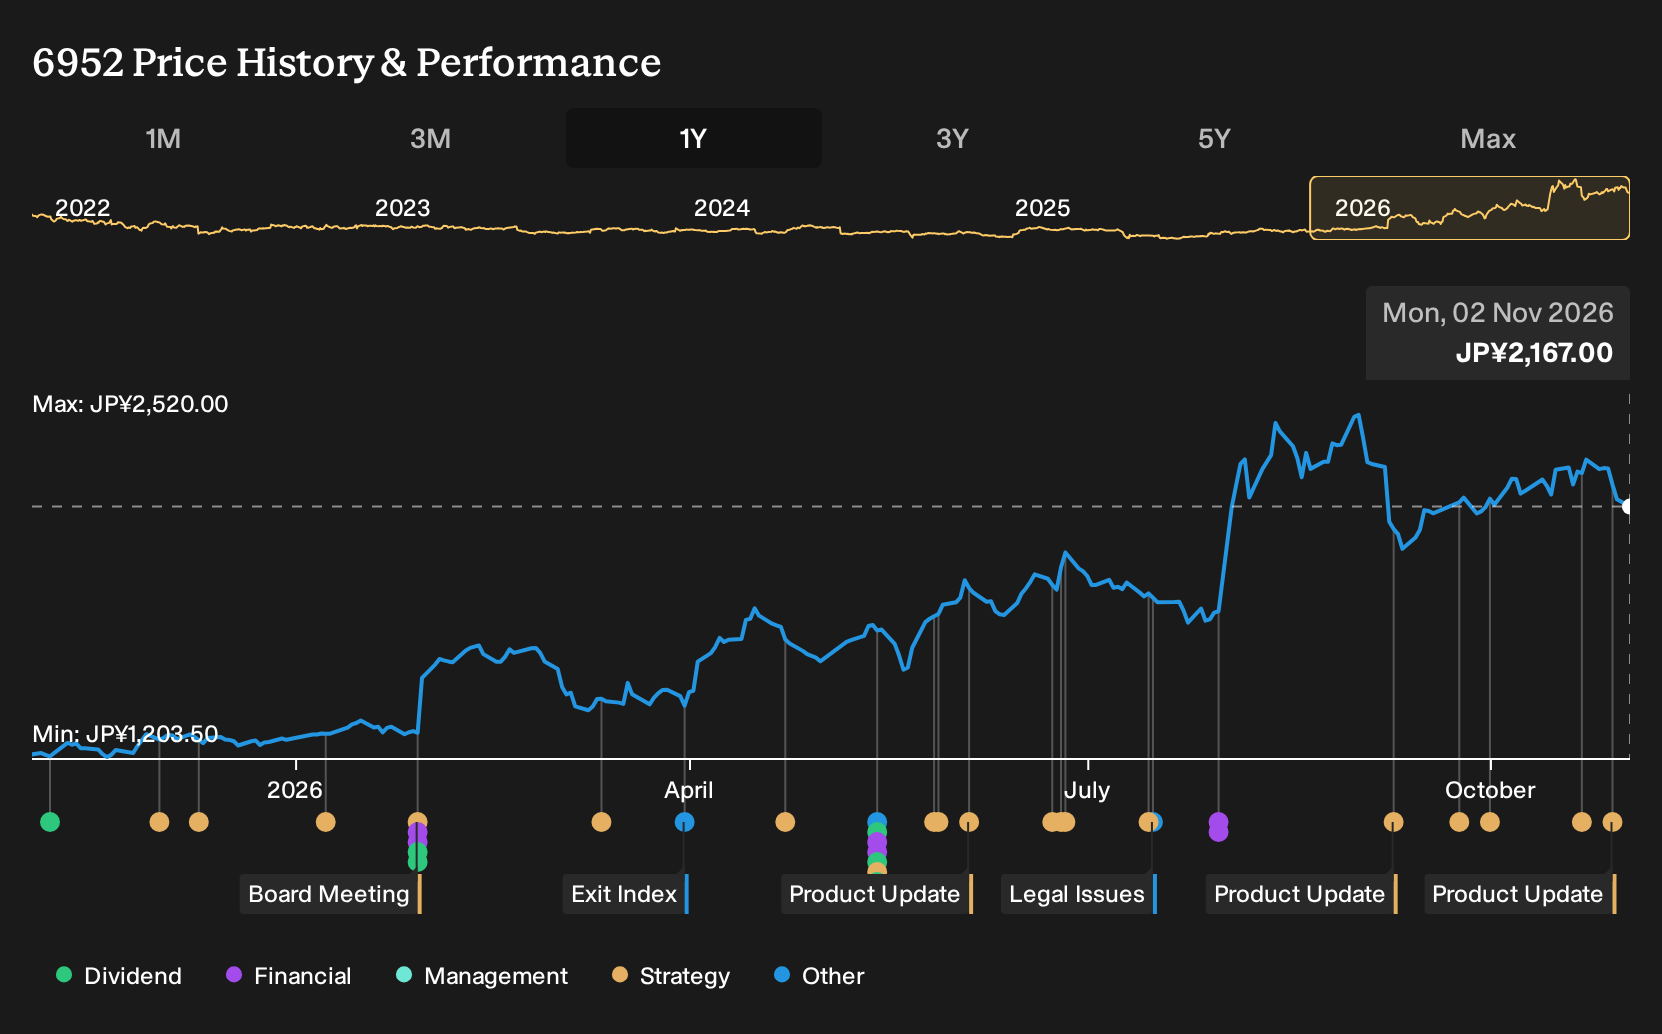
If you scroll recent headlines on Casio ComputerLtd, one product launch keeps popping up: the new G-SHOCK 2500 series that reworks the original 1983 digital watch into a modern analog line with bio-based resin parts and power saving features. Investors who held Casio ComputerLtd over the past year are up 83.9%, including dividends. If you were deciding on 2 November 2025, what had to be believed about future G-SHOCK demand and brand reach to make that outcome feel reasonable?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Casio ComputerLtd has already moved. See which of 15 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Were Weighing On Casio ComputerLtd
The shares cost ¥1,206 at the start of the period. Anyone looking at Casio ComputerLtd then had to decide which story felt more plausible, not which one was certain.
The bullish case put Fair Value at ¥1,700. That view leaned on analysts assuming revenue growth of 5.4% a year, rising net margins from 2.2% to 8.0%, and a future P/E of 18.5x supported by stronger e-commerce and higher-margin wearables.
The bearish narrative anchored Fair Value at ¥1,070. That camp focused on shrinking demand for digital watches and calculators and assumed slower 1.2% annual revenue growth, with earnings reaching ¥19.6b on a P/E of 15.5x.
What The Results Changed For The Casio ComputerLtd Story
Casio ComputerLtd kept pushing the G-SHOCK franchise with launches such as the analog 2500 series and new GRAVITYMASTER and G-LIDE models. These moves lined up with the optimistic case that focused on fresher wearables and premium timepieces. Reported numbers gave investors harder evidence. Revenue moved from ¥62,191m in Q1 2026 to ¥74,511m in Q1 2027, and net income rose from ¥3,721m to ¥9,377m, lifting net margin from 6.0% to 12.6%. The period supported the optimistic case, although only over a single quarter.
The key lesson is simple. When a bullish story leans on higher profitability from product refreshes, it is important to track whether net margin actually moves toward those targets and whether new launches show up in segment revenue rather than only in marketing headlines.
What Casio ComputerLtd's Price Already Assumes
Casio ComputerLtd now trades at ¥2,167 after an 83.9% gain over the past year, while the selected Narrative’s Fair Value sits below that level. The Narrative frames this gap around execution risk rather than a claim that the business is broken.
The selected view argues that for today’s price to hold up, Casio ComputerLtd needs to keep turning its Timepieces expansion, EdTech push, Sound restructuring and new projects into profit that consistently covers softer areas and external cost shocks.
"The main thing that has to go right is that Casio ComputerLtd converts its dual-brand Timepieces strategy, EdTech ecosystem, geographic expansion and Sound business restructuring into durable profit growth that offsets weakness in areas like China and loss-making segments."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
How Could You Get There Earlier?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 17% below our estimate - uses a larger salesforce to win more maintenance contracts and raise productivity in modernization projects.
- Company 2 - 46% below our estimate - shifts incentives to ARR while pouring spending into AI-led security platforms and managed protection services.
- Company 3 - 39% below our estimate - pushes AI HR tools and marketing matching products to deepen monetization of hiring and local services.
Three companies from the same screener. Open every one of the 22 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com