


EN
How Investors Are Reacting To Southern Copper Stock Q3 Output And Dividend
- Southern Copper reported Q3 2026 operating results that showed slightly lower mined volumes for copper, molybdenum and zinc versus a year earlier, alongside higher silver output over the first nine months, and the board approved a quarterly dividend of US$1.30 per share payable on November 19, 2026.
- The combination of softer base metal volumes with a sizeable cash dividend signals how Southern Copper is balancing current production trends with direct cash returns. This gives investors more information about capital allocation priorities while large Peru and Mexico projects remain under development.
- This review will examine how Southern Copper's investment narrative aligns with these Q3 production outcomes and the newly authorized dividend.
Compare Southern Copper's mix of production trends and a US$1.30 dividend with hand-picked peers by screening for 16 top copper producer stocks that may offer a similar balance of volume and income focus.
Southern Copper Investment Narrative Recap
To own Southern Copper, you need to be comfortable with a miner that is leaning hard into a long build out of Peru and Mexico projects while managing near term volume softness. Q3 2026 production for copper, molybdenum and zinc sat slightly below the prior year quarter, and nine month figures were also lower, so the heartbeat right now is execution rather than expansion headlines.
The key short term catalyst is progress and cost control on that US$20.5b capex pipeline, because those projects underpin management’s longer term output targets. The biggest risk is that lower mined grades or community and regulatory issues in Peru and Mexico slow ramp ups. The latest production data slightly cools momentum but does not radically change that near term equation.
The fresh US$1.30 quarterly dividend sits at the center of this update, because it directly touches the main operational tension around Southern Copper. The miner is committing substantial cash to growth projects while also returning a sizable amount to shareholders at a time when production is not trending higher year on year.
For you, that dividend decision is relevant in two ways. It speaks to confidence in current cash generation despite softer volumes, and it interacts with the flagged risk of an unstable dividend track record. If project timelines slip or copper prices soften, management will have less room to fund both heavy investment and a large payout without trade offs.
What Analysts Are Baking Into Southern Copper’s Numbers
Southern Copper's long term growth story is already laid out in analyst models. They are building in 5.3% yearly revenue growth over the next few years, starting from current earnings of US$5.7b and aiming for consensus earnings of US$6.8b by 2029. This represents an increase of about US$1.1b and assumes those profits arrive in the year 2029.
On those projections, analysts see profit margins edging higher from 35.9% today to 36.8% over roughly three years, with earnings per share estimated at US$7.33 by late decade. That move in profitability sits alongside a P/E multiple that would need to ease from 30.9x today to 28.1x on the 2029 earnings, still above the 19.7x level quoted for the broader US metals and mining group.
The forecast fair value work then ties those profit targets back to revenue, with the consensus expecting Southern Copper to reach about US$18.4b in sales and US$6.8b in earnings during 2029. Analysts use discount rates in the 8.85% to 8.9% range to bring those future figures into today’s dollars, which highlights how sensitive any valuation is to both the project delivery timeline and the margin path.
Disagreement across forecasts is wide, which matters if you are trying to judge how much conviction to place on a single scenario. On earnings, the most optimistic estimates sit at US$7.9b while the most cautious are around US$4.7b. This implies very different outcomes for cash generation, dividend capacity and flexibility to keep funding that US$20.5b capex slate without stretching the balance sheet.
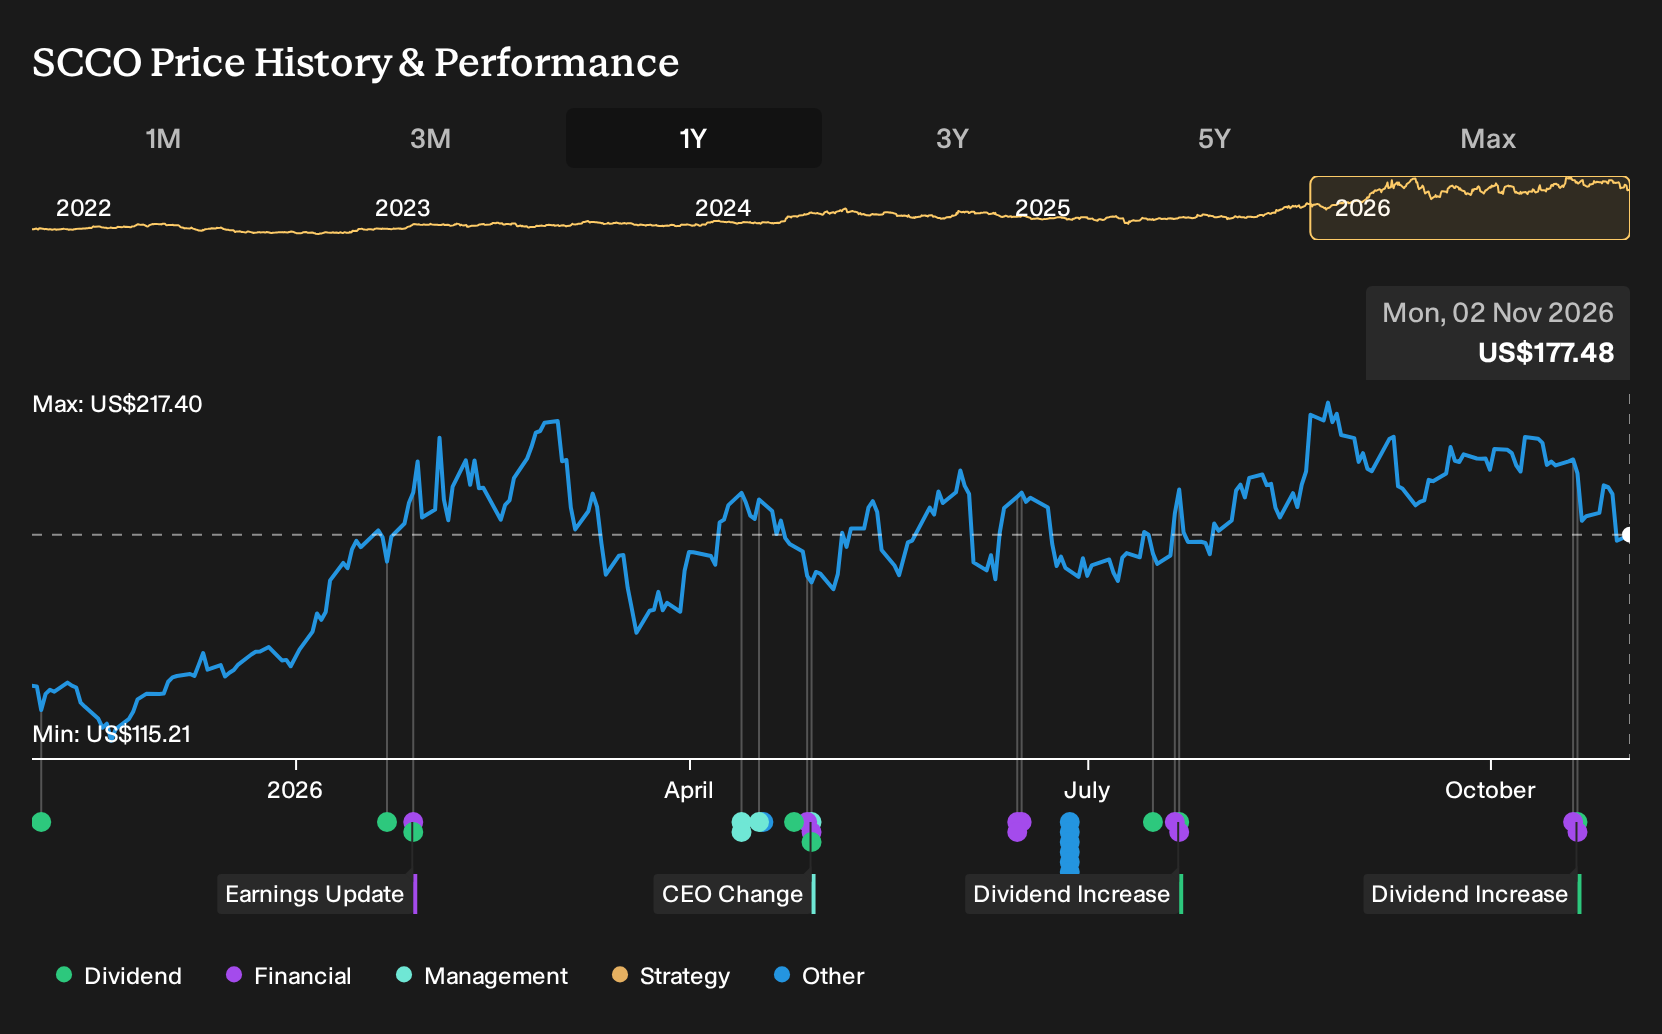
The same split shows up in price targets. The average target of US$175.30 is below the current share price of US$207.42, with the bullish end at US$275.00 and the low point at US$138.34. Analyst views therefore tend to cluster around the idea that Southern Copper’s quality and growth options are well known and already heavily reflected in the quote.
Uncover why Southern Copper's fair value indicates a valuation gap that aligns with its current price.
Exploring Other Perspectives
You can frame Southern Copper very differently if you focus on the bearish worry that copper volumes in Peru stay constrained. The lowest analysts were already penciling in revenue of about US$14.4b and earnings of US$4.6b by 2029 before this Q3 production and dividend news, so their more cautious story may shift again as fresh data lands.
Explore 4 other Southern Copper fair value estimates, including one that suggests as much as 23% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Southern Copper research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Southern Copper. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Southern Copper's overall financial health at a glance.
Looking for more investment ideas beyond Southern Copper?
If Southern Copper has sharpened your thinking on commodities, income and capital expenditure, broaden that lens by using the Simply Wall St Screener to line up other stocks with traits that match your own risk and return preferences.
- For investors who want potential upside without ignoring quality, start with a focused group of companies that screen as 19 high quality undiscovered gems and might not yet be widely followed.
- If capital preservation and steadier profiles matter more to you than excitement, narrow your search to businesses highlighted as 29 resilient stocks with low risk scores and see which ones fit your comfort zone.
- Income focused readers who care about both yield and resilience can zero in on established payers by filtering for 4 dividend fortresses that combine higher payouts with durable fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com