


EN
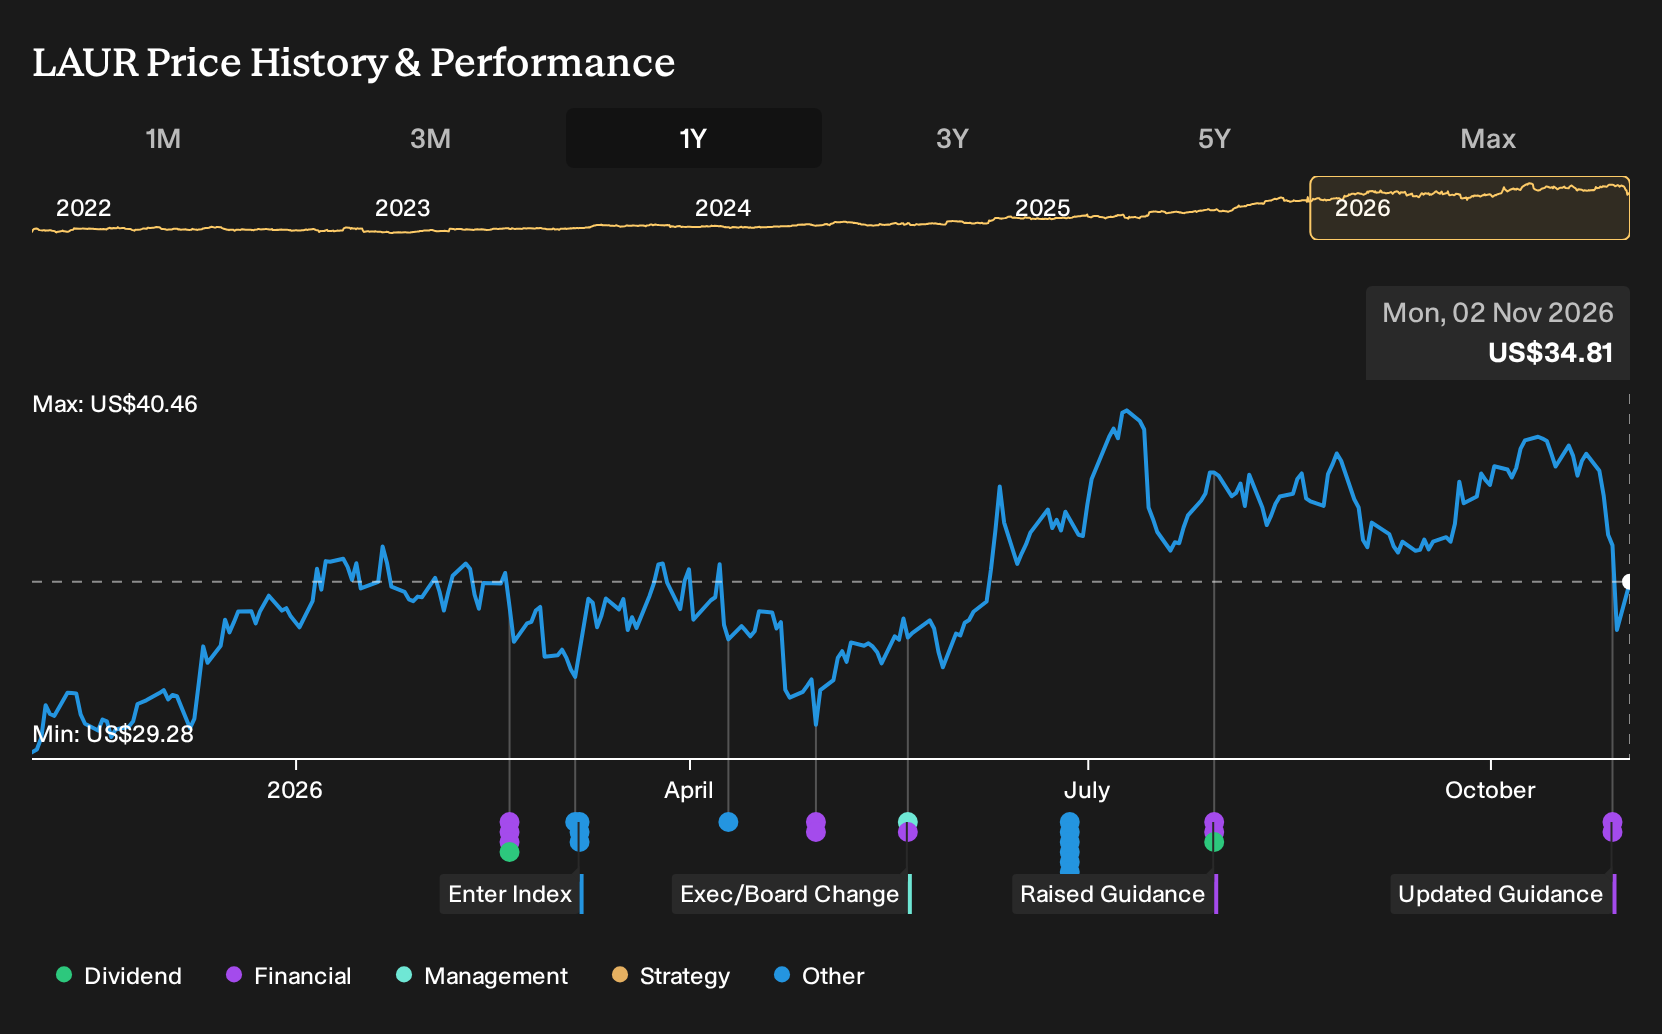
How Investors May Respond To Laureate Education (LAUR) Earnings Beat
- Laureate Education reported third quarter 2026 sales of US$485.09 million and net income of US$101.22 million, and also reaffirmed full year 2026 revenue guidance of US$1.92b to US$1.93b alongside fourth quarter revenue expectations of US$546 million to US$556 million.
- The combination of higher earnings per share from continuing operations and confirmed revenue targets shows how Laureate Education is currently converting demand for both new campuses and online programs into profit and cash generation potential.
- Next, the focus shifts to how Laureate Education's reaffirmed 2026 revenue guidance could influence the existing investment narrative around online expansion.
Compare Laureate Education's reaffirmed guidance and margin story with a curated 34 high quality undervalued stocks that also pair disciplined execution with stronger cash generation potential.
Laureate Education Investment Narrative Recap
To own Laureate Education, you need to believe the company can keep scaling online programs in Mexico and Peru while filling out new campuses enough to support current margins. The reaffirmed 2026 revenue guidance around US$1.92b to US$1.93b, plus higher recent earnings, supports that story but does not radically change it.
The key near term catalyst remains efficient enrollment growth across both digital and on site formats. This ties directly into cash generation and any future capital return. The biggest risk is that new locations underperform on student intake while costs stay elevated. That could pressure free cash flow and limit further margin progress.
The third quarter 2026 update is the announcement that matters most here. Laureate Education reported US$485.09 million in sales and US$101.22 million in net income for the quarter, with basic earnings per share from continuing operations at US$0.74. Those figures, alongside higher year to date profit, frame how the model is working today.
Management also reaffirmed full year revenue guidance and set fourth quarter expectations between US$546 million and US$556 million. For you as a shareholder, the operational question is whether this level of delivery can be sustained while online programs, campus expansion and AI driven marketing continue to scale without reigniting the earlier concern about revenue outpacing earnings quality.
Laureate Education's current analyst narrative points to revenues of US$2.3b and earnings of US$374.6 million by 2029, based on an assumed 7.8% yearly revenue growth rate and an earnings increase of about US$52.8 million from US$321.8 million today.
Discover how Laureate Education's fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Laureate Education’s AI driven marketing and student support. They were already penciling in around US$2.5b of revenue and US$427.9 million of earnings by 2029 before this guidance and Q3 beat. You can treat this as a higher octane narrative that may shift once updated.
Explore 3 other Laureate Education fair value estimates, including one that suggests as much as 106% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Laureate Education research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Laureate Education. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Laureate Education's overall financial health at a glance.
Looking for more investment ideas beyond Laureate Education?
If the Laureate Education story has sharpened your thinking, use that same lens across the market by building a shortlist of other businesses that fit your risk, income and quality preferences.
- For investors who want potential upside with tighter downside controls, scan a curated set of 29 resilient stocks with low risk scores that pair resilient balance sheets with measured volatility.
- If reliable balance sheets matter most to you, start with a focused list of solid balance sheet and fundamentals (24 results) and compare leverage, liquidity and fundamental strength side by side.
- Income focused readers can zero in on companies that combine meaningful yields with staying power by reviewing a hand picked 4 dividend fortresses built around 5%+ payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com