


EN
Does IND Filing Change The Bull Case For Eton Pharmaceuticals (ETON)?
- Eton Pharmaceuticals recently announced the ET-900 program, licensing mecasermin rights from Baylor College of Medicine and submitting an IND to the FDA for a planned Phase 2 trial in infantile and epileptic spasms, with first patient dosing targeted for Q1 2027.
- This move pushes Eton Pharmaceuticals further into pediatric neurology, adding a new rare disease indication that could diversify its concentrated endocrine focused portfolio and reshape how investors think about its development pipeline risk.
- We now explore how Eton Pharmaceuticals' investment narrative may shift in light of ET-900's IND filing and planned trial.
Scan how Eton Pharmaceuticals fits into a wider set of rare disease and specialty players by reviewing our handpicked 19 high quality undiscovered gems with similar under the radar potential.
Eton Pharmaceuticals Investment Narrative Recap
To own Eton Pharmaceuticals, you need to be comfortable with a focused rare disease portfolio that leans heavily on a handful of pediatric endocrine therapies. The big near term swing factor sits in how consistently those existing brands perform, while the upcoming Q3 2026 report on 5 November should clarify how current demand and pricing are tracking.
The largest operational risk remains concentration in ultra rare products where guideline changes or competition could hit revenue abruptly. The ET 900 program is too early to alter that short term picture in a material way. Your attention likely stays on commercial execution, payor dynamics, and any shift in R&D spending.
Against that backdrop, the fresh ET 900 mecasermin program gives Eton Pharmaceuticals a potential future catalyst that is separate from its endocrine base. Management has filed an IND and is planning a Phase 2 trial in infantile and epileptic spasms, with first dosing targeted for Q1 2027, so timelines and trial start up now become part of the watch list.
This does not replace nearer catalysts like the 5 November earnings release, Amglidia's planned NDA submission, or Libervant's regulatory path. It does slightly reframe execution risk, because Eton is pushing deeper into pediatric neurology where trial complexity, costs, and regulatory scrutiny can be high. For you as a shareholder, that widens the range of outcomes you need to monitor across both approved products and pipeline.
What The ET-900 Program Sits On Top Of
Eton Pharmaceuticals' story now rests on two layers. There is the current set of ultra rare treatments that drive reported numbers, and there is the analyst blueprint that tries to map where all of this could land by the late 2020s. The new ET 900 neurology effort drops onto that second layer, so it is worth knowing what expectations analysts already have baked in before you mentally assign any extra value to the new program.
Consensus modeling has put some fairly specific stakes in the ground. Analysts are assuming revenue can expand by 50.4% a year over the next three years, with profit margins moving from 12.0% today to 37.0% over the same period. On the earnings line, the group expects Eton Pharmaceuticals to reach US$133.0 million by 2029, up from US$12.7 million today, which implies roughly a 10x step up in profit over that window.
Those forecasts then tie into valuation markers that many investors end up watching by default. The analyst framework points to 2029 revenue of US$359.4 million and earnings of US$133.0 million, with the stock trading on a P/E of 22.8x in that year compared with 128.6x today. That assumed future P/E also sits above the 16.4x multiple cited for the wider US Pharmaceuticals sector, so the expectations build in a premium to the peer group.
In addition to the growth assumptions, the models layer in capital structure and risk inputs that matter for dilution and discounting. Forecasts currently use share count expansion of 6.58% a year for the next three years and a discount rate just above 7%, based on the Simply Wall St report. When that is all pushed through to a single reference point, analysts arrive at a consensus price target of US$71.0 compared with a share price of US$57.09, with the caveat that each investor should sanity check those numbers against their own view of the Eton Pharmaceuticals pipeline, including ET 900.
Eton Pharmaceuticals' narrative projects US$359.4 million revenue and US$133.0 million earnings by 2029. That assumes 50.4% yearly revenue growth and roughly a 10x earnings increase from US$12.7 million today.
Uncover why Eton Pharmaceuticals' fair value indicates a 40% potential upside to its current price, a gap that may not persist.
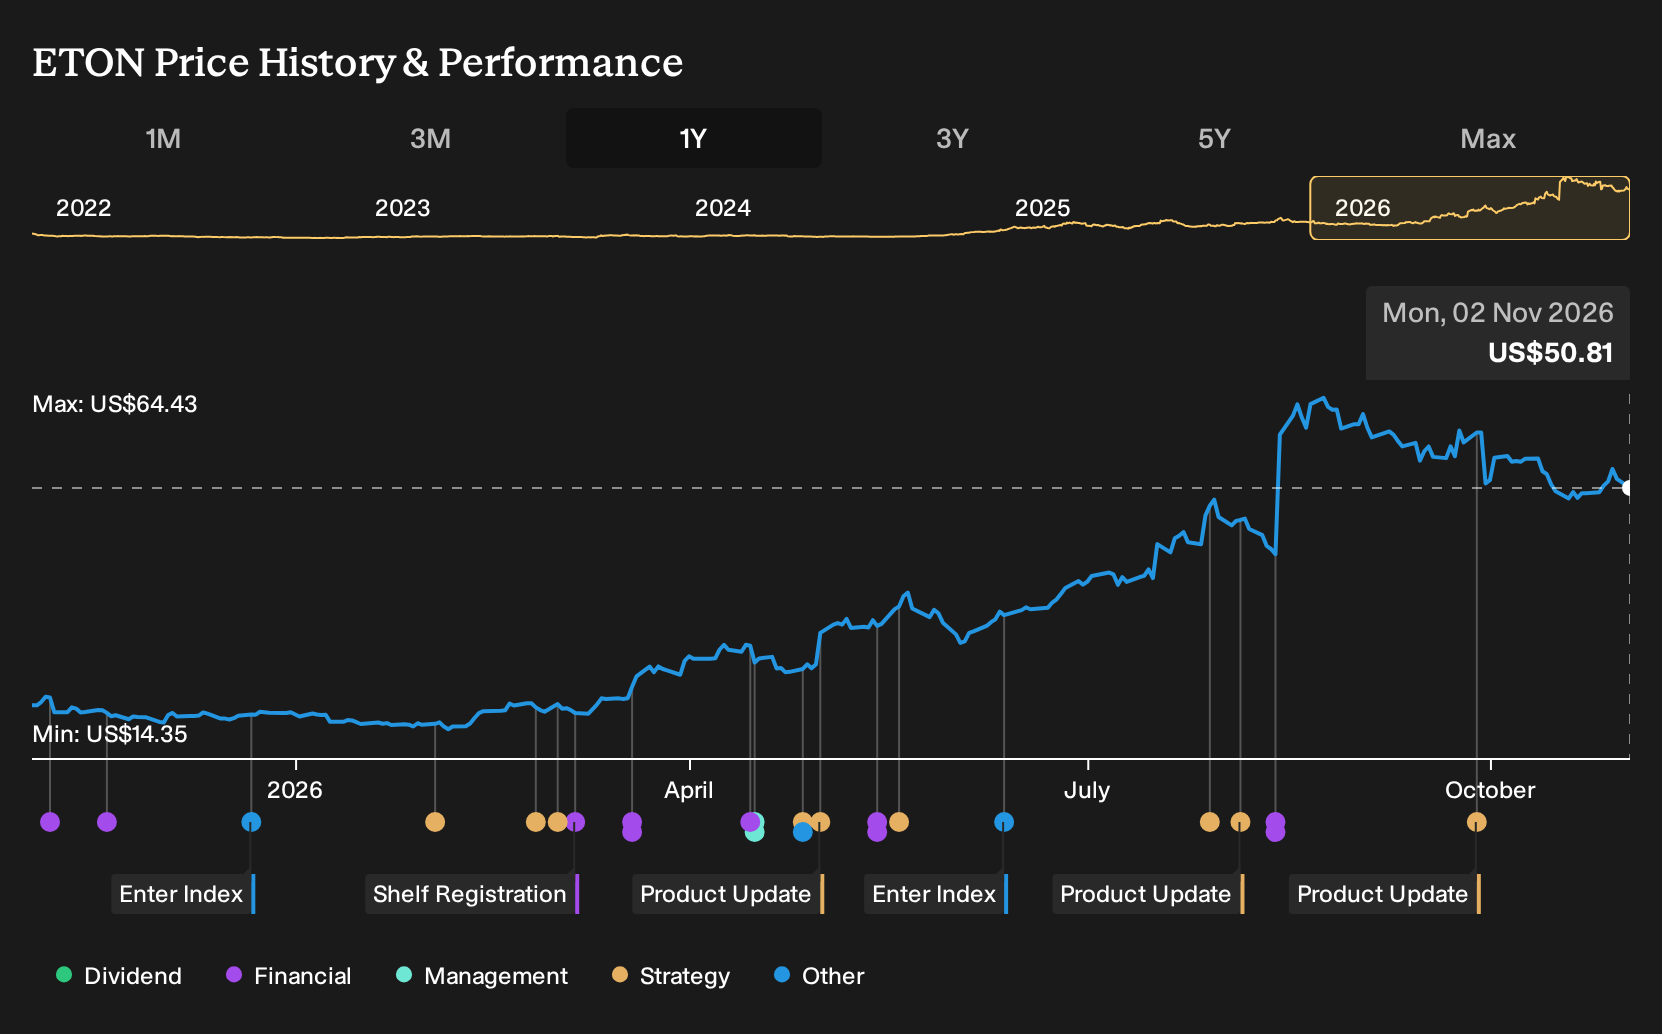
Exploring Other Perspectives
One alternate view highlights R&D risk rather than product concentration. The most bearish analysts already assumed heavier spending would keep 2029 earnings nearer US$117.6 million on about US$350.8 million of revenue. Those forecasts, set before ET 900 and the upcoming Q3 2026 earnings, could shift meaningfully, so explore both narratives before deciding where you stand.
Explore 3 other Eton Pharmaceuticals fair value estimates, including one that suggests it could be worth just $71.00!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Eton Pharmaceuticals research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Eton Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eton Pharmaceuticals' overall financial health at a glance.
Looking for more investment ideas beyond Eton Pharmaceuticals?
If the Eton Pharmaceuticals story has sharpened your thinking about risk, reward, and concentration, you can broaden that lens with a few focused screens that surface other opportunities matching your preferred profile.
- For investors who want income as well as potential capital gains, scan a curated set of high yield payers through the 4 dividend fortresses.
- If capital protection ranks high on your list, filter for companies that pair lower risk scores with resilient fundamentals using our 29 resilient stocks with low risk scores.
- When you are hunting for under the radar businesses with solid quality markers, let the 19 high quality undiscovered gems surface ideas that might not yet be on most investors’ radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com