


EN
Earnings Miss Might Change The Case For Investing In Las Vegas Sands Stock (LVS)
- Las Vegas Sands reported third quarter 2026 revenue of US$3.216b and net income of US$304m, with earnings per share from continuing operations of US$0.48, and affirmed a US$0.30 quarterly dividend payable on 10 November 2026.
- The nine month figures show revenue of US$9.955b and net income of US$1.217b.
- Next, the focus turns to how Las Vegas Sands' softer quarterly earnings alongside a maintained dividend factor into the broader investment narrative.
Compare Las Vegas Sands' earnings and dividend profile with curated income ideas by scanning 4 dividend fortresses, which may offer a similar balance of cash flow and payout focus.
Las Vegas Sands Investment Narrative Recap
To back Las Vegas Sands, you need to believe its Macau and Singapore resorts can keep drawing higher value guests even as competition and promotional spending stay intense. The latest quarter showed revenue and profit lower than the same period last year, so the near term focus stays on how efficiently existing properties convert visitor traffic into earnings.
The main short term swing factor is Macau demand and margins, especially after prior earnings misses and a recent drop in market wide Macau gaming revenue. The biggest operational risk remains execution on large projects like the Marina Bay Sands IR2 build, where any cost pressure or delay would matter more than this single quarter.
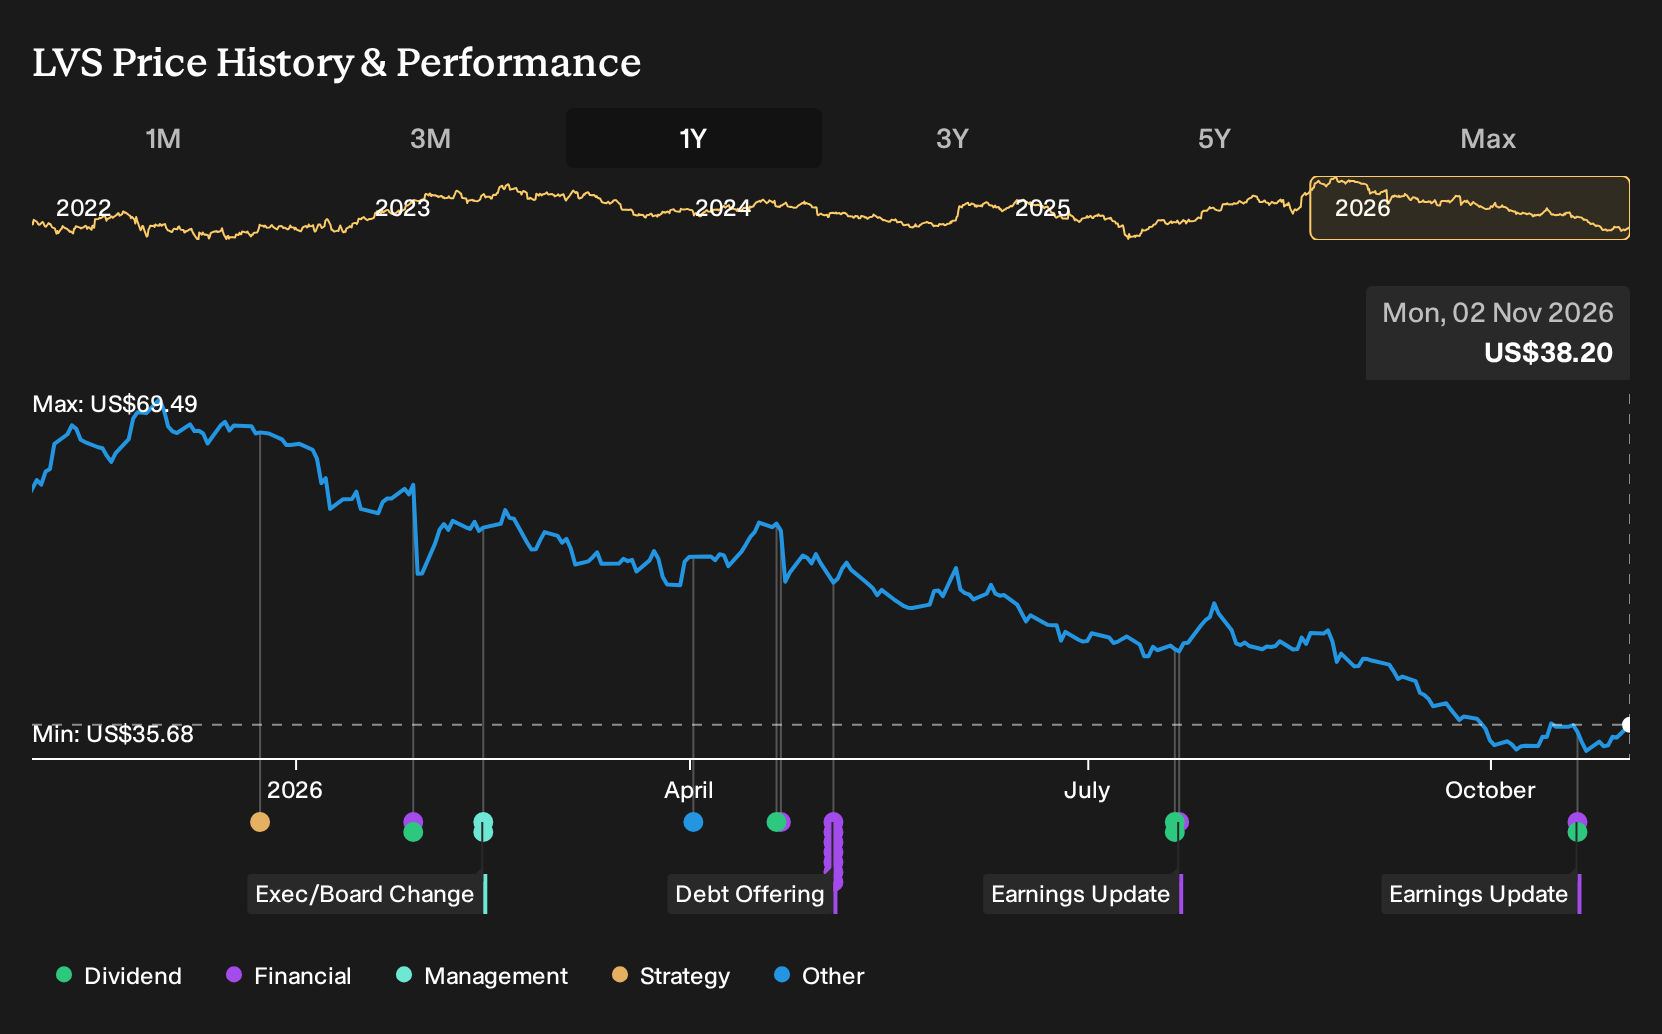
The most relevant update right now is the October 21 earnings release. Third quarter revenue of US$3.216b and net income of US$304m came in lower than a year earlier, and earnings per share from continuing operations fell to US$0.48 from US$0.61. Nine month revenue reached US$9.955b with net income of US$1.217b, broadly flat versus the prior period.
This mix of softer quarterly profit but ongoing profitability keeps attention firmly on how Las Vegas Sands funds heavy capex and services its higher debt load while still paying cash to shareholders. With Macau renovations and the Marina Bay Sands expansion ahead, execution on cost control, guest mix and occupancy looks more important to the thesis than the single quarter miss itself.
Las Vegas Sands' narrative projects US$15.4b revenue and US$2.2b earnings by 2029. This implies 4.2% yearly revenue growth and an earnings increase of about US$600m from US$1.6b today.
Uncover why Las Vegas Sands' fair value indicates a 31% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest Las Vegas Sands forecasts lean hard into cost risk rather than growth potential. Those analysts were penciling in roughly US$14.7b of 2029 revenue and holding earnings at about US$1.6b. That is a much more cautious story. You can use this earnings and dividend update as a prompt to compare those views yourself.
Explore 2 other Las Vegas Sands fair value estimates, including one that suggests it could be worth just $40.01.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Las Vegas Sands research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Las Vegas Sands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Las Vegas Sands' overall financial health at a glance.
Looking for more Las Vegas Sands investment ideas beyond this stock?
If this update on Las Vegas Sands has sharpened your view on income, risk and value, use that same lens across the wider market with the Simply Wall St Screener.
- For investors who want quality at a sensible entry point, scan a focused 34 high quality undervalued stocks that blend strong fundamentals with pricing that may still leave room for upside.
- If capital preservation sits high on your priority list, filter the market with a 29 resilient stocks with low risk scores that emphasizes resilient balance sheets and more stable risk scores.
- When you want to broaden your watchlist beyond widely followed giants, search through a 19 high quality undiscovered gems that can help surface lesser known businesses with solid financial traits.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com