


EN
Why DexCom (DXCM) Could Be 28% Below Fair Value Following Raised 2026 Guidance
DexCom (DXCM) is back in focus after Q3 results topped Wall Street expectations, management raised full year 2026 revenue guidance to a range of US$5.20b to US$5.25b, and the G7 15 Day rollout continued.
DexCom shares have reacted quickly to the Q3 beat and raised 2026 revenue outlook, with a 1 day share price return of 3% and a 7 day share price return of 7.88% following the G7 15 Day rollout news, the new US$1.0b buyback authorization, and international regulatory wins. Despite some recent softness, with the 90 day share price return down 2.51%, momentum for 2026 has been positive overall. This is reflected in a year to date share price return of 27.38% and a 1 year total shareholder return of 40.26%, even as the 5 year total shareholder return shows a decline of 46.78% that reminds investors how volatile the longer term ride has been.
Capitalize on DexCom’s momentum in diabetes technology by scanning a curated 33 healthcare AI stocks, which are also pushing the edge of digital health and data driven care.Recent gains leave DexCom looking less like a sentiment swing and more like a response to higher guidance, G7 15 Day rollout progress, and the new buyback. How far do those fundamentals stretch on valuation?
Most Popular Narrative: 27.9% Undervalued
On the numbers, DexCom’s last close at $84.76 sits well below the most followed fair value estimate of $117.59. This frames the current enthusiasm around G7 15 Day and the higher 2026 revenue outlook in valuation terms rather than as hype alone.
DexCom has continued to reap the rewards stemming from positive earnings and investors seeking appealing, undervalued stocks outside of memory chip / semiconductor companies. Year-to-date price performance stands at 23.50%. Re-evaluation of metrics refocuses fair value to $117.59 under the following adjustments:
See why 2 investors see DexCom as 28% undervalued.
Result: Fair Value of $117.59 (UNDERVALUED)
Still, the DexCom narrative could be tested if G7 15 Day adoption falls short of expectations, or if higher valuation multiples compress back toward sector levels.
Find out about the key risks to this DexCom narrative.
Another View on DexCom’s Valuation
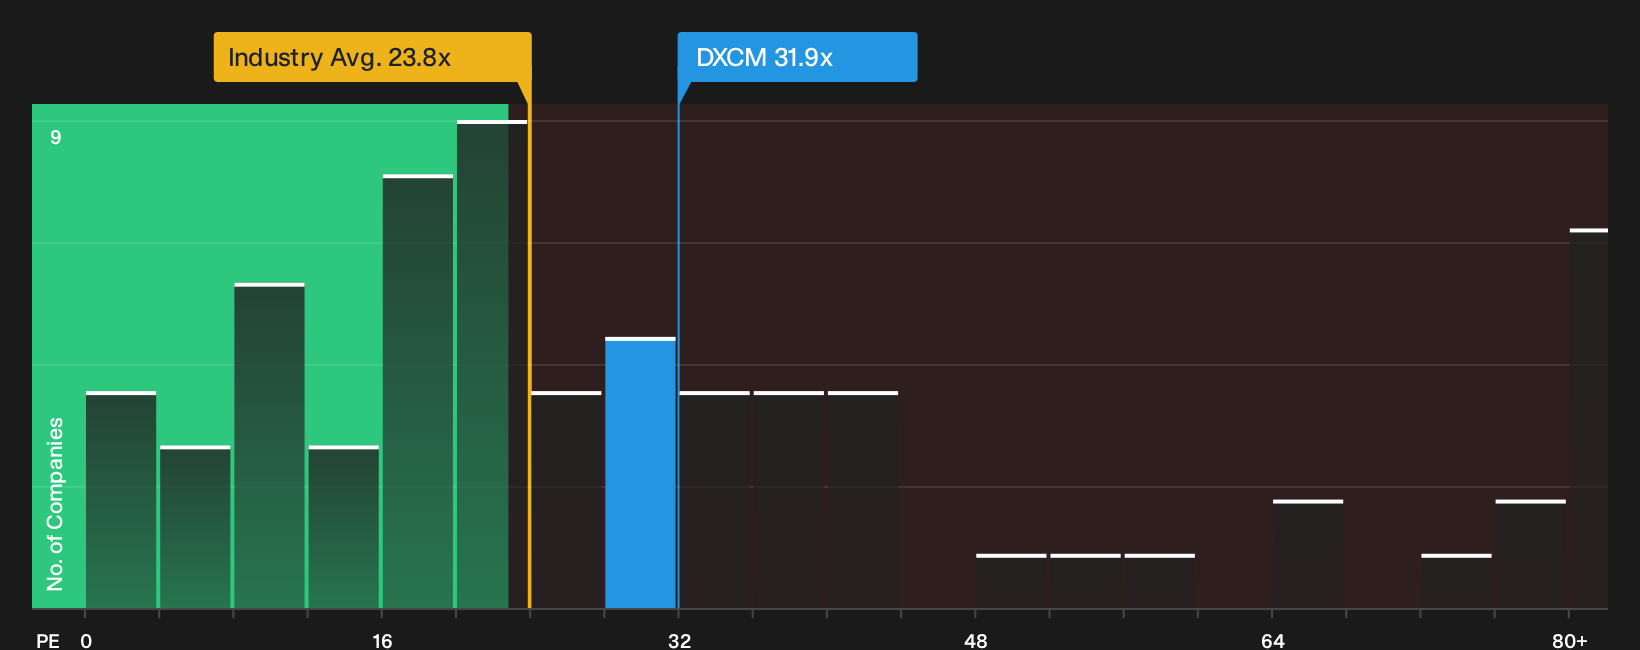
There is a different read on DexCom when looking at the P/E ratio instead of fair value estimates. The stock trades on 31.9x earnings, compared with a 28x peer average and 23.8x for the wider US Medical Equipment group. That premium points to higher expectations and some valuation risk if sentiment cools.
Against that, the fair ratio sits at 32.3x, which is very close to the current multiple. If the market gravitates toward that fair ratio rather than peer levels, investors are paying roughly in line with what the earnings profile supports, rather than a stretched growth story that must go perfectly.
Pricing power or crowding out: which way does that P/E gap lean for you, given DexCom’s recent guidance and execution track record.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment looks upbeat, yet the real test is your own work on the numbers and risks. Move quickly and shape your view using the 3 key rewards.
Looking for more investment ideas beyond DexCom?
Do not stop with DexCom. Build out a watchlist of differentiated opportunities using focused stock ideas that align with the type of portfolio you want to run.
- Target potential mispricings by scanning a curated set of companies through the 34 high quality undervalued stocks.
- Strengthen portfolio resilience by filtering for businesses with robust finances using the list of solid balance sheet and fundamentals (24 results).
- Add measured growth potential by reviewing a handpicked group of smaller opportunities via the 9 elite penny stocks with strong financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com