


EN
Quilter (LSE:QLT), What Is Behind The Fresh Attention?
Quilter (LSE:QLT) has drawn fresh attention after appointing Kristy Barr as managing director for its UK platform and investment solutions. This leadership shift places a new executive over core advice-led operations.
Recent trading has been mixed for Quilter, with a 6.69% 1 month share price return giving way to a 5.52% decline over 3 months, while total shareholder return sits at 4.95% over 1 year and very large over 3 years, suggesting that enthusiasm has cooled recently following a much stronger earlier run.
Scan how other wealth and platform players are setting up for their next phase by reviewing our hand picked list of solid balance sheet and fundamentals (10 results) alongside Quilter's latest leadership move.
Quilter now trades below the average analyst target, even as the leadership change puts fresh focus on its core platform and solutions. Is that discount caution well placed, or is it starting to look excessive?
Most Popular Narrative: 15% Undervalued
The most followed narrative currently anchors Quilter’s fair value at £2.20 per share, above the last close of £1.87. That gap frames the leadership change as a test of whether the business can deliver on the efficiency and margin story already baked into those assumptions.
The main thing that has to go right is that Quilter manages mix driven margin pressure and rising cost investment so that higher AuMA and adviser productivity still translate into the higher margin ambition over time.
The step up in guided operating costs to £530–540 million for 2026, reflecting salary inflation and higher spending on technology, brand and growth initiatives, risks embedding a structurally higher cost base if productivity and revenue benefits take longer than expected to come through.
See why 2 investors see Quilter as 15% undervalued.
Result: Fair Value of £2.20 (UNDERVALUED)
Still, the narrative frays quickly if revenue margins keep drifting lower or if the step up to £530 to £540 million of operating costs locks in a heavier expense base.
Find out about the key risks to this Quilter narrative.
Another View: Quilter Through The P/E Lens
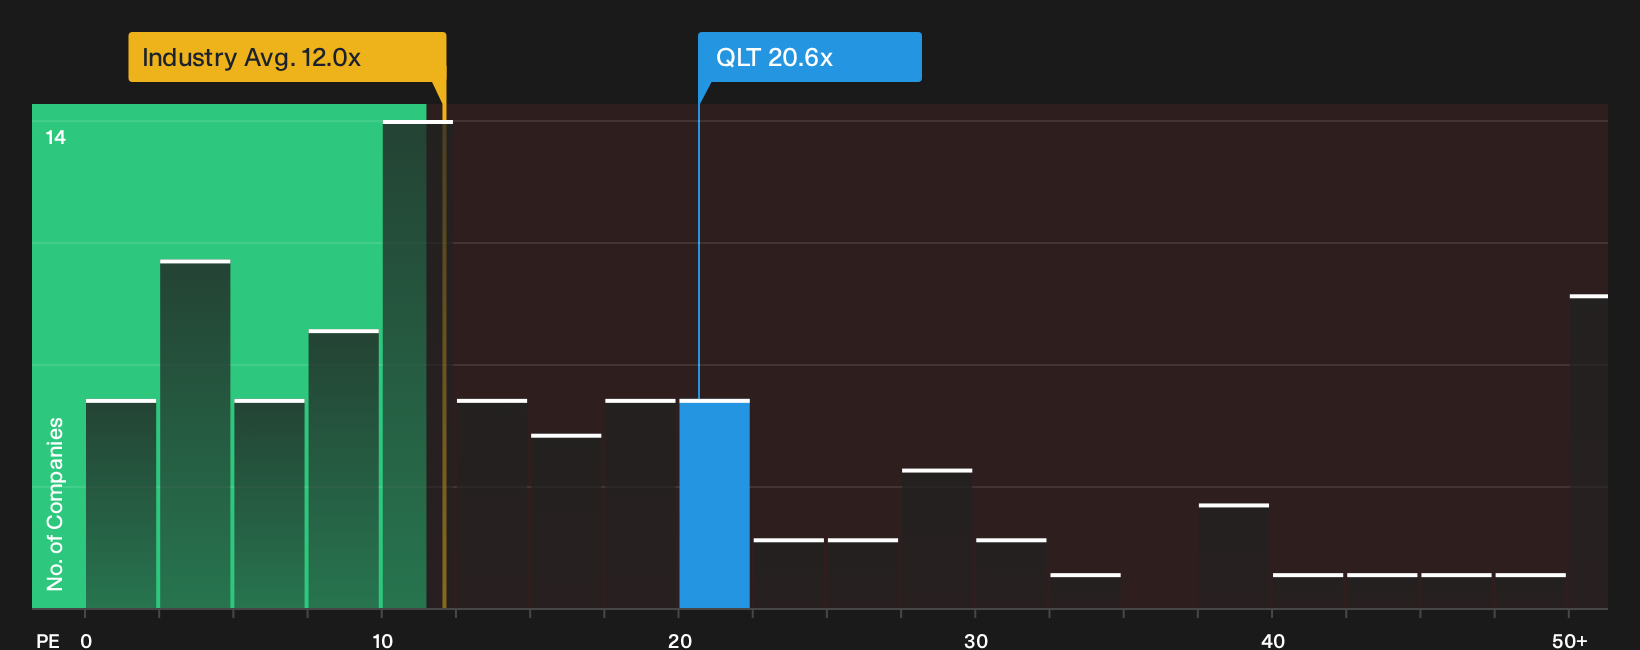
A different angle on Quilter uses its P/E ratio. The shares trade on 20.6x earnings, which is far below the 38.8x peer average but above the broader UK Capital Markets group at 12x and the fair ratio of 16.6x. That mix hints at both valuation support and overpayment risk. Which side do you think dominates?
To see how that trade off looks when you line the current multiple up against earnings quality and future assumptions, take a closer look at See what the numbers say about this price — find out in our valuation breakdown..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Quilter for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Quilter is split, with clear risks and real upside both on display. Move quickly and pressure test the thesis yourself with 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Quilter?
If Quilter has sharpened your focus, do not stop here. Broaden your watchlist and pressure test your thinking against other opportunities before the market moves first.
Use the Simply Wall St Screener to surface focused ideas that match your risk appetite and return goals, then compare them directly against what Quilter offers.
- Target potential mispricings by scanning a curated set of quality companies that screens for valuation support through the 13 high quality undervalued stocks.
- Prioritise resilience by reviewing a 5 resilient stocks with low risk scores that can help you emphasise steadier profiles when volatility feels uncomfortable.
- Hunt for future leaders early by checking a 5 high quality undiscovered gems before wider attention arrives and competition for entry points intensifies.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com