


EN
Reduced Losses Could Change The Case For Axsome Therapeutics (AXSM)
- Axsome Therapeutics reported third quarter 2026 revenue of US$259.69 million and a net loss of US$12.88 million, with basic and diluted loss per share of US$0.25, alongside nine month revenue of US$669.27 million and a net loss of US$128.73 million.
- The reduced quarterly and nine month losses indicate that Axsome Therapeutics may be gaining operating traction as its CNS portfolio scales, while the business continues to invest heavily in commercialization and R&D.
- Investors can now assess how Axsome Therapeutics' reduced quarterly net loss influences the broader investment narrative for this CNS specialist.
Axsome Therapeutics Investment Narrative Recap
To own Axsome Therapeutics, you need to believe its CNS portfolio can turn growing revenue into sustainable profitability while heavy R&D and commercial spend gradually becomes more efficient. The latest quarter points in that direction of travel, with revenue of US$259.69 million and a smaller net loss of US$12.88 million, but the business is still loss making.
The key near term catalyst remains execution on Auvelity, Sunosi and SYMBRAVO, and how quickly these products can support operating leverage. The biggest current risk is that high SG&A and payer discounts keep net margins under pressure for longer. The reported quarter reduces that concern a little, but does not remove it.
The most relevant update is the fresh third quarter and nine month 2026 earnings print. Revenue reached US$259.69 million for the quarter and US$669.27 million for the first nine months, while net losses were US$12.88 million and US$128.73 million across those periods. For an Axsome Therapeutics shareholder, that set of numbers frames the company’s ability to self fund its CNS ambitions.
Loss per share of US$0.25 in the quarter and US$2.48 across nine months keeps the focus on the balance between commercial expansion and cash burn. Execution on late stage programs like AXS 05, AXS 12 and AXS 14, plus additional solriamfetol indications, will likely be judged against this earnings baseline, since slower than expected uptake or reimbursement pressure could extend the timeline to consistent profitability.
Axsome Therapeutics' current earnings are a loss of US$188.3 million, with analysts expecting earnings to reach US$908.3 million by 2029. That shift implies an earnings increase of about US$1.1b. Forecasts also point to 51.3% yearly revenue growth over the next three years, with analyst models calling for US$2.5b of revenue and US$908.3 million of earnings in 2029.
Uncover why Axsome Therapeutics' fair value indicates a 108% potential upside to its current price that may not last much longer.
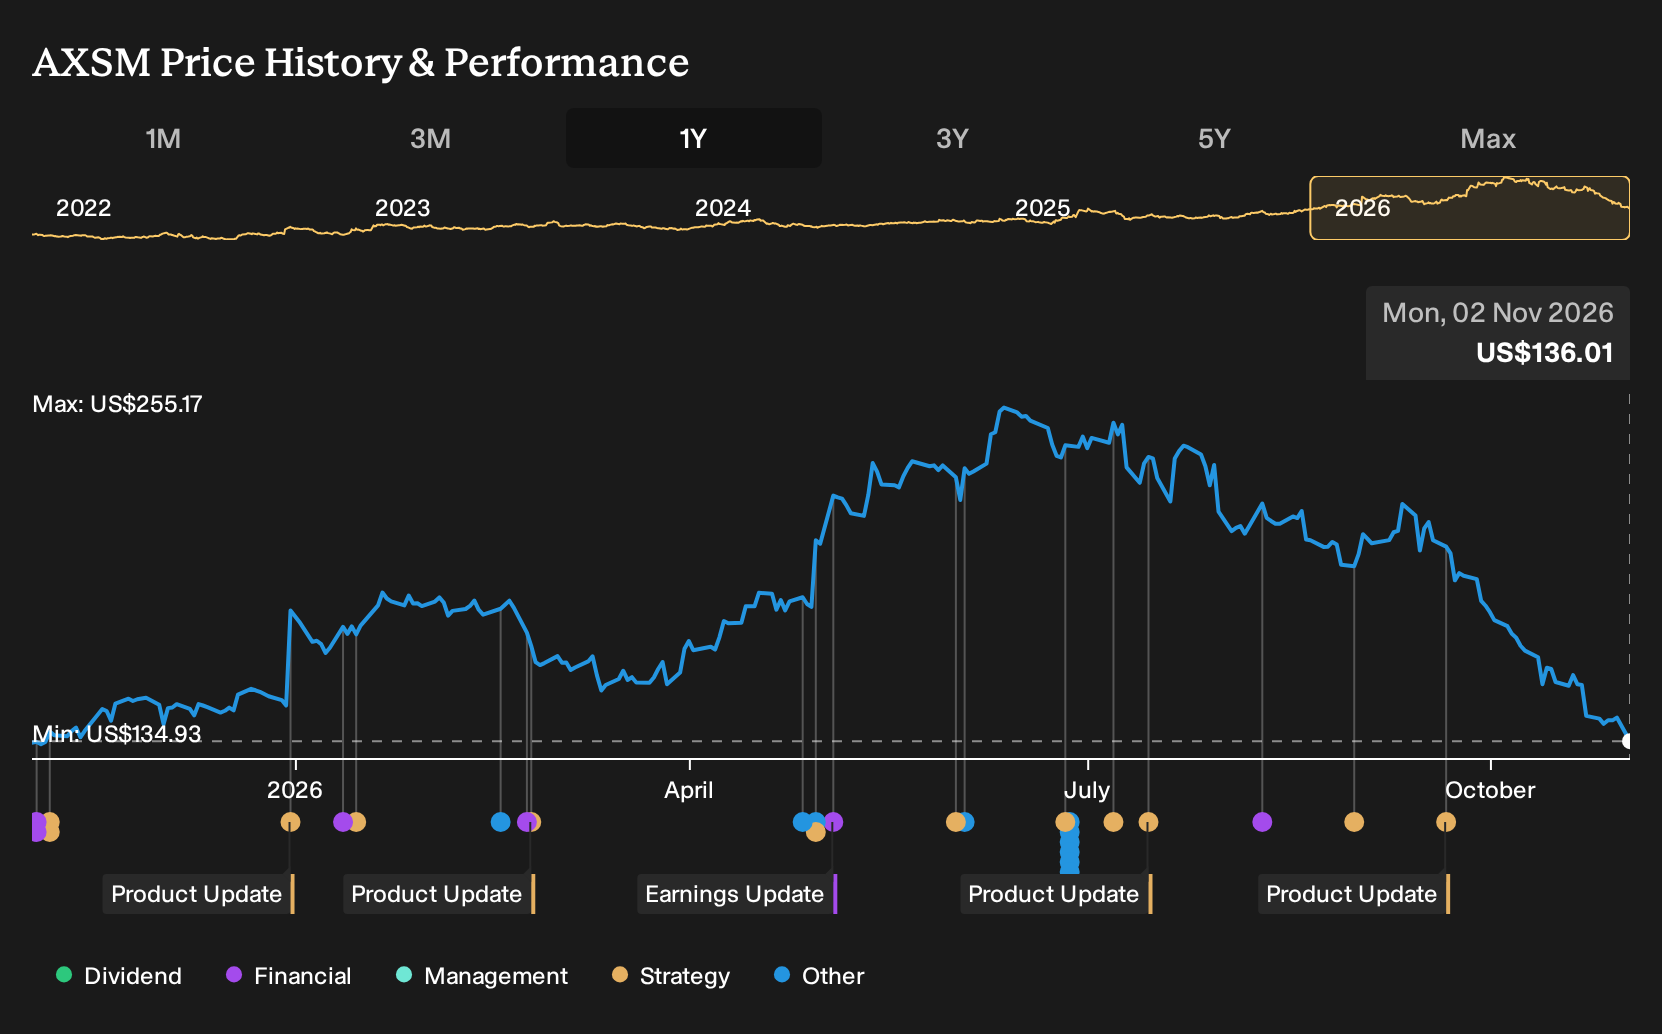
Exploring Other Perspectives
For Axsome Therapeutics, the most optimistic analysts focus on the AXS 12 catalyst. Before this earnings release, they were penciling in revenue of about US$3.4b and earnings of roughly US$2.1b by 2029. You now have fresh numbers that those projections did not include, so use this moment to compare different narratives side by side.
Explore 4 other Axsome Therapeutics fair value estimates, including one that suggests potential upside of as much as 553% from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Axsome Therapeutics research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Axsome Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Axsome Therapeutics' overall financial health at a glance.
Looking For More Ideas Beyond Axsome Therapeutics?
If Axsome Therapeutics has you thinking about position sizing, risk and reward, it can help to compare it with other opportunities that share some of the qualities you care about most. Use the Simply Wall St Screener to filter for traits that match your own approach and build a watchlist that fits your plan instead of relying on headlines.
- For investors who like mispriced situations with quality backstops, start with a focused list of 34 high quality undervalued stocks that combine stronger fundamentals with more appealing valuations.
- If capital protection sits high on your priority list, narrow the field to a curated 29 resilient stocks with low risk scores that may suit a more cautious portfolio.
- When you want resilient balance sheets to sit alongside Axsome Therapeutics, scan our list of solid balance sheet and fundamentals (24 results) and compare their fundamentals side by side.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com