


EN
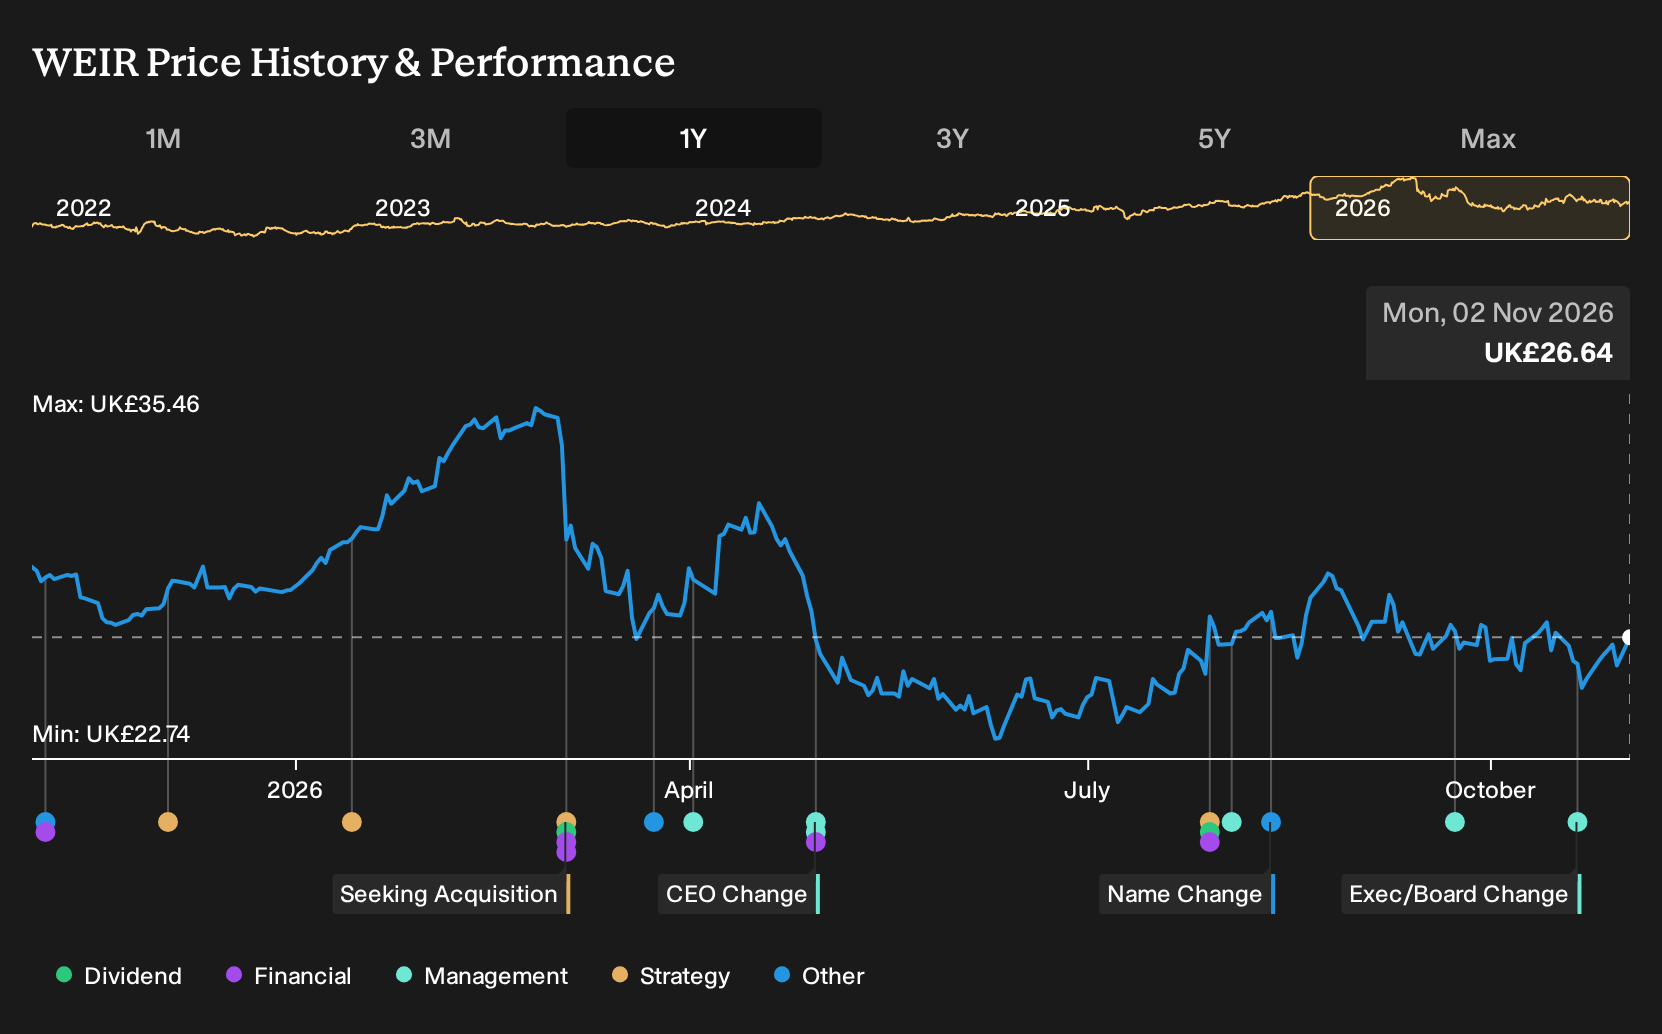
What Weir (LSE:WEIR)'s Minerals Leadership Change Means For Shareholders
- Weir PLC has appointed Marc Cameron as President of its Minerals Division, adding him to the Group Executive after more than 25 years in mining, heavy equipment and technology led roles at Caterpillar and Rio Tinto.
- Cameron’s background in data driven mining software and large scale mine operations highlights Weir’s push to blend equipment, digital tools and customer focused services in its core Minerals segment.
- We will now look at how Weir's investment narrative could shift with Marc Cameron leading the Minerals Division's global operations.
Scan other equipment and mining technology players that may benefit from the same trends driving Weir’s Minerals business by reviewing the 95 robotics and automation stocks in our screener.
Weir Investment Narrative Recap
To own Weir, you need to believe its mining focused equipment, software and aftermarket services can turn a large project pipeline and high recurring revenue into stronger cash generation. The short term swing factor is whether working capital and cash conversion improve from H1 2026 levels. Marc Cameron’s appointment does not change that near term test in a material way yet.
The key risk still sits with mining activity and commodity cycles, plus integration of recent acquisitions while net debt to EBITDA is at 2.2x. Cameron’s background in large scale operations and data driven mining tools gives Weir more operational experience to tackle those execution and integration risks, but the financial metrics will need to do the talking.
There have been no fresh regulatory filings tied directly to this hire, so the relevant reference point is Weir’s previous commentary around Micromine, Townley and CiDRA. Those deals lean heavily on mining software, process optimisation and higher margin recurring revenue. That is exactly the territory where a former Caterpillar Resource Industries executive with software exposure can influence how the Minerals division runs.
For shareholders, the catalyst to watch is whether this leadership change tightens delivery on the existing plan. That plan already includes a targeted Performance Excellence saving of £90m, an aftermarket mix of around 80% in Minerals, and Micromine annual recurring revenue that analysts expect to grow more than 25% in 2026. Execution against those numbers will matter more than the headline of a new hire.
Weir's analyst narrative points to forecast revenue of £3.2b and projected earnings of £429.9 million by 2029, built on an assumed 6.9% yearly revenue growth rate and an earnings increase of about £165.7 million from £264.2 million today.
Uncover why Weir's fair value indicates a 23% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Weir leans heavily on digital mining tools as the real swing factor. The most optimistic analysts were already modelling 8.1% yearly revenue growth and about £456.7 million of earnings by 2029, well above consensus. Your take on Marc Cameron’s software background could shift how you see those pre news forecasts, so it helps to compare several viewpoints.
Explore 3 other Weir fair value estimates, including one that suggests as much as 50% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Weir research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Weir. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Weir's overall financial health at a glance.
Looking for more investment ideas beyond Weir?
Once you are comfortable with where Weir fits in your portfolio, it can help to scan a few different angles using the Simply Wall St Screener so you are not relying on a single theme or style of stock for returns.
- If you care most about valuation support and quality together, start with companies that screen well on both fronts through the 13 high quality undervalued stocks.
- For investors who prefer a smoother ride, focus on stability first by reviewing a 5 resilient stocks with low risk scores that may offer more resilient profiles than a single cyclical industrial.
- Those hunting for new stories rather than widely followed blue chips can scan a 5 high quality undiscovered gems that combines under-the-radar names with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com