


EN
What National Bank Holdings (NBHC)'s Quarterly Loss Means For Shareholders
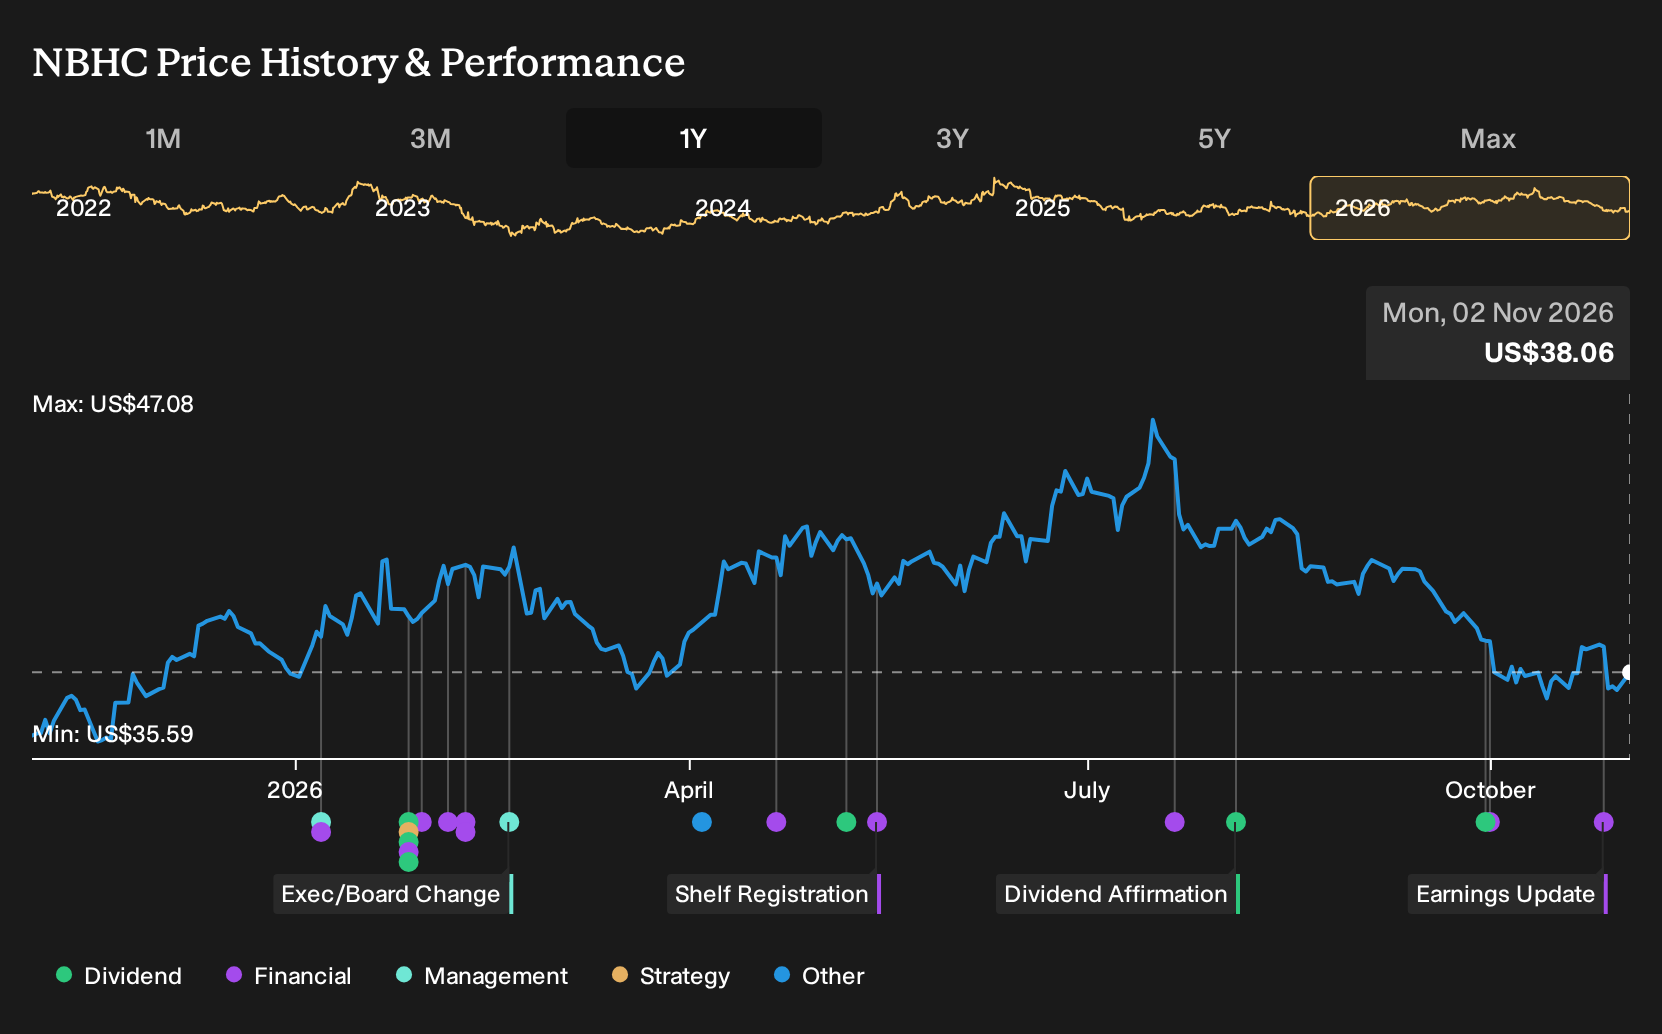
- National Bank Holdings reported third quarter 2026 results with net interest income of US$112.9 million but a net loss of US$8.76 million, and also confirmed completion of a share repurchase program totaling 949,526 shares for US$39.15 million.
- The combination of higher net interest income and a swing to a quarterly loss points to pressure elsewhere in the business, likely from costs, credit provisions, or weaker noninterest income. This matters for how durable National Bank Holdings' earnings mix really is.
- We will now look at how National Bank Holdings' sharp swing to a quarterly loss could reshape the existing investment narrative.
Compare National Bank Holdings' earnings reset with peers facing similar pressure on credit costs and fee income by scanning our hand picked 29 resilient stocks with low risk scores that currently look more resilient on risk.
National Bank Holdings Investment Narrative Recap
An investor in National Bank Holdings needs to believe that its relationship driven deposit base, 2UniFi digital push and Vista acquisition can still be turned into steadier earnings, even after a quarter with a reported loss. The jump in net interest income to US$112.9 million shows underlying client activity, but the US$8.76 million loss raises questions about cost control and potential credit or fee headwinds.
In the near term, the key swing factor is whether management can pull expenses and credit costs back in line as one time items from integration and investment roll off. The biggest risk at this point is that the drag from weaker profitability and underperforming noninterest income persists long enough to blunt the impact of any margin resilience or loan growth.
The most relevant update is the third quarter 2026 earnings release itself, because it links stronger net interest income to weaker bottom line results. For the first nine months of 2026, National Bank Holdings reported US$330.99 million of net interest income and US$38.52 million of net income, which is far lower than the prior year figure of US$93.54 million.
This pattern matters for the current catalysts. The 2UniFi small business platform and Vista related growth need to show up in cleaner, less volatile earnings, or the bank risks prolonging a period of lower profit margins and a loss making quarter hanging over the story. The decision for investors comes down to how quickly management can translate higher earning assets and digital spending into more consistent, high quality returns.
National Bank Holdings' current consensus narrative assumes revenue will grow at about 13.4% a year, targeting roughly US$659.3 million of revenue and US$235.7 million of earnings by 2029, compared with earnings of US$97.4 million today, which implies an earnings increase of about US$138.3 million over that period.
Uncover why National Bank Holdings' fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$46 and about US$60, so some members see National Bank Holdings as materially mispriced. You are weighing these views against credit concentration in trucking, agriculture and commercial real estate, plus 2UniFi execution risk, which could all pull future profitability in very different directions.
Explore another National Bank Holdings fair value estimate, including one that suggests up to 58% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your National Bank Holdings research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for National Bank Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate National Bank Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond National Bank Holdings?
If the latest quarter at National Bank Holdings has you rethinking concentration in a single regional bank, it can help to line it up against a wider watchlist of companies with different balance sheet profiles, earnings drivers and risk levels using the Simply Wall St Screener.
- For readers who care most about financial resilience, start with companies that pass strict debt and liquidity filters through our list of solid balance sheet and fundamentals (24 results).
- If value is your priority, compare National Bank Holdings with other stocks that combine quality fundamentals with lower implied expectations using the 34 high quality undervalued stocks.
- Income focused investors can widen their search beyond a single bank by scanning a curated set of higher yielding payers via the 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com