


EN
Learn Why The Bull Case For First Solar Stock Could Change Following Lower 2026 Guidance
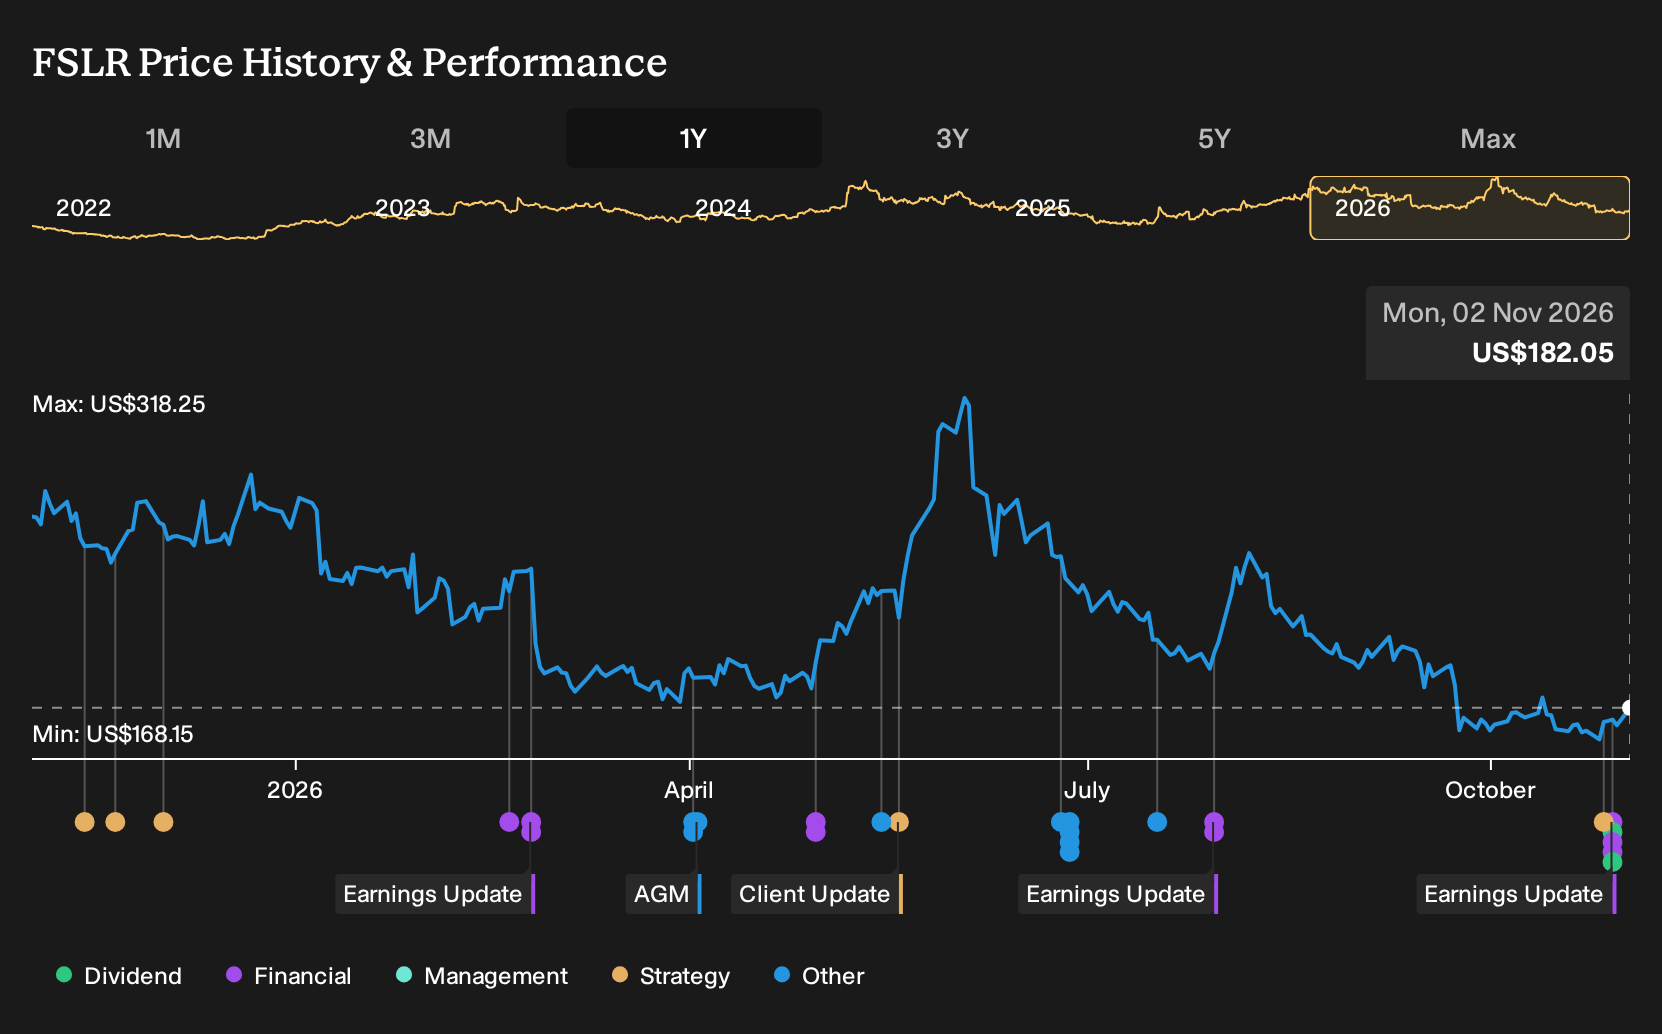
- First Solar reported third quarter 2026 sales of US$1,230.94 million and net income of US$571.06 million, while also lowering full year 2026 net sales and volume guidance and outlining softer module shipment expectations.
- The business paired this tempered outlook with a US$500 million share repurchase plan and continued U.S. manufacturing expansion, including its new South Carolina facility. This underscores a focus on domestic capacity and capital return.
- Next, the focus will shift to how First Solar's softer full year guidance and new buyback shape the broader investment narrative.
Scan how First Solar’s mixed guidance, South Carolina build out, and fresh buyback stack up against other potential opportunities in our hand picked 43 power grid technology and infrastructure stocks for the next phase of energy infrastructure.
First Solar Investment Narrative Recap
To own First Solar, you need to believe the company can turn its U.S. centric backlog, technology roadmap and domestic manufacturing push into durable earnings, even with choppy volumes. The latest quarter showed sales of US$1,230.94 million and net income of US$571.06 million, alongside softer 2026 sales and volume guidance that tempers near term momentum.
The key near term catalyst is still execution on U.S. output and project specific contracts that aim to lock in pricing and reduce inventory risk. The biggest current operational risk sits in underutilized overseas lines and higher logistics costs. The lower full year guidance highlights these issues rather than materially changing them.
The new US$500 million share repurchase plan ties directly into this earnings update. It sits on top of strong year to date net income of US$1,340.25 million and signals that management is comfortable committing capital while also investing in U.S. plants such as the facility in South Carolina.
For investors, the practical question is whether First Solar can keep funding CuRe roll out, perovskite development and potential shifts away from Malaysia if targets are missed, while still absorbing buybacks. Execution on those projects and on the 16.0 GW to 17.0 GW 2026 volume plan will likely matter more to the business than the headline size of the repurchase.
First Solar's current analyst narrative points to forecast revenue of US$6.9b and earnings of US$3.0b by 2029, built on projected revenue growth of 8.5% per year and an earnings increase of about US$1.3b from the US$1.7b level cited for today.
Discover how First Solar's fair value indicates a 52% potential upside to its current price that could close more quickly than many investors expect.
Exploring Other Perspectives
One alternate view around First Solar focuses on legal and tariff uncertainty rather than tariffs as a pure tailwind. The most bearish analysts were penciling in about US$6.3b of revenue and US$2.8b of earnings by 2029, which is below consensus. That darker storyline shows how widely opinions differ and invites you to explore several angles yourself.
Explore 7 other First Solar fair value estimates, including one that suggests it could be worth just $263.00!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your First Solar research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for First Solar. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Solar's overall financial health at a glance.
Looking for more investment ideas beyond First Solar?
Once you have formed a view on First Solar, it can help to compare it with other businesses that offer different combinations of resilience, income, and upside potential. The Simply Wall St Screener gives you a quick way to surface those contrasts without getting lost in noise.
- If capital preservation is front of mind, start with a basket of companies screened for balance sheet strength and consistent fundamentals through our list of solid balance sheet and fundamentals (24 results).
- If you are hunting for opportunities that the market may be overlooking, scan a curated group of financially healthy under the radar stocks via the 19 high quality undiscovered gems.
- If reliable cash payouts matter to your plan, compare potential yields and coverage metrics using the focused list of income generating companies in the 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com