


EN
Is Strong Drill Results Altering The Investment Case For IAMGOLD (TSX:IMG)?
- IAMGOLD reported past assay results from its 2025 to 2026 drilling at the Nelligan Mining Complex, Monster Lake and Philibert, confirming depth extensions, high grade gold intersections and updated mineral resource estimates across one of Canada’s larger pre production gold camps.
- The consolidation of Nelligan, Monster Lake and Philibert into a single Quebec gold hub gives IAMGOLD a clearer multi deposit pipeline that complements its focus on Côté Gold execution and operational cash flow.
- In this review, the focus is on how IAMGOLD's investment narrative is shaped by this larger Nelligan camp resource base and deeper mineralization.
Scan IAMGOLD's Quebec drilling story against a curated group of peers by reviewing our hand picked 34 elite gold producer stocks for ideas across the wider gold producer space.
IAMGOLD Investment Narrative Recap
To own IAMGOLD, you need to believe that Côté Gold can run reliably and that cash generation from Côté and Essakane can steadily improve the balance sheet. The Nelligan Mining Complex update strengthens the long term pipeline, but the key near term catalyst still sits with throughput, production and costs at Côté.
The biggest current risk remains execution slippage at core operations and any sustained pressure on all in sustaining costs or capital needs while net debt sits around $1b. The Quebec drill results do not materially change that risk. However, they do help frame where future capital could be directed once cash flow allows.
The Nelligan drilling update is the most relevant recent announcement for this story because it reframes Quebec as a potential second leg of the IAMGOLD portfolio. Investors now have clearer visibility on scale at Nelligan, Monster Lake and Philibert, with millions of ounces categorized as Indicated and Inferred resources.
That scale matters only if IAMGOLD can first stabilize Côté and Essakane and keep net debt trending lower. If operating execution improves and free cash flow grows, the Nelligan camp and a future economic study could become an important follow on catalyst. If costs or production disappoint, this pre production complex remains more of a medium term option than a near term driver.
IAMGOLD's current analyst narrative points to $3.9b in revenue and $1.3b in earnings by 2029, based on 2.2% yearly revenue growth and an earnings increase of about $100m from $1.2b today.
Discover why IAMGOLD's fair value indicates a 45% potential upside to its current price that may not last much longer.
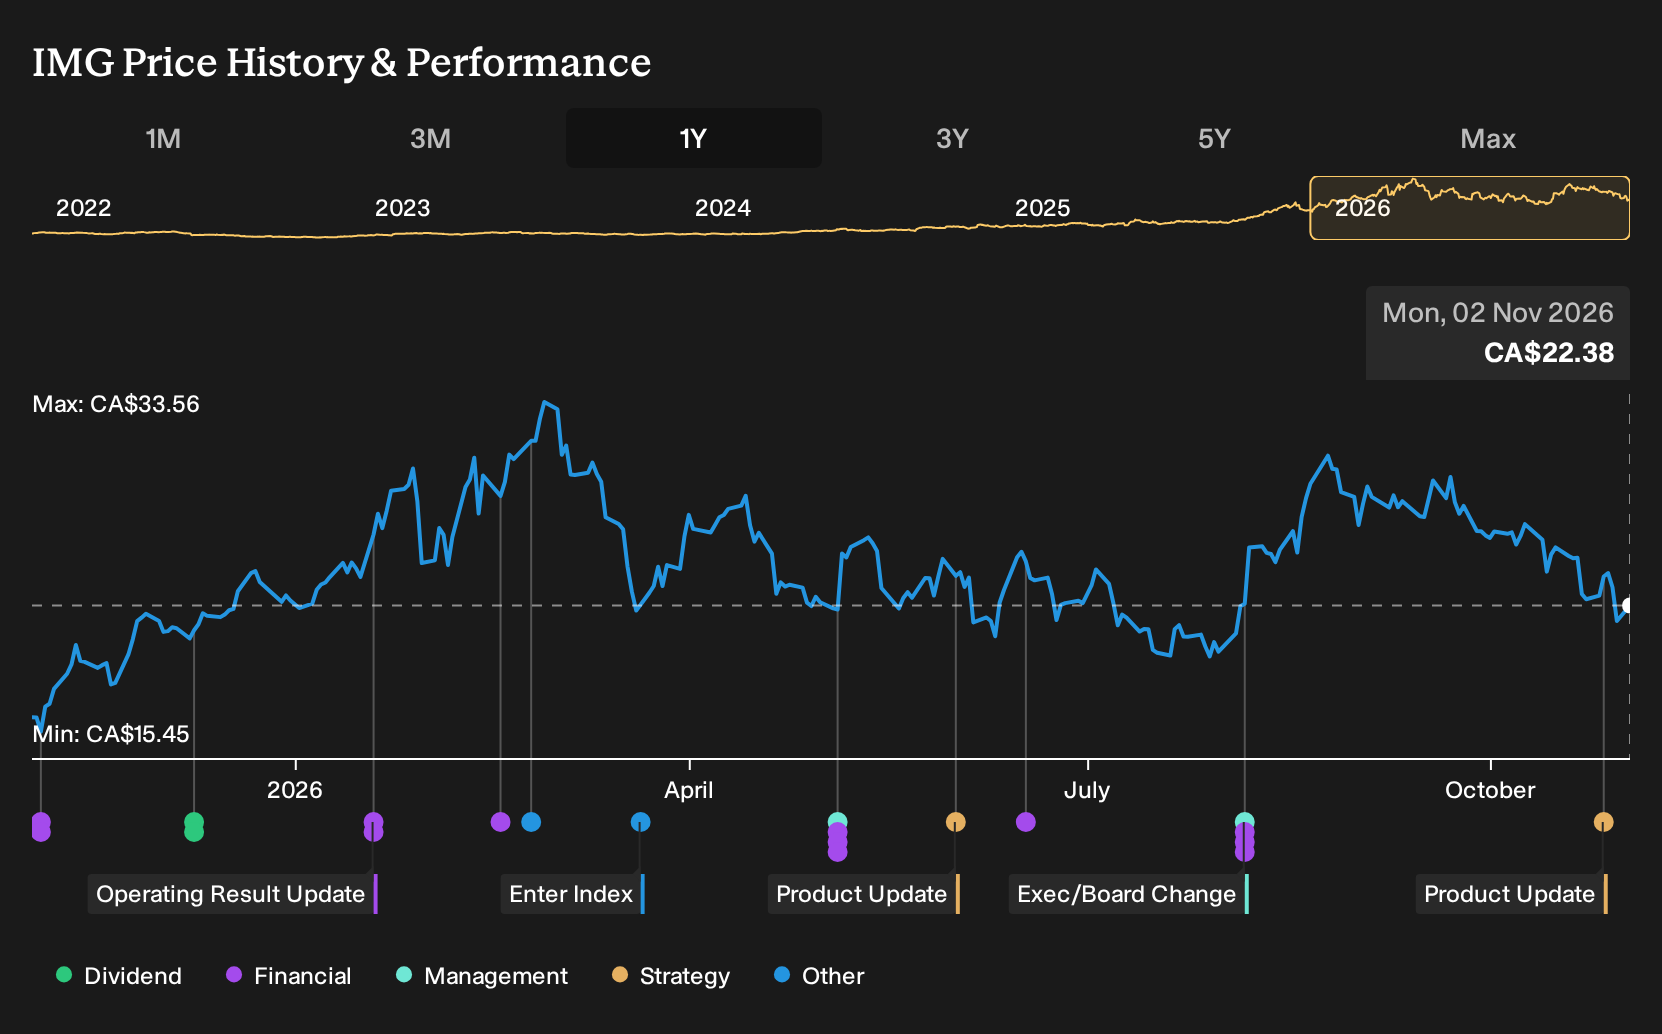
Exploring Other Perspectives
One alternative view puts cost pressure at the center of the IAMGOLD story. In that more cautious narrative, analysts assume profit margins drift from 31.4% to 30.0% and earnings stay around $1.2b, even by 2029. Those forecasts come from before this Quebec drilling news, so you may want to see how opinions shift as new data lands.
Explore 4 other IAMGOLD fair value estimates, including one that suggests it could be worth just CA$31.64!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your IAMGOLD research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for IAMGOLD. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IAMGOLD's overall financial health at a glance.
Looking for more IAMGOLD style investment ideas?
If the IAMGOLD story has sharpened your thinking about risk, balance sheets and future potential, use that same lens across the wider market with the Simply Wall St Screener.
- For investors who want income resilience at the center of their portfolio, scan a curated set of higher yield payers by reviewing our 3 dividend fortresses.
- If capital preservation and steadier fundamentals are your priority, filter for businesses with stronger financial footing using the list of solid balance sheet and fundamentals (6 results).
- When you are hunting for potential mispriced opportunities with quality metrics to match, widen your search with the 5 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com