


EN
What General Electric's Raised Guidance Means For Shareholders
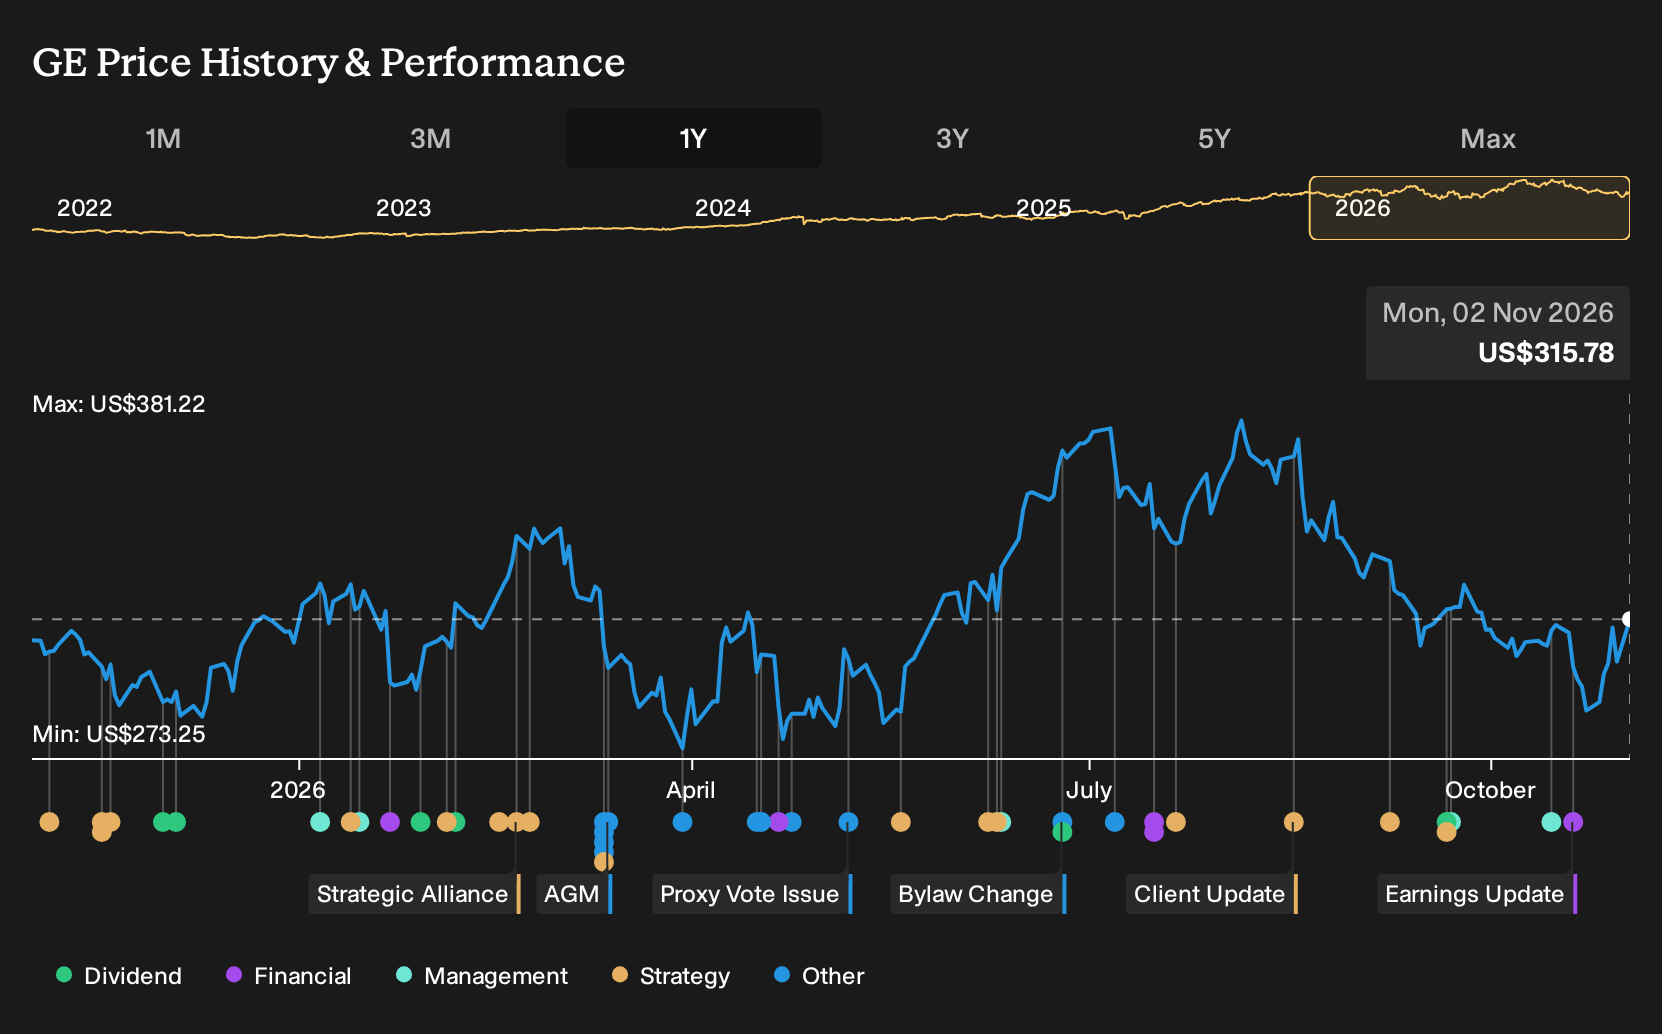
- General Electric reported Q3 2026 results with US$14,118 million in revenue and US$2,288 million in net income, alongside higher basic and diluted earnings per share from continuing operations compared with a year earlier.
- The business paired this profit update with progress on its share repurchase program and raised guidance tied to aerospace services and engine maintenance demand, highlighting that cash generation and capital returns now rely heavily on recurring aftermarket work.
- The focus now shifts to how General Electric's raised full year guidance tied to aerospace services may reshape the broader investment narrative.
Scan how other industrial and aerospace plays compare with General Electric's earnings and buyback story by reviewing our hand picked 43 power grid technology and infrastructure stocks in one place.
General Electric Investment Narrative Recap
To own General Electric, you need to believe its large commercial and defense engine base will keep feeding a long, service heavy earnings stream, and that the FLIGHT DECK operating model and added capacity will offset cost and supply stress. The latest quarter supports that story, although aftermarket demand also raises exposure to any future slowdown in airline flying.
Right now the key near term swing factor is how efficiently General Electric turns that services backlog into cash while absorbing lower margin LEAP work and early losses on GE9X. The biggest risk stays the same: a softer commercial aviation cycle or slower shop visits could quickly pressure revenue assumptions.
The most relevant update is the acquisition of Consolidated Precision Products, which expands turbine airfoil capacity and brings General Electric more vertically integrated control over a critical engine component. That matters directly to the services story, since reliable turbine blade supply underpins both engine deliveries and long term repair work.
If management hits integration targets, extra internal capacity can support higher engine output, help FLIGHT DECK driven productivity, and reduce reliance on external suppliers during tight conditions. Execution missteps would instead add complexity and cost at a time when margins already face pressure from newer platforms and durability concerns on certain GEnx blades.
General Electric's analyst narrative points to US$65.8b in revenue and US$12.3b in earnings by 2029. This setup assumes 7.7% yearly revenue growth and an earnings increase of about US$3.1b from US$9.2b today.
Uncover why General Electric's fair value indicates a 20% potential upside to its current price before the market squeezes that discount away.
Exploring Other Perspectives
Some of the most optimistic analysts care less about cycle risk and focus on General Electric lifting free cash flow conversion. Before this Q3 update, the bullish narrative already assumed revenue of about US$67.6b and earnings of roughly US$13.2b by 2029. You now get to judge whether the new earnings and buyback data push those assumptions even higher or pull them back.
Explore 8 other General Electric fair value estimates, including one that suggests as much as 38% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your General Electric research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for General Electric. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate General Electric's overall financial health at a glance.
Looking for more investment ideas beyond General Electric?
Once you have formed a view on General Electric, it can help to widen the lens and compare it with other opportunities that fit different risk and return profiles. The Simply Wall St Screener gives you a quick way to filter for businesses that match the themes you care about most.
- If capital preservation comes first for you, start with sturdier balance sheets and steadier fundamentals using our 29 resilient stocks with low risk scores.
- If income is a priority, scan for dependable payers with higher yields through the focused 4 dividend fortresses.
- If you like finding earlier stage opportunities with room for the story to develop, look through the curated 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com