


EN
How Investors May Respond To Diversified Healthcare Trust (DHC) Updated 2026 Guidance
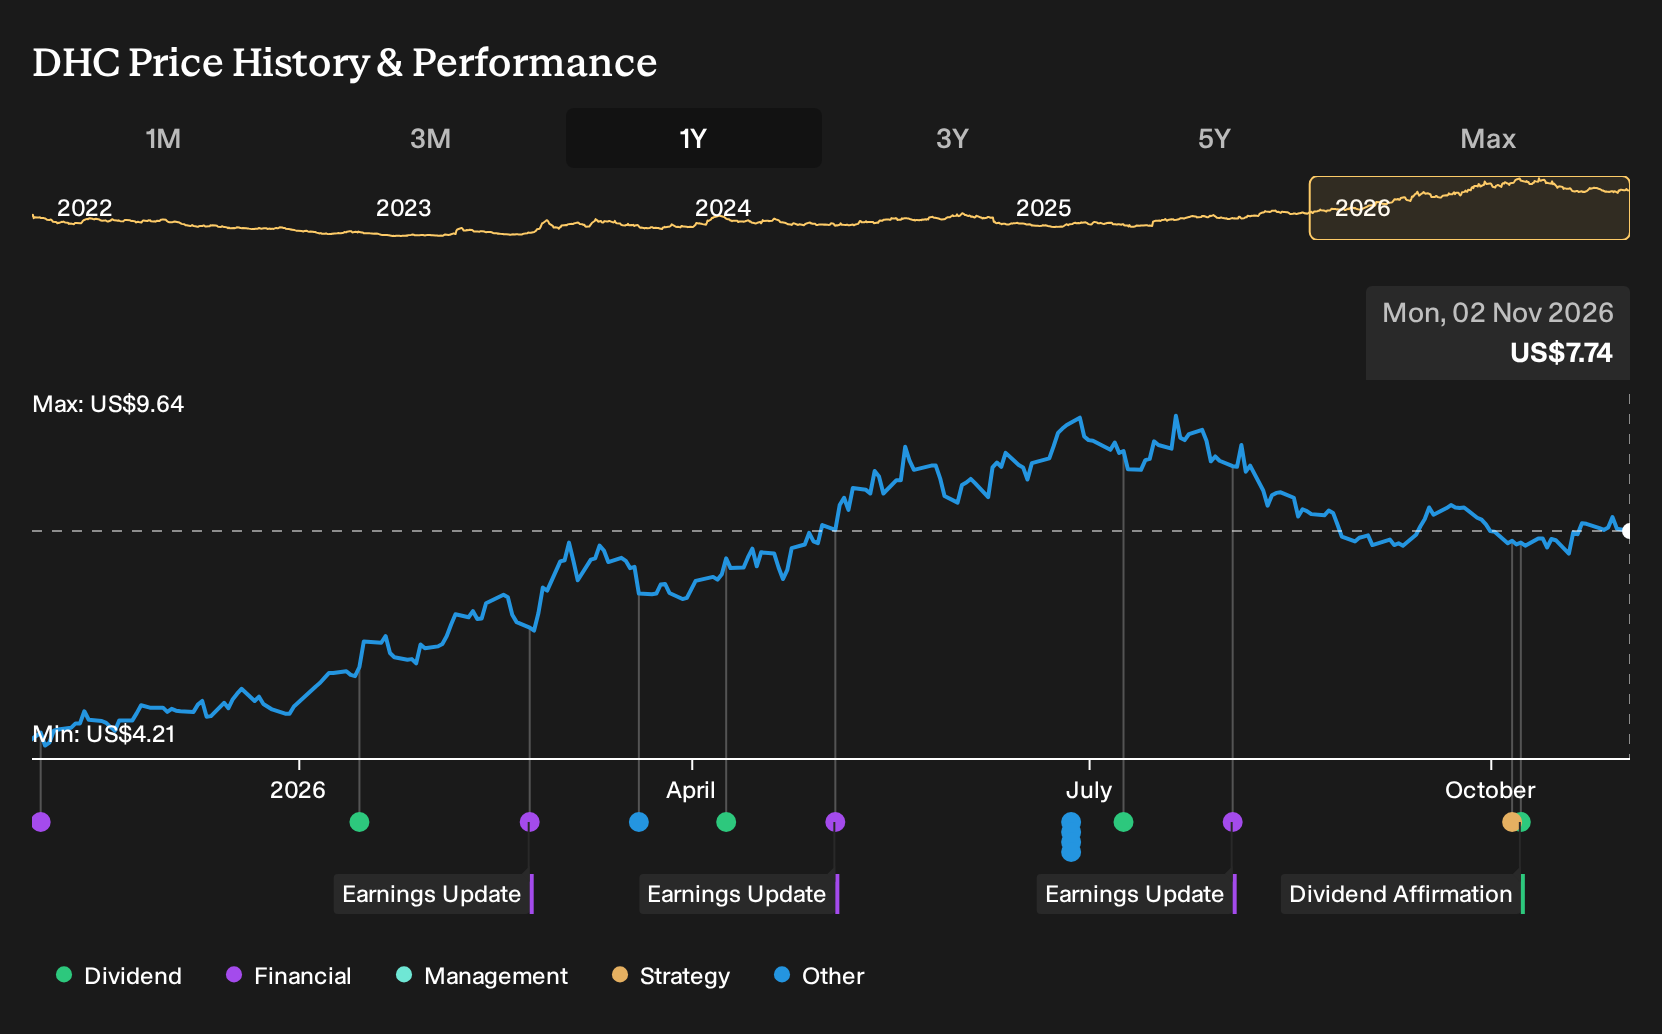
- Diversified Healthcare Trust released its third quarter 2026 results for the period ended 30 September and updated full year 2026 guidance, alongside plans to discuss the figures on a November 3 conference call.
- The updated outlook gives investors a fresh read on how senior housing, medical office, and life science properties are contributing across the portfolio and where operational pressure points may sit.
- We will look at how Diversified Healthcare Trust's refreshed 2026 guidance reshapes the existing investment narrative around senior housing execution.
Scan how Diversified Healthcare Trust stacks up against other listed landlords by moving through our hand picked list of solid balance sheet and fundamentals (24 results).
Diversified Healthcare Trust Investment Narrative Recap
To own Diversified Healthcare Trust, you need to believe the senior housing operating portfolio can translate occupancy and rate gains into cleaner cash generation while the medical office and life science segment holds its ground through known tenant vacates. The updated 2026 guidance gives you a fresh check on how those moving pieces line up with that thesis.
The biggest near term swing factor remains execution in senior housing and whether cost savings and internal ROI projects convert into higher NOI and, eventually, profitability. A key risk remains on the liability side. A high net debt to adjusted EBITDAre ratio and modest interest coverage keep refinancing costs and credit conditions front of mind.
The latest quarterly release and updated full year 2026 outlook matter because they sit against a backdrop of capital recycling and internal projects already in motion. Over US$600 million of asset sales since early 2025 and a reported net debt to adjusted EBITDAre ratio of 7.1x by Q2 2026 frame how much financial flexibility Diversified Healthcare Trust has as it executes.
That background makes the new guidance a way for you to test whether expected NOI from senior housing, stable occupancy in medical office and life science properties, and about US$20 million earmarked for converting skilled nursing wings into higher demand units are tracking closely enough to offset interest costs, upcoming tenant departures and continued net losses.
What The Long Term Consensus Implies For Diversified Healthcare Trust
Analysts are effectively asking investors to underwrite a different version of Diversified Healthcare Trust than the one reflected in current quarterly results. The stock analysis work suggests that by 2029 the business could be generating US$1.7b of revenue and US$132.3m of earnings, supported by an assumed 4.3% annual top line growth rate and a shift from a reported loss of US$266.0m today to positive net income. That path implies an earnings swing of roughly US$398m from current levels.
To align that with the analyst price target, investors would need to be comfortable that Diversified Healthcare Trust can eventually reach a profit margin broadly in line with the wider US health care REIT group. The consensus framework assumes margins move from a reported loss position of 17.7% to a positive 7.8% level by 2029, with the stock trading on a P/E of 22.9x those future earnings compared with a current multiple that is based on losses. In simple terms, the investment debate centers on whether that degree of operational and financial repair feels realistic, given current senior housing performance and the stability of the medical office and life science segment.
Diversified Healthcare Trust's current narrative sets out a path to revenue of US$1.7b and earnings of US$132.3m by 2029. This rests on 4.3% yearly revenue growth and an earnings increase of about US$398m from a current loss of US$266.0m.
Uncover why Diversified Healthcare Trust's fair value indicates a 31% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Diversified Healthcare Trust leans hard into the bullish catalyst of SHOP margin expansion. Those analysts were penciling in about 5.6% annual revenue growth and earnings of roughly US$196.1 million by 2029 before this Q3 update. You may see those forecasts shift as the new 2026 guidance beds in. It is therefore worth comparing several viewpoints before deciding how you feel about the story.
Explore another Diversified Healthcare Trust fair value estimate, including one that suggests potential upside of up to 175% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Diversified Healthcare Trust research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Diversified Healthcare Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Diversified Healthcare Trust's overall financial health at a glance.
Looking For More Investment Ideas Beyond Diversified Healthcare Trust?
If the Diversified Healthcare Trust story has sharpened your thinking about balance sheets, income potential, and risk, you can use that same lens on a wider set of opportunities with the Simply Wall St Screener.
- If you want to focus on resilient businesses with measured risk, start by scanning a curated set of 29 resilient stocks with low risk scores that may suit a more cautious approach.
- If reliable income is a priority, you can look at potential payout candidates drawn from our 4 dividend fortresses that already clear a 5% yield hurdle.
- If you are hunting for mispriced opportunities, consider broadening your watchlist with a hand picked 33 high quality undervalued stocks that pair stronger balance sheets with solid cash generation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com