


EN
3 Australian Dividend Stocks To Own In November 2026
Rising energy costs are starting to bite global manufacturers, and that pressure can feed into everything from power bills to supermarket prices in Australia. Reliable cash payouts suddenly look more appealing when inflation risk feels less distant. Well covered local dividend payers offering yields above 3% can help steady a portfolio. This article highlights three Australian dividend stocks that currently meet that quality income test.
The three stocks highlighted here offer a compelling starting point if you want exposure to well covered, growing and stable dividend payers yielding above 3%. However, if you want the absolute best, these 4 dividend aristocrats stocks are the cream of the crop.
Computershare (ASX:CPU)
Overview: Computershare provides shareholder registry management, corporate trust and employee share plan services, with issuer and dividend administration closely tied to dividend flows.
Operations: Computershare generates about US$1.3b from Issuer Services and US$1.0b from Corporate Trust, with most revenue coming from the United States and UK regions.
Market Cap: A$24.7b
For a dividend-focused investor, Computershare matters because it helps listed businesses keep their shareholder records clean and dividend payments flowing smoothly, so its fortunes are tightly linked to how active and healthy global payout markets remain.
"Importantly, this assessment is based primarily on Computershare’s existing operations, current client balances and FY26 earnings guidance."
What really influences Computershare’s appeal to income-focused investors is how one less visible earnings lever behaves over time.
That quiet earnings lever is exactly what the full narrative for Computershare unpacks, showing where dividend-linked cash flows could accelerate or quietly stall next.

BHP Group (ASX:BHP)
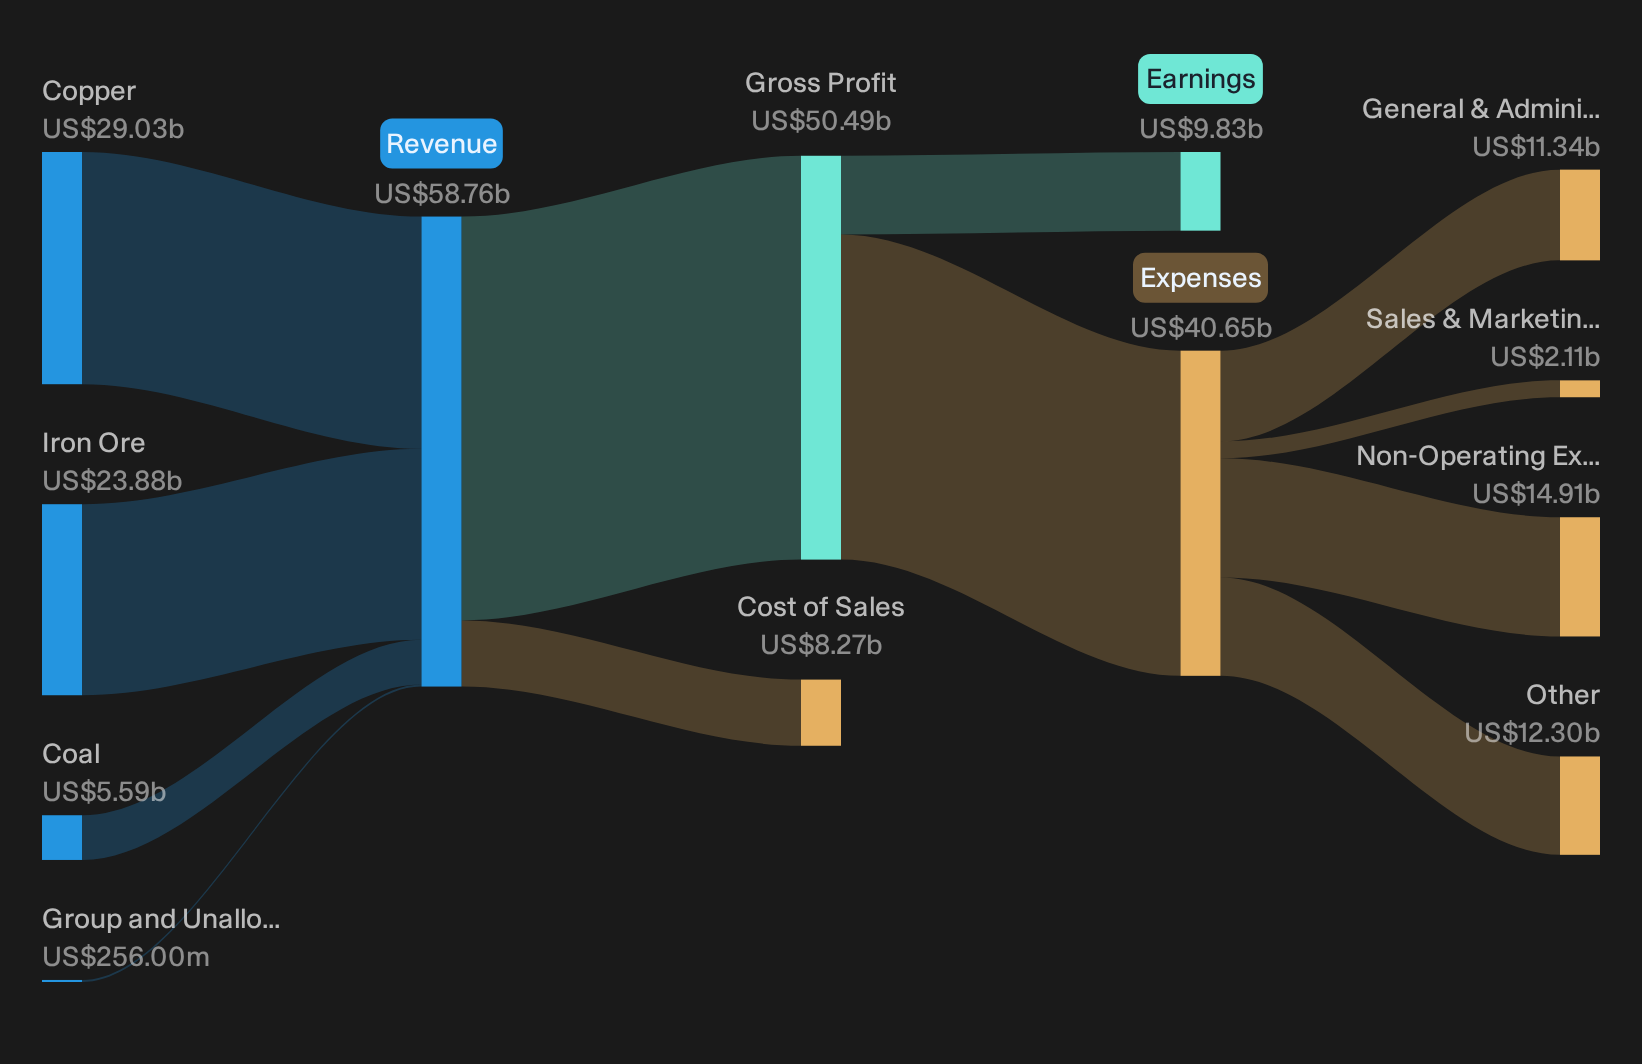
Overview: BHP Group is a global resources company that produces iron ore, copper and coal, with these long-life assets supporting its dividend stream.
Operations: BHP generates about US$29.0b from Copper, US$23.9b from Iron Ore and US$5.6b from Coal, largely selling into China and broader Asia.
Market Cap: A$288.4b
BHP Group is often considered by income-focused investors because its iron ore and copper operations generate the cash that supports a dividend yield above 3%. This gives the Dividend Powerhouses theme a direct link to long-life mining assets rather than short-term trading swings.
"A strong pipeline of copper and potash projects positions BHP Group to benefit from a global surge in decarbonization efforts and electrification initiatives, with rising demand for critical minerals expected to influence future revenues."
What really matters for BHP’s future dividends is how one unresolved production and cost pressure shapes margins just as those new projects scale.
As those margin questions build, the full narrative for BHP Group maps where decarbonization demand, capital discipline and cost pressures could be quietly reshaping BHP Group’s long term dividend firepower.
QBE Insurance Group (ASX:QBE)
Overview: QBE Insurance Group underwrites general and reinsurance policies across property, casualty and specialty lines, using recurring premiums and investments to support dividends.
Operations: QBE Insurance Group generates about US$12.2b from International, US$8.3b from North America and US$5.8b from Australia Pacific, plus smaller corporate income.
Market Cap: A$38.5b
For income hunters, QBE Insurance Group matters because its broad insurance book and in-house investing create recurring cash flows that can support a covered, 3%+ dividend and provide exposure to global underwriting cycles.
"Ongoing transformation through cloud, AI and automation, including a plan to at least double production AI agents after early gains such as faster marine and motor claims handling, is aimed at structurally lowering the expense ratio and supporting a more stable combined ratio and earnings base over time."
What could really shape QBE Insurance Group’s future dividend strength is how one less visible pressure on underwriting profitability ultimately resolves.
If you want to see how that pressure could be quietly accelerating or capping QBE Insurance Group’s payout potential, read the full narrative for QBE Insurance Group for the full picture.

Seeking Fresh Alternatives For Your Income?
Markets move fast and the next wave of dividend and growth stories can start breaking out before most investors notice. Screen fresh ideas while it matters and act now.
- Spot resilient payers before momentum really starts flying by running your filters through the list of solid balance sheet and fundamentals (12 results), curated from balance sheets that currently look built for stress.
- Chase early upside potential in niche miners and producers with the 34 elite gold producer stocks, curated to focus on operators already producing and generating real cash flow.
- Position ahead of the next infrastructure upgrade cycle using the 43 power grid technology and infrastructure stocks, built around companies exposed to grid modernisation and electrification projects.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com