


EN
Are Strong Earnings Altering The Investment Case For German American Bancorp Stock?
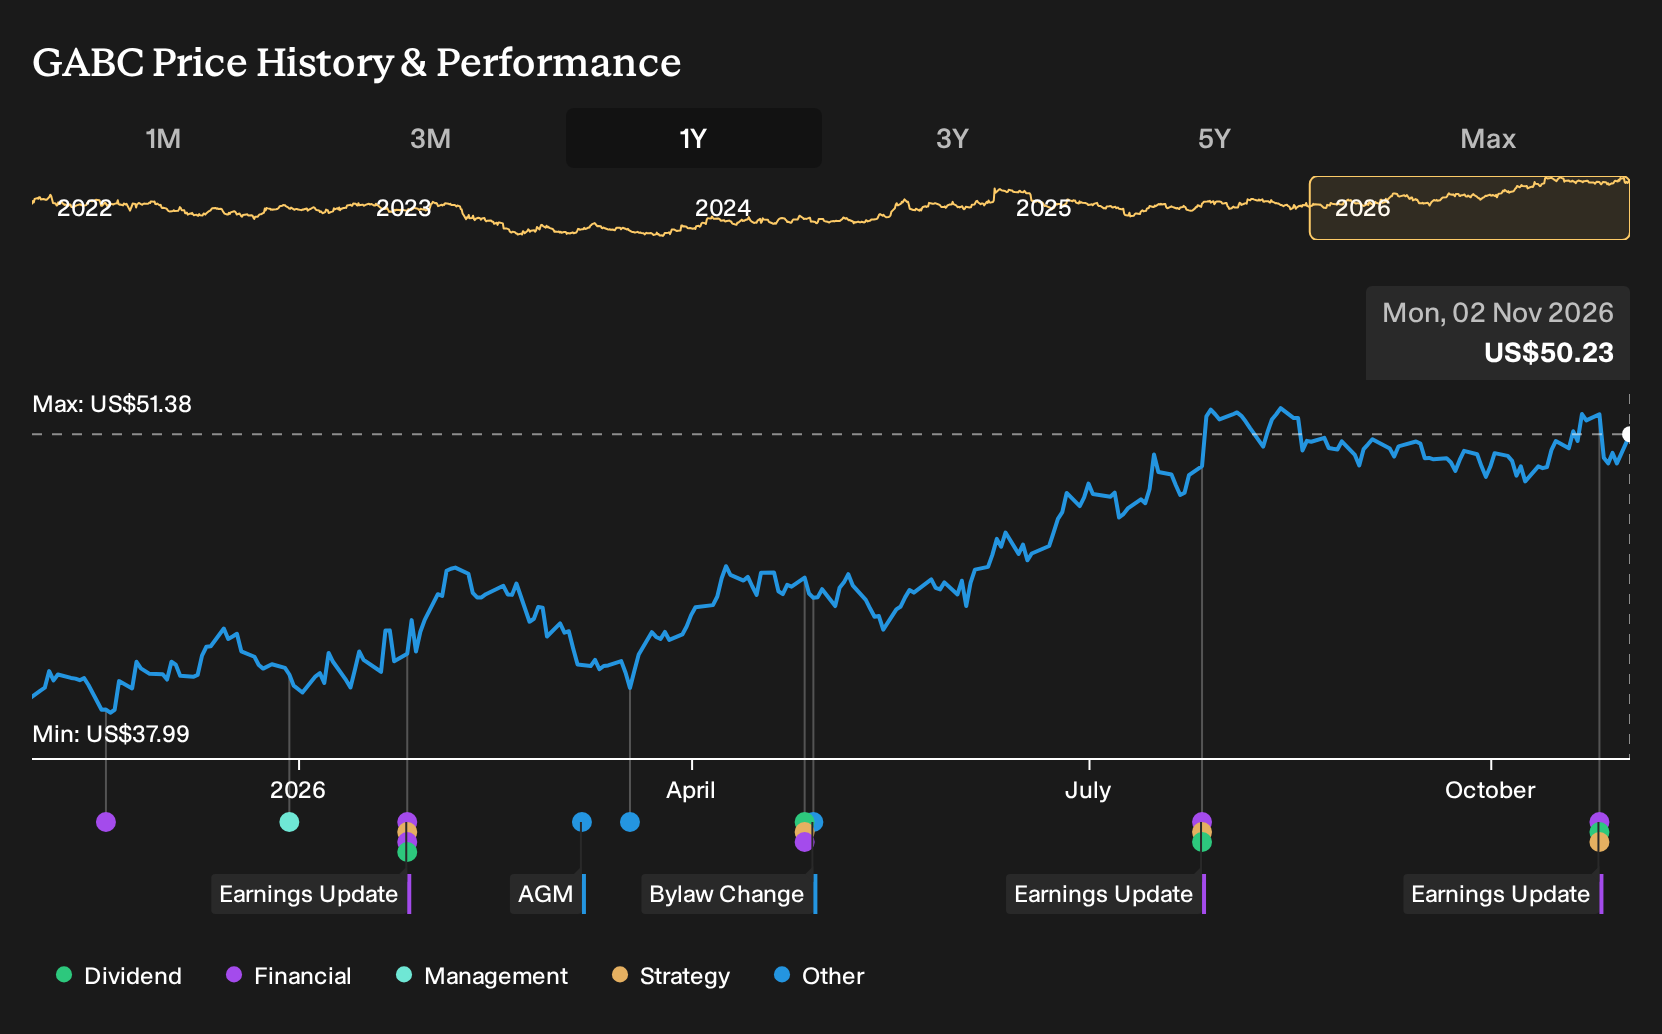
- German American Bancorp reported third quarter 2026 net interest income of US$83.52 million and net income of US$38.64 million, with basic and diluted EPS from continuing operations of US$1.03. The company also disclosed nine month 2026 results and net charge offs as of September 30.
- The board maintained a regular cash dividend of US$0.31 per share, which provides an income stream for shareholders alongside higher year to date earnings per share compared with the prior year period.
- The next step is to consider how German American Bancorp's investment narrative is influenced by the stronger quarterly earnings and the dividend decision.
Scan how German American Bancorp's latest earnings and dividend compare with a hand picked set of banks and lenders in the 29 resilient stocks with low risk scores.
German American Bancorp Investment Narrative Recap
To own German American Bancorp, you need to be comfortable with a regional bank that is relying on a wider footprint, technology spending and fee income projects to keep earnings moving while working on efficiency and capital strength. The latest quarter points to solid net interest income and profit. However, the key near term catalyst still hinges on turning that revenue base into consistently stronger margins.
The main risk remains that operating costs and capital build do not keep up with balance sheet growth. That could limit flexibility as the bank prepares for the US$10b asset threshold. Third quarter results and modest net charge offs do not materially change that risk reward balance in the short term.
The most relevant announcement here is the third quarter 2026 earnings release because it directly feeds into those efficiency and capital questions. Net interest income of US$83.52 million and net income of US$38.64 million, alongside basic EPS from continuing operations of US$1.03, provide fresh data on how German American Bancorp is monetizing its enlarged footprint.
Over the first nine months of 2026, net interest income of US$243.58 million and net income of US$109.96 million, with EPS from continuing operations of US$2.93, help you gauge whether integration of Heartland, technology investments and preparation for higher regulatory thresholds are translating into earnings. These figures also set the bar for how much improvement in efficiency and capital generation investors may look for next.
German American Bancorp's narrative projects US$472.1 million in revenue and US$168.4 million in earnings by 2029. This assumes 7.5% yearly revenue growth and an earnings increase of about US$26.3 million from US$142.1 million today.
Uncover why German American Bancorp's fair value indicates a 15% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$56.20 and about US$92.17, which shows how far apart retail views on German American Bancorp can be. When you set those opinions against risks around efficiency, capital build and the upcoming US$10b threshold, you have strong reasons to compare multiple viewpoints yourself.
Explore 2 other German American Bancorp fair value estimates, including one that suggests as much as 88% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your German American Bancorp research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for German American Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate German American Bancorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond German American Bancorp?
Once you have formed a view on German American Bancorp, it can help to benchmark that thesis against other opportunities using the Simply Wall St Screener. You keep the same disciplined process but apply it across different sectors, income profiles and balance sheet strengths.
- If you want income to do more of the heavy lifting in your returns, consider high yield opportunities by scanning a curated set of 5 dividend fortresses.
- For investors focused on resilience and capital preservation, filter for businesses with stronger financial footing through the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for ideas that the market may not be paying much attention to yet, broaden your watchlist with a focused group of 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com