


EN
Zai Lab (ZLAB) Phase 1b Lung Cancer Data Lifts The Case For Undervalued Shares
Zai Lab (NasdaqGM:ZLAB) stock is in focus after the company released first data from a global Phase 1b trial for lung cancer candidate zocilurtatug pelitecan, supporting a planned Phase 3 study.
The latest lung cancer data lands after a volatile stretch for Zai Lab, with the stock down 9.3% on a 7-day share price return and 9.3% on a 30-day share price return, yet up 19.4% over 90 days and 27.4% year to date. Long term total shareholder returns of 17.5% over one year and 74.7% over five years are still in decline, showing short term momentum picking up against a weaker multi year record.
Scan how Zai Lab fits into the wider opportunity set by comparing it with 19 high quality undiscovered gems in the same broader hunt for under-the-radar healthcare potential.
Zai Lab now trades at a steep discount to both analyst targets and an implied fair value, yet recent volatility signals investors are still wary. Is that caution supported once you line up the current price against fundamentals?
Most Popular Narrative: 34% Undervalued
Zai Lab closed at $22.07 against a widely followed fair value estimate of $33.30, which frames the current DLL3 story as a valuation gap rather than just a trading bounce.
Multiple high-potential product launches and label expansions over the next 12-18 months (including VYVGART, bemarituzumab, KarXT, TIVDAK, Tumor Treating Fields), combined with a deep pipeline in oncology and immunology, are expected to significantly increase Zai Lab's addressable market and diversify revenue streams, supporting both top-line growth and future earnings.
See why 13 investors see Zai Lab as 34% undervalued.
The popular narrative applies a discount rate of 7.87% to those future cash flows and arrives at a fair value of $33.30 per share, which is roughly one third above where Zai Lab trades today. That contrasts with the current analyst consensus target of $33.30 and sits against a long term total shareholder return that declined 17.5% over one year and 74.7% over five years.
Analysts in that storyline also expect revenue to compound at about 22.4% a year, with margins moving toward 19.0%, even though Zai Lab currently reports a loss of $188.2m on $449.6m of sales. That backdrop helps explain why some investors focus on the future earnings profile rather than recent underperformance, while others question whether the assumed path to profitability and the implied future P/E of 31.5x are too demanding.
Result: Fair Value of $33.30 (UNDERVALUED)
Still, reliance on licensed drugs and heavy R&D and SG&A spending could pressure Zai Lab if new launches and indications do not scale as analysts anticipate.
Find out about the key risks to this Zai Lab narrative.
Another View: Zai Lab On Sales Multiples
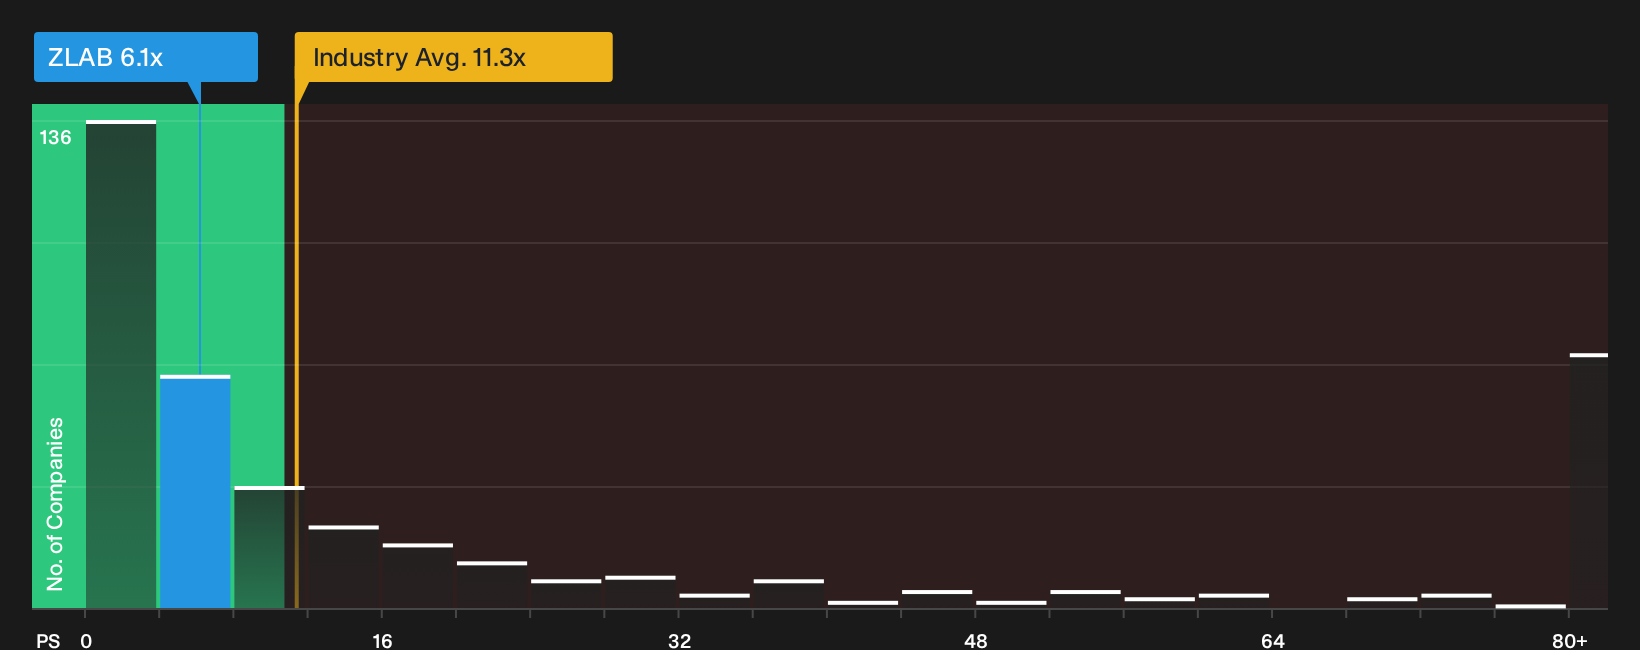
The DCF based narrative paints Zai Lab as heavily undervalued, but the P/S ratio tells a more cautious story. The stock trades on 6.1x sales, compared with a fair ratio of 3.3x and a US Biotechs average of 11.3x, which suggests meaningful valuation risk if sentiment cools.
For investors weighing these conflicting signals, the key question is whether the market edges closer to the higher peer level or leans back toward that lower fair ratio as expectations reset.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Zai Lab's valuation and execution story are clear, so consider reviewing the situation while sentiment is still forming and stress test the 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Zai Lab?
If you stop with Zai Lab, you only see one angle. Use curated stock lists to spot fresh ideas before they hit everyone else's radar.
- Target potential mispricing by reviewing companies screened as 36 high quality undervalued stocks that pair quality fundamentals with prices that still lag their underlying business strength.
- Prioritize resilience and peace of mind by checking 29 resilient stocks with low risk scores where balance sheets and risk scores aim to keep surprises in check.
- Sharpen your watchlist with a list of solid balance sheet and fundamentals (24 results) that can handle shocks while still backing credible long term business plans.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com