


EN
Meta Platforms (META) Faces Negative Free Cash Flow From AI Spending
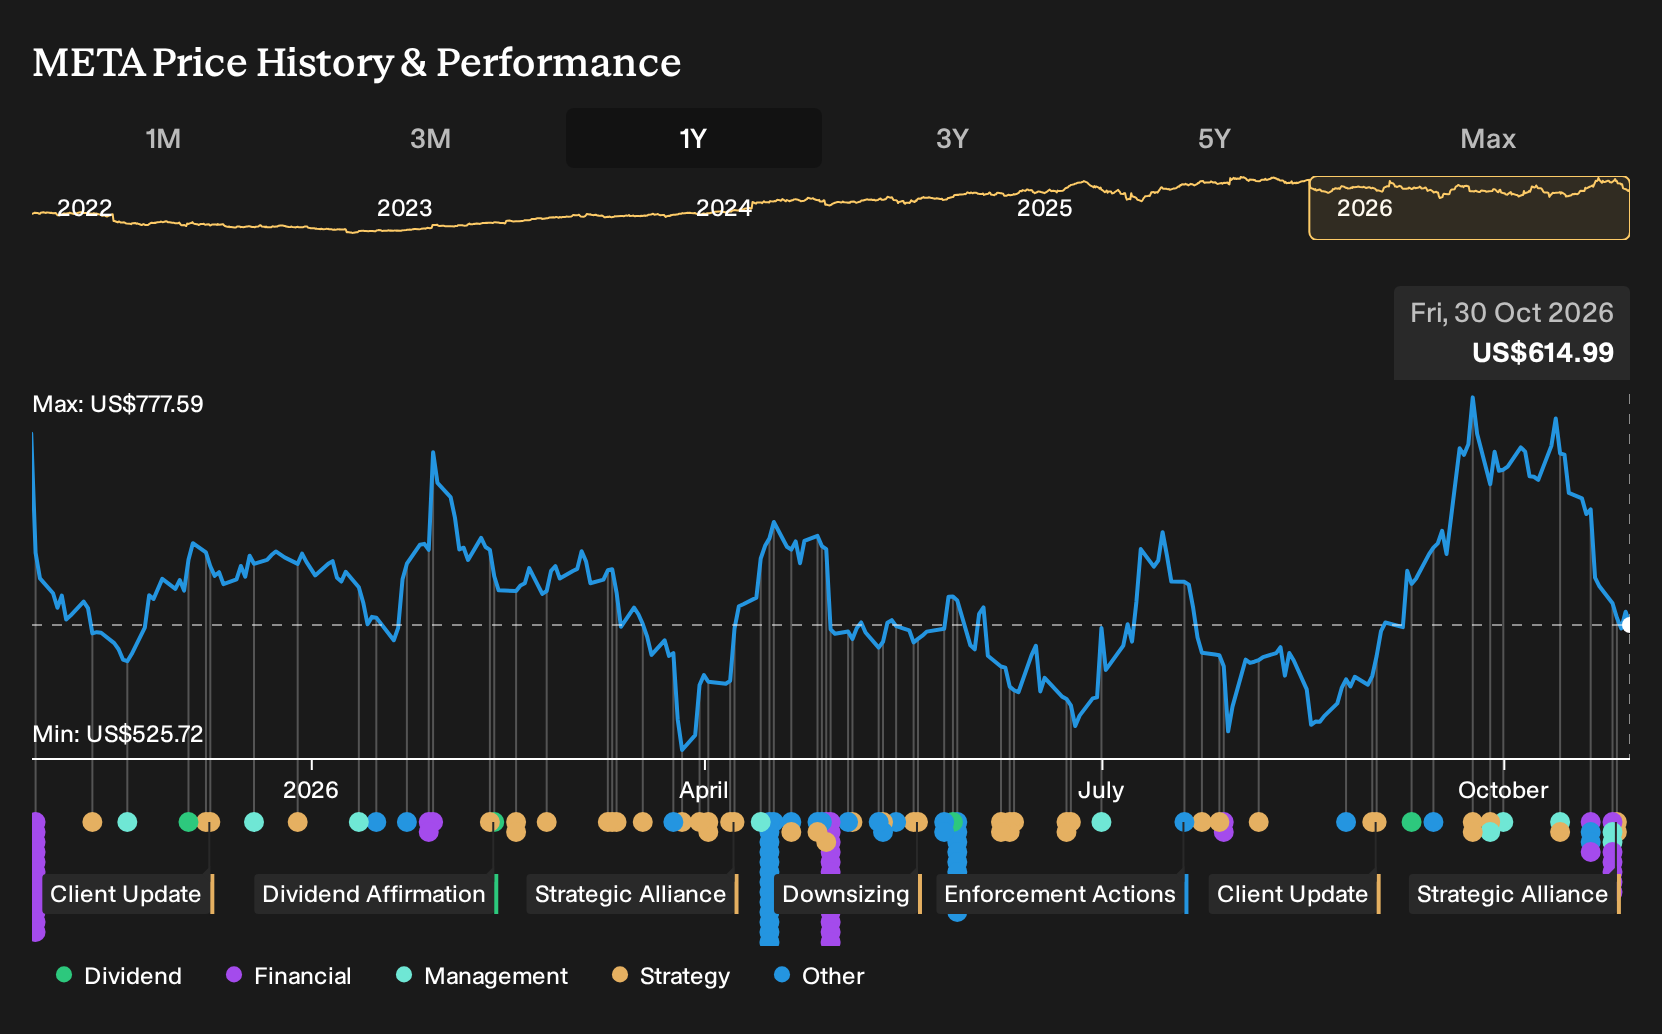
- Meta Platforms (NasdaqGS:META) shares were hit in a broad tech sell off as heavy AI investment led to negative free cash flow, the first since 2012.
- Ratings agencies cut Meta's credit outlook after the AI spending plan raised concerns over cash generation and balance sheet flexibility.
- Management is building a bipartisan political team in Washington to influence emerging AI rules and protect its data center expansion plans.
- The sell off linked to AI capex, negative free cash flow and the outlook downgrade is only one part of the Meta story. We have also spotted 4 other big wins worth knowing about at Meta Platforms.
Big tech is pouring money into AI infrastructure, and the knock on effects are reshaping a much wider set of companies. 54 AI infrastructure stocks
Meta Platforms runs social networks and hardware like VR headsets and AI glasses across major global regions, which gives its AI push direct access to user data and computing needs. That reach helps explain why regulators, credit agencies and policymakers all pay close attention when its spending plans shift.
See which insiders are buying and selling Meta Platforms following this latest news.
Why did Meta Platforms get hit so hard in this tech sell-off?
Meta Platforms pushed AI capital expenditure so far that free cash flow turned negative for the first time since 2012 and S&P moved its credit outlook to negative. That combination spooked investors who had become used to strong cash generation. The result is a market that is suddenly pricing funding risk, not just AI excitement.
Does this change the Meta Platforms Narrative or just sharpen it?
The Narrative already hinges on US$130 to US$145 billion of 2026 AI capex and large, multi-year compute commitments turning into durable earnings that offset legal and regulatory costs. Negative free cash flow and an outlook downgrade pull the risk side of that story into sharper focus but do not negate analyst expectations around AI-driven ad performance and messaging monetization.
See how these catalysts shape Meta Platforms' path to a $848 fair value.
What should investors watch next to test this read on Meta?
Investors are likely to focus on the next few quarters of reported cash flow and capex guidance, plus the terms on Meta’s new US$35 billion of completed equity and preferred raises and any future bond deals. A clear signpost would be management either tightening AI spending guidance or sustaining current capex while cash from ads, Muse agents, and messaging turns positive again.
The quiet valuation clue hiding inside Meta Platforms' own cash flows
Most holders watch Meta Platforms' share price and quarterly headlines, yet few stop to compare a cash-flow-based estimate of the whole business against where the stock actually trades today. Find out exactly what Meta Platforms is worth today based on its cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com