


EN
Core Scientific (CORZ) Shares Slid, So What Is Driving Attention Now?
Core Scientific (CORZ) is back in focus after a clear pivot toward AI and high performance computing colocation, supported by long term power contracts tied to CoreWeave and AMD partnerships.
Despite the AI pivot grabbing headlines, Core Scientific’s recent trading tells a different story. The share price has fallen 8.18% over the last day and 19.45% over 30 days, and the 1 year total shareholder return is down 42.14%. This points to fading momentum as investors reassess both execution risk and the long runway implied by its long term power contracts.
Scan how other AI infrastructure plays are setting up for their next phase by checking the hand picked 54 AI infrastructure stocks alongside Core Scientific’s pivot.
Bulls point to Core Scientific’s long term AI power contracts and rapid colocation ramp, while bears focus on share price declines and past losses. Which story does the current valuation lean toward next?
Most Popular Narrative: 58% Undervalued
Core Scientific’s most followed valuation storyline points to a fair value of $31.48 per share, compared with the last close at $13.25. This comparison highlights a substantial gap between what the narrative models in and where the market is pricing the stock today.
Core Scientific secured a major HPC contract with CoreWeave, with a total revenue potential of $8.7 billion over a 12-year term, significantly boosting future revenue compared to their current levels. The company is expanding HPC infrastructure capacity by reallocating resources from Bitcoin mining, adding new sites, and extending existing ones, expecting to drive future revenue growth as data center needs rise.
See why 65 investors see Core Scientific as 58% undervalued.
Result: Fair Value of $31.48 (UNDERVALUED)
Still, the Core Scientific story can change quickly if CoreWeave’s concentration risk bites or if delays in new AI and HPC capacity push out the expected revenue ramp.
Find out about the key risks to this Core Scientific narrative.
Another View: Multiples Paint a Tougher Picture for Core Scientific
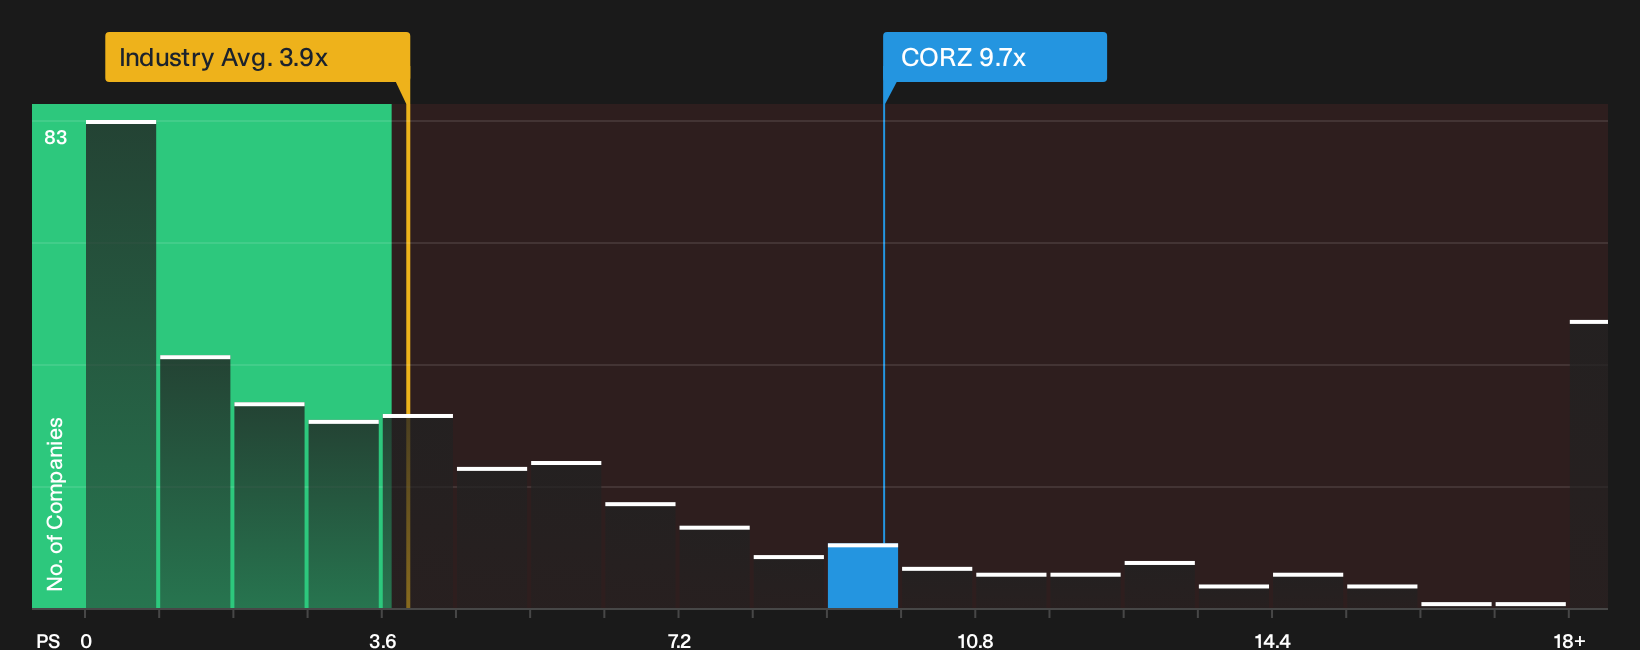
That 58% upside narrative sits next to a very different signal. On a P/S basis, Core Scientific trades around 9.7x, compared with about 3x for direct peers and 3.9x for the broader US Software group, while the fair ratio sits closer to 5.1x.
This gap suggests investors today are already paying a premium price for future AI and HPC execution, even before Core Scientific reaches profitability. If sentiment cools or expectations reset, does the story converge toward the analyst fair value or toward that lower fair ratio instead?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals dominate the Core Scientific story right now. Move quickly, pull up the data for yourself, and stress test both sides of the argument using 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Core Scientific?
If Core Scientific has sharpened your focus on where capital can really work, broaden your watchlist with a few targeted sets of ideas built from the Simply Wall Street Screener.
- Target resilience first by reviewing a list of solid balance sheet and fundamentals (24 results) that can better withstand shocks when conditions change.
- Hunt for mispriced potential and scan a 19 high quality undiscovered gems that many investors may not be paying attention to yet.
- Prioritise sleep at night investing and filter for a 29 resilient stocks with low risk scores so your next decision is grounded in measured downside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com