


EN
What Tripadvisor Doubters Saw Before The Drop
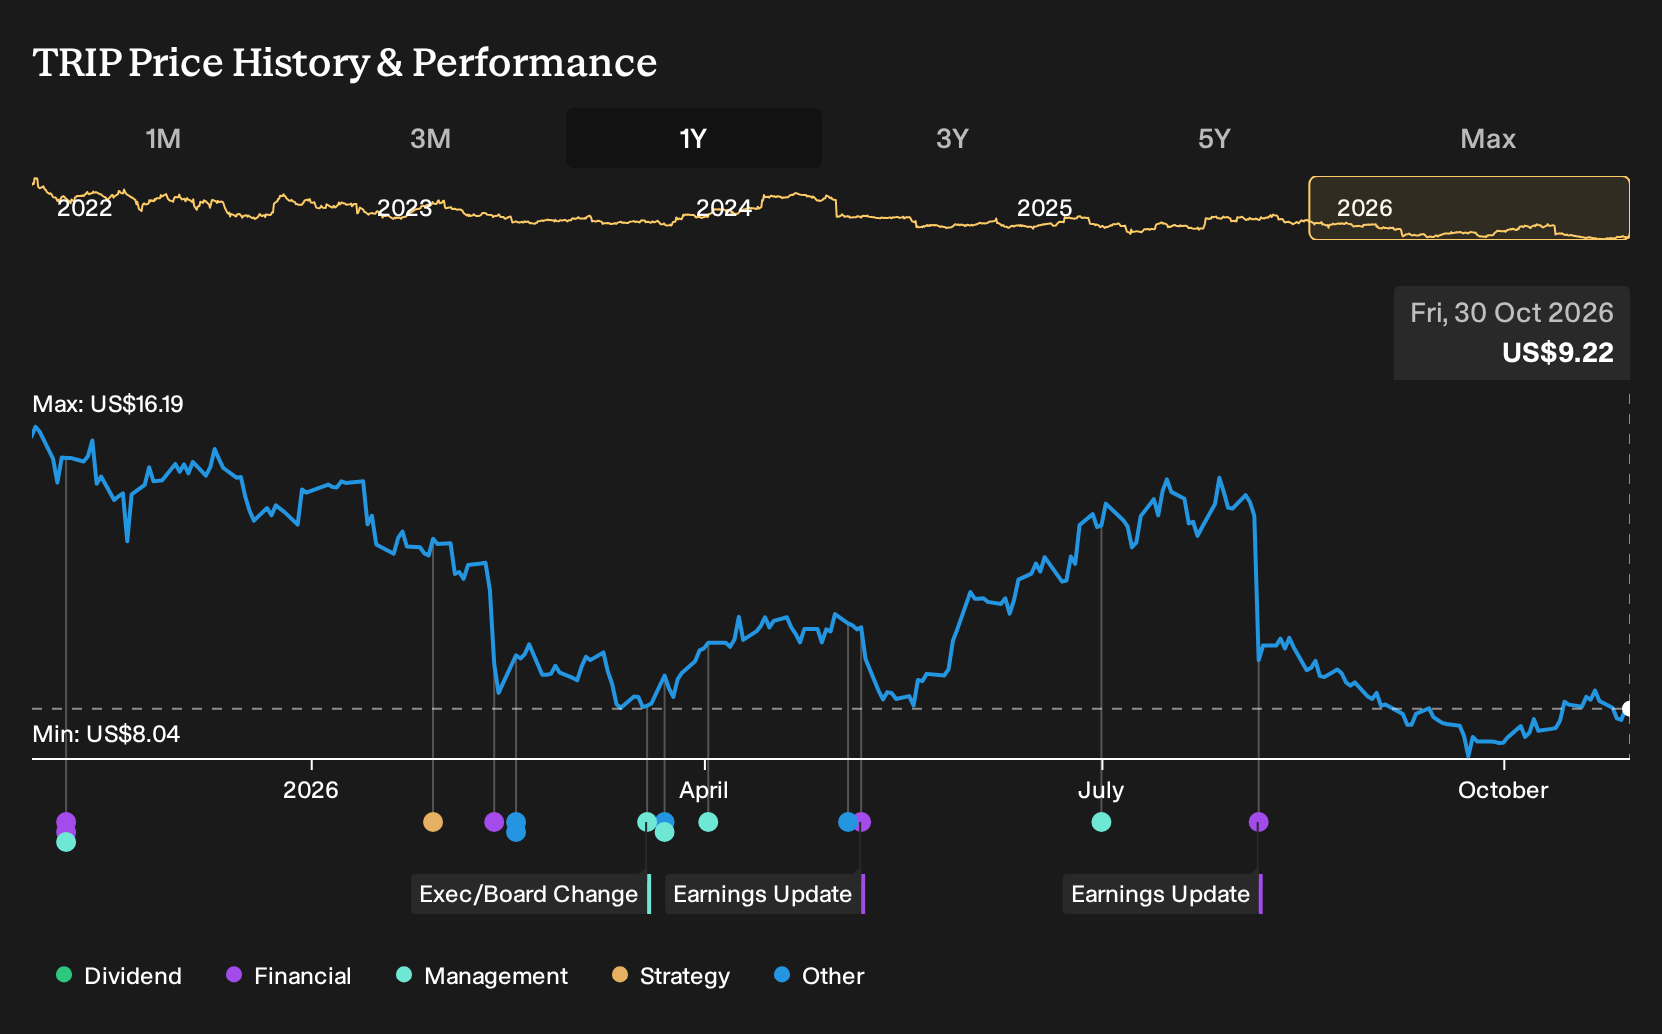
Tripadvisor’s headline this year was the US$700 million sale of TheFork to American Express, so the market finally got clarity on where management wants to focus. Investors who held Tripadvisor over the past year are down 40.1%, including dividends. That loss reflects everything that hit and helped the business across the period, not just one restaurant-platform deal. If you were sizing up Tripadvisor back on 30 October 2025, which expectations about experiences, AI and regulation most needed testing?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Tripadvisor. Zero in on 36 high quality undervalued stocks for companies trading below our estimates.
The Two Tripadvisor Stories Investors Were Arguing About
The shares cost US$16.19 at the start of the period, so any call on Tripadvisor began with what you believed the core travel platform could become.
On the bull side, a Fair Value of US$17.77 rested on experiences and AI. The optimistic case leaned on expansion of Viator and TheFork, as well as personalized, AI-powered recommendations to deepen engagement and lift margins while reducing dependence on paid traffic.
The bear Narrative put Fair Value at US$13. It focused on AI competition from larger platforms and tightening rules such as GDPR and CCPA, which could push up compliance costs and limit Tripadvisor’s ability to monetize user data.
What Tripadvisor’s Results Actually Tested
TheFork sale to American Express for US$700 million backed the bullish Tripadvisor story about focusing on Viator and experiences. Yet Q2 2026 results showed revenue at US$441.9 million versus US$476 million a year earlier, with net margin sliding from 7.7% to 5.2%, which challenged the profitability part of that optimistic case. Overall, the evidence cut both ways.
The lesson is simple. When a thesis leans on higher quality earnings, watch net margin and segment mix, not just headline revenue or deal headlines at any travel platform.
What Tripadvisor’s Drop Leaves You Paying For Today
Tripadvisor trades at US$9.22 after a 40.1% loss over the past year, and the selected Narrative’s Fair Value sits above that quote. The argument leans on Experiences, AI-led trip planning and portfolio streamlining to carry more of the heavy lifting as older SEO-reliant lines shrink.
For the fall to look like an opportunity rather than a warning, a buyer today would need confidence that Tripadvisor can successfully shift revenue and earnings mix toward repeat Experiences customers and AI products while managing ongoing SEO and travel demand pressure.
"The main thing that has to go right is that Tripadvisor successfully reallocates capital from shrinking SEO-dependent hotel and media lines into Experiences and AI products that attract repeat customers and profitable B2B2C partners."
One Narrative disagrees with today's price. → See where this Narrative says Tripadvisor should trade
Go Straight To The Source
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 48% below our estimate - convert a record backlog of technology-heavy projects into intensive construction activity.
- Company 2 - 28% below our estimate - align major AI data center buildouts with hybrid subscription and usage-based pricing structures.
- Company 3 - 41% below our estimate - tackle complex AI-related failure, safety and regulatory disputes requiring multidisciplinary expert teams.
That is three of the list. See all 24 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com