


EN
Public Service Enterprise Group (PEG), Why Is It Back In The Spotlight?
Public Service Enterprise Group earnings jolt puts recent returns in focus
Public Service Enterprise Group (PEG) released third quarter 2026 results that fell short of market expectations, with revenue and earnings per share coming in below consensus and both metrics declining compared with the prior year.
The earnings announcement arrived after a mixed stretch for PEG shares. The stock is up about 9% over the past month, but remains down roughly 3% over the past 3 months and about 8% year to date.
That mixed earnings print landed against a backdrop where Public Service Enterprise Group’s recent 30-day share price return of 9.14% contrasts with a weaker year to date pattern, and the 5 year total shareholder return of 41.33% points to momentum that has softened rather than strengthened in the near term as investors reassess earnings risk.
Scan beyond Public Service Enterprise Group’s earnings miss and compare it with other regulated utilities by reviewing our hand picked 43 power grid technology and infrastructure stocks in the sector.
Public Service Enterprise Group has just rallied after a weak quarter, which puts you at a fork in the road. You could lock in exposure after the bounce, or wait for a cleaner price given the earnings setback and the guidance reset that management has just outlined.
Most Popular Narrative: 9% Undervalued
On Simply Wall St’s most followed narrative, Public Service Enterprise Group screens as undervalued, with a fair value of $81.42 against a last close of $74.29, which puts the recent earnings wobble in a different light for anyone focused on the longer term story.
Policy and regulatory support for decarbonization and cleaner power supply, including PJM capacity revenues for the nuclear fleet and state level measures such as the Power New Jersey Act and the lifted moratorium on new nuclear development, provides a framework for Public Service Enterprise Group to keep earning capacity payments and potentially add new nuclear related projects that support revenue and margin stability.
See why 17 investors see Public Service Enterprise Group as 9% undervalued.
Result: Fair Value of $81.42 (UNDERVALUED)
Still, the narrative can crack if data center interest fails to convert into actual load, or if New Jersey policy shifts trim allowed returns and incentives.
Find out about the key risks to this Public Service Enterprise Group narrative.
Another View on Public Service Enterprise Group’s Valuation
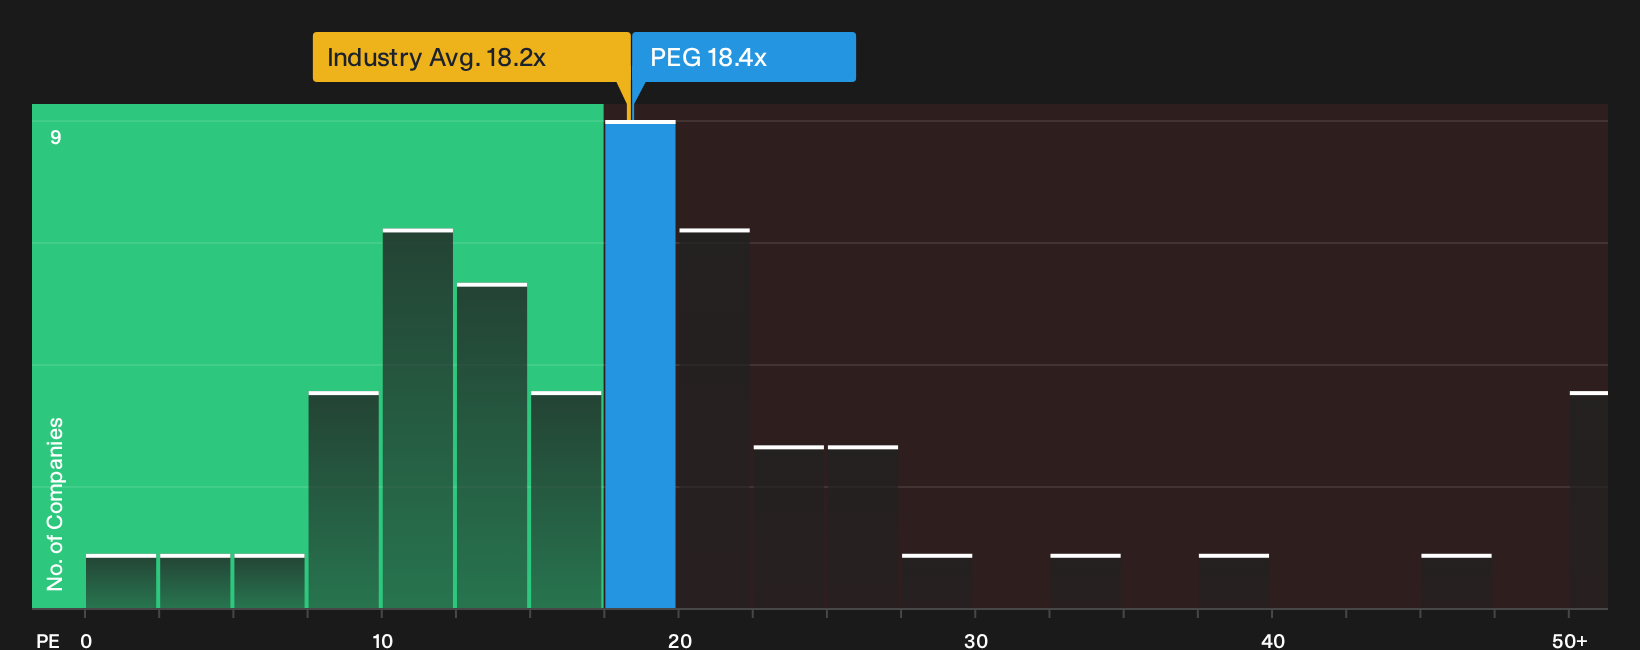
Most of the recent discussion around Public Service Enterprise Group leans on fair value estimates and analyst targets that point to undervaluation. The market, though, is putting a P/E of 18.4x on PEG, slightly above the global integrated utilities average of 18.2x, yet below a fair ratio of 20.9x. This hints at some built-in caution as well as potential re rating room.
That mix of a modest premium to the wider industry and a discount to the fair ratio frames the current price as neither obviously cheap nor stretched. The key question is whether you think the story eventually pulls the multiple toward peers or toward that higher fair ratio over time.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Public Service Enterprise Group can easily pull you in both directions, so step into the data now and stress test your own thesis with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Public Service Enterprise Group?
If Public Service Enterprise Group has sharpened your thinking, now is the moment to widen your watchlist and pressure test your approach across fresh opportunities.
- Spot potential mispricings early and compare valuations across sectors by scanning our hand picked 36 high quality undervalued stocks.
- Build a steadier income stream and assess yield against balance sheet strength by checking out the 5 dividend fortresses.
- Prioritise resilience and capital protection by reviewing companies in the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com