


EN
What Invesco (IVZ)'s Global Inflows Mean For Shareholders
- Invesco reported third quarter 2026 revenue of US$1,873.2 million, net income of US$331.5 million and continued portfolio tools development through its new Claude for Financial Advisors connector.
- The collaboration with Anthropic gives advisors direct access to Invesco model portfolio data and practice management research inside Claude, which could influence how clients experience advice and portfolio construction.
- We will examine how Invesco's investment narrative is affected by the global inflows and margin expansion highlighted in its latest results.
Scan how Invesco's AI and portfolio tooling push fits alongside other asset managers by checking which peers screen as 29 resilient stocks with low risk scores right now.
Invesco Investment Narrative Recap
To own Invesco, you need to believe the firm can keep shifting its mix toward scalable ETFs, models and solutions while holding the line on costs in a fee pressured industry. The latest quarter shows higher revenue year on year but slightly lower net income, so operating leverage still feels fragile. The key near term swing factor is whether global inflows stay broad based enough to offset pressure in higher fee active franchises.
The biggest risk remains margin compression as investors move to cheaper products, while digital competitors and regulation push up fixed costs. Recent AI tooling and platform investments, including the Claude connector, add execution risk if spending runs ahead of adoption. On balance, the October updates do not materially change that risk reward equation, but they do sharpen focus on efficiency and product mix.
The most relevant fresh data point for this story is the Q3 2026 earnings print. Invesco reported US$1,873.2 million of revenue and US$331.5 million in net income, with basic EPS from continuing operations of US$0.66. Those figures sit alongside management commentary about strong global inflows and wider operating margins supported by expense discipline.
For a shareholder, the question is how that earnings profile connects to the Claude for Financial Advisors rollout and wider technology agenda. Stronger margins give the group more room to fund AI tools, model portfolios and platform modernization without putting as much pressure on the dividend or balance sheet. If revenue mix keeps tilting toward ETFs, models and overseas flows, while earnings remain sensitive to fee pressure and regulation, execution on these tools becomes a practical catalyst rather than a side project.
Invesco's current analyst narrative projects US$7.9b of revenue and US$1.5b of earnings by 2029. That outlook assumes revenue growth of 4.6% per year and an earnings swing of about US$1.8b, from a current loss of US$309.2 million to the 2029 consensus level.
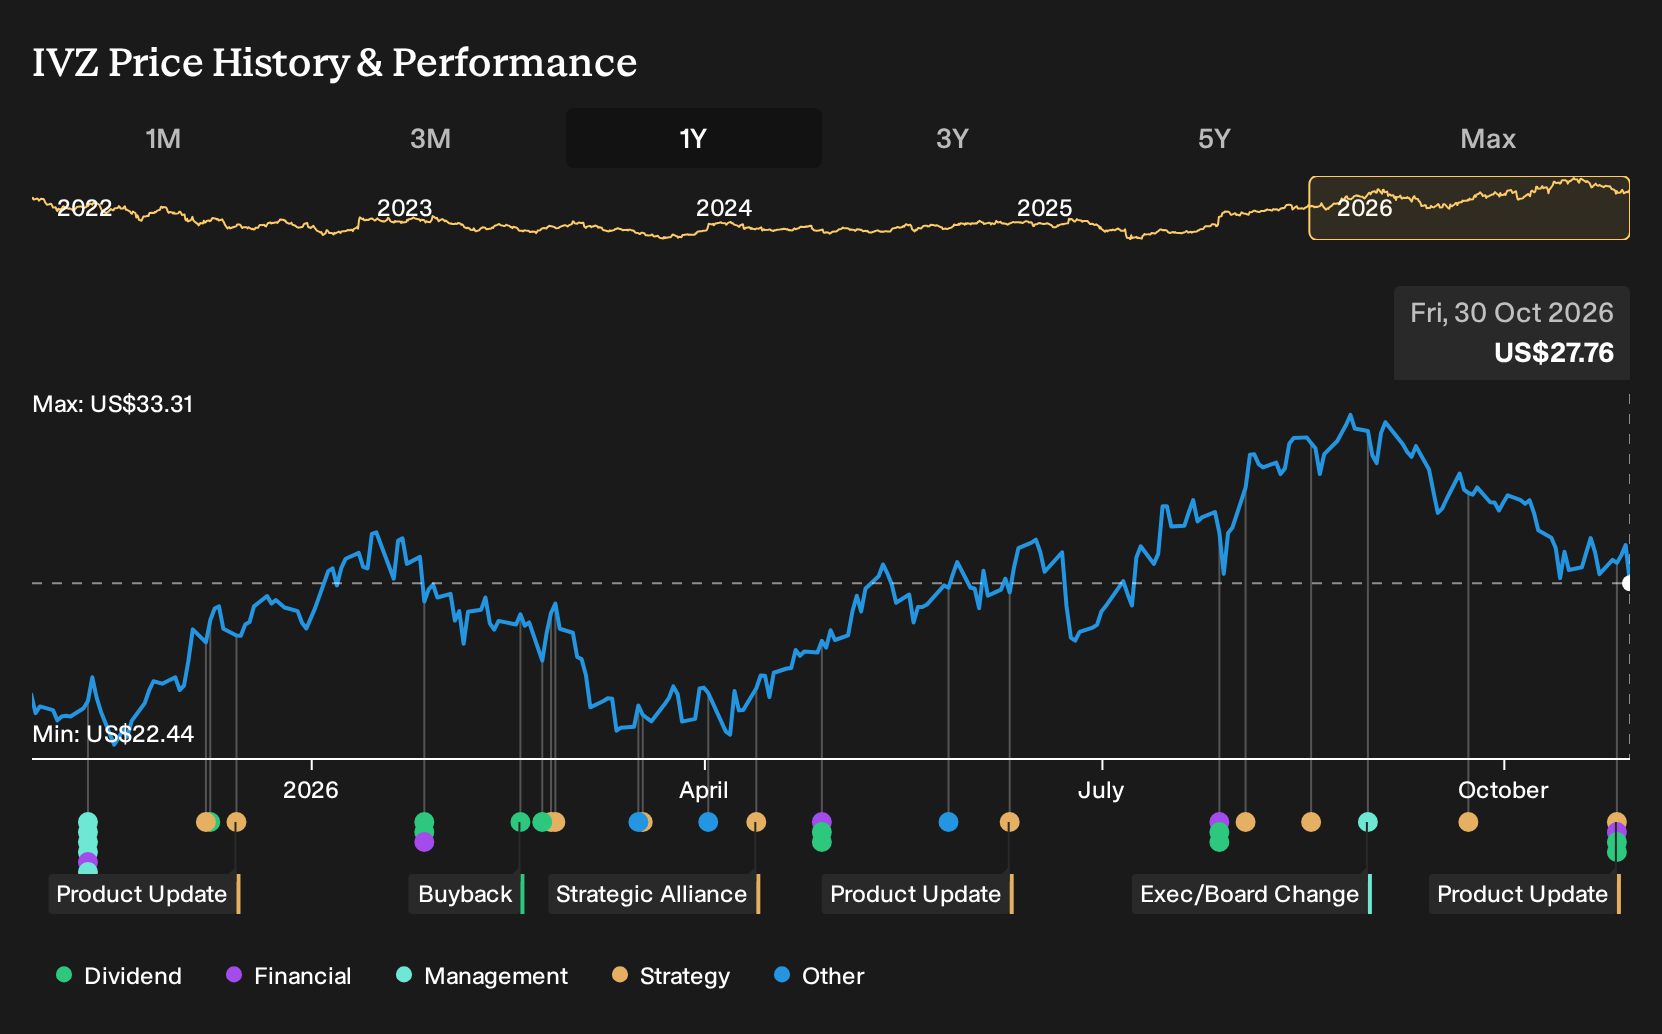
Uncover why Invesco's fair value indicates a 25% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view says the real risk for Invesco is that fee cuts and lower net revenue yield keep biting, even if tools like the Claude connector work well. The lowest analysts were pencilling in revenue of about US$6.0b and earnings of roughly US$1.7b by 2029. That is a far more cautious setup than consensus, and this fresh AI and earnings news could easily reshape both stories. Readers should explore both versions before deciding which feels closer to their own expectations.
Explore 3 other Invesco fair value estimates, including one that suggests it could be worth just $30.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Invesco research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Invesco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Invesco's overall financial health at a glance.
Looking for more investment ideas beyond Invesco?
If the Invesco story has sharpened your thinking and you want to pressure test that against other opportunities, the Simply Wall St Screener can help you scan for companies that better fit your return and risk preferences.
- If you want potential mispricings with solid fundamentals, start by checking a curated set of 36 high quality undervalued stocks that combine quality metrics with discounted prices.
- If resilience matters most to you, narrow your focus to a list of solid balance sheet and fundamentals (24 results) and see which businesses pair financial strength with consistent fundamentals.
- If you prefer to look where fewer investors are paying attention, scan through a 19 high quality undiscovered gems that may sit off the usual radar but still clear strict quality filters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com