


EN
How Store Expansion At Kroger (KR) Has Changed Its Investment Story
- Kroger has outlined plans to add about 110 new stores by 2029, roll out three refreshed formats, lean harder into fresh food, prepared meals, and online orders, and trim space for apparel and general merchandise.
- The shift toward ready to eat meals, lower everyday prices, simpler promotions, and heavier tech investment points to Kroger prioritizing food centric traffic and operational efficiency over peripheral categories.
- We will look at how Kroger's investment narrative is affected by the planned 110 store expansion and new fresh focused formats.
Scan how Kroger's fresh food push compares with peers by reviewing our curated list of solid balance sheet and fundamentals (24 results) for ideas that echo this focus on core grocery demand and resilience.
Kroger Investment Narrative Recap
Kroger appeals most if you think fresh food, private labels and digital ordering can keep pulling more spending into its ecosystem while cost savings protect margins. The fresh formats and 110 store buildout sit right on that thesis, yet the biggest near term swing factor remains whether e-commerce and retail media stay consistently profitable.
The live risk does not really change. A larger physical footprint, plus the planned Giant Eagle deal in 2027, still needs to earn its keep through solid traffic and basket sizes. Missteps on pricing accuracy, or diluted returns from new stores, could weigh on identical sales and squeeze already thin net margins.
Among recent moves, the most relevant to this store plan is Kroger’s push to keep e-commerce and retail media profitable after two quarters in the black. Fresh focused formats and more prepared meals are only as helpful as the digital channels that surface them and the advertising that monetises that traffic.
If that online and media profitability fades, the heavier capital spend on 110 new locations and remodels becomes harder to justify from an earnings perspective. If it holds, these stores give Kroger more points of pickup, more first party data and more scope to spread fixed technology and fulfilment costs across a wider base.
Kroger's current analyst narrative points to revenues of US$156.4b and earnings of US$3.2b by 2029, based on 1.6% yearly revenue growth and an earnings increase of about US$2.1b from US$1.1b today.
Uncover why Kroger's fair value is essentially aligned with its current price.
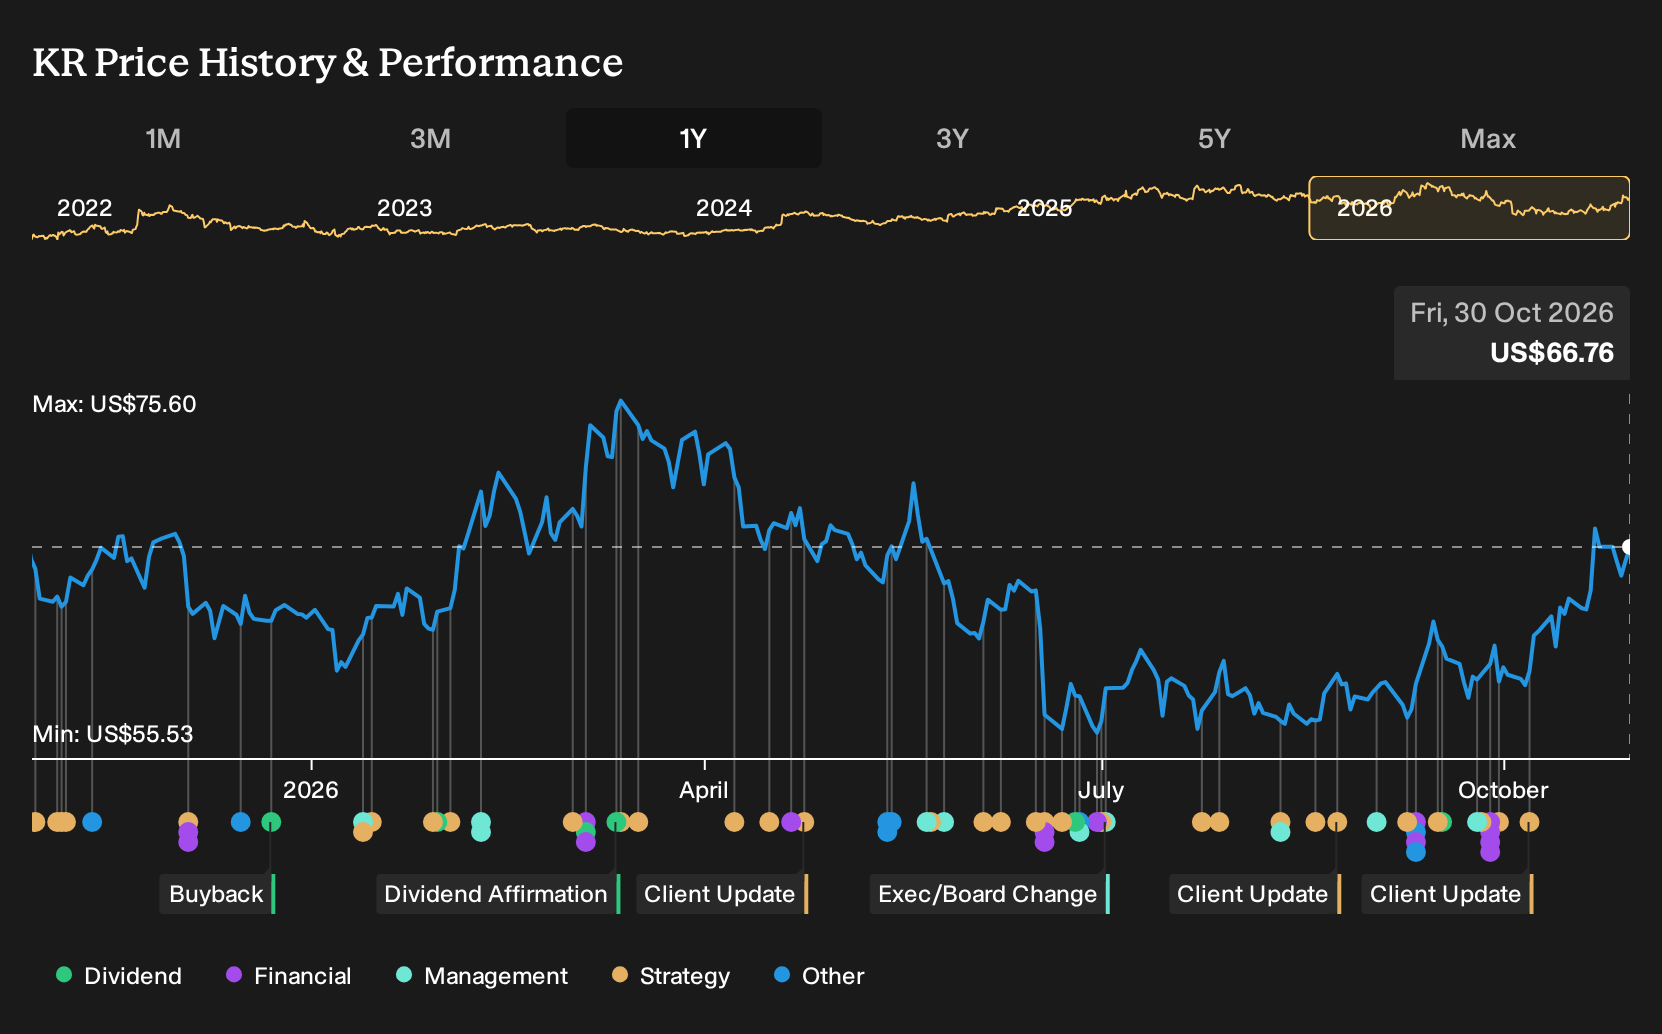
Exploring Other Perspectives
Some analysts look at Kroger’s capital heavy store expansion and see a risk that earnings stay closer to the bearish path, where revenue was previously penciled at about US$156.3b and earnings around US$2.7b by 2029. That is materially below the US$3.2b consensus path, so treat this fresh format news as a prompt to compare narratives before deciding what you think is realistic.
Explore 3 other Kroger fair value estimates, including one that suggests it could be worth just $68.14.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Kroger research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Kroger. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kroger's overall financial health at a glance.
Looking for more investment ideas beyond Kroger?
If this Kroger review sharpened your thinking about fresh focused retailers, you could broaden your watchlist with a few targeted stock lists built around different types of opportunity and risk.
- For investors who want a mix of quality and value, scan a 36 high quality undervalued stocks that might suit a long term, fundamentals first approach.
- If reliable balance sheets matter most to you, filter for companies on the list of solid balance sheet and fundamentals (24 results) that pair financial resilience with cleaner accounts.
- Income focused readers could weigh up a 5 dividend fortresses that aims to combine higher yields with businesses built to keep paying.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com