


EN
Why Netwealth Group Fell Even As Profit Rose
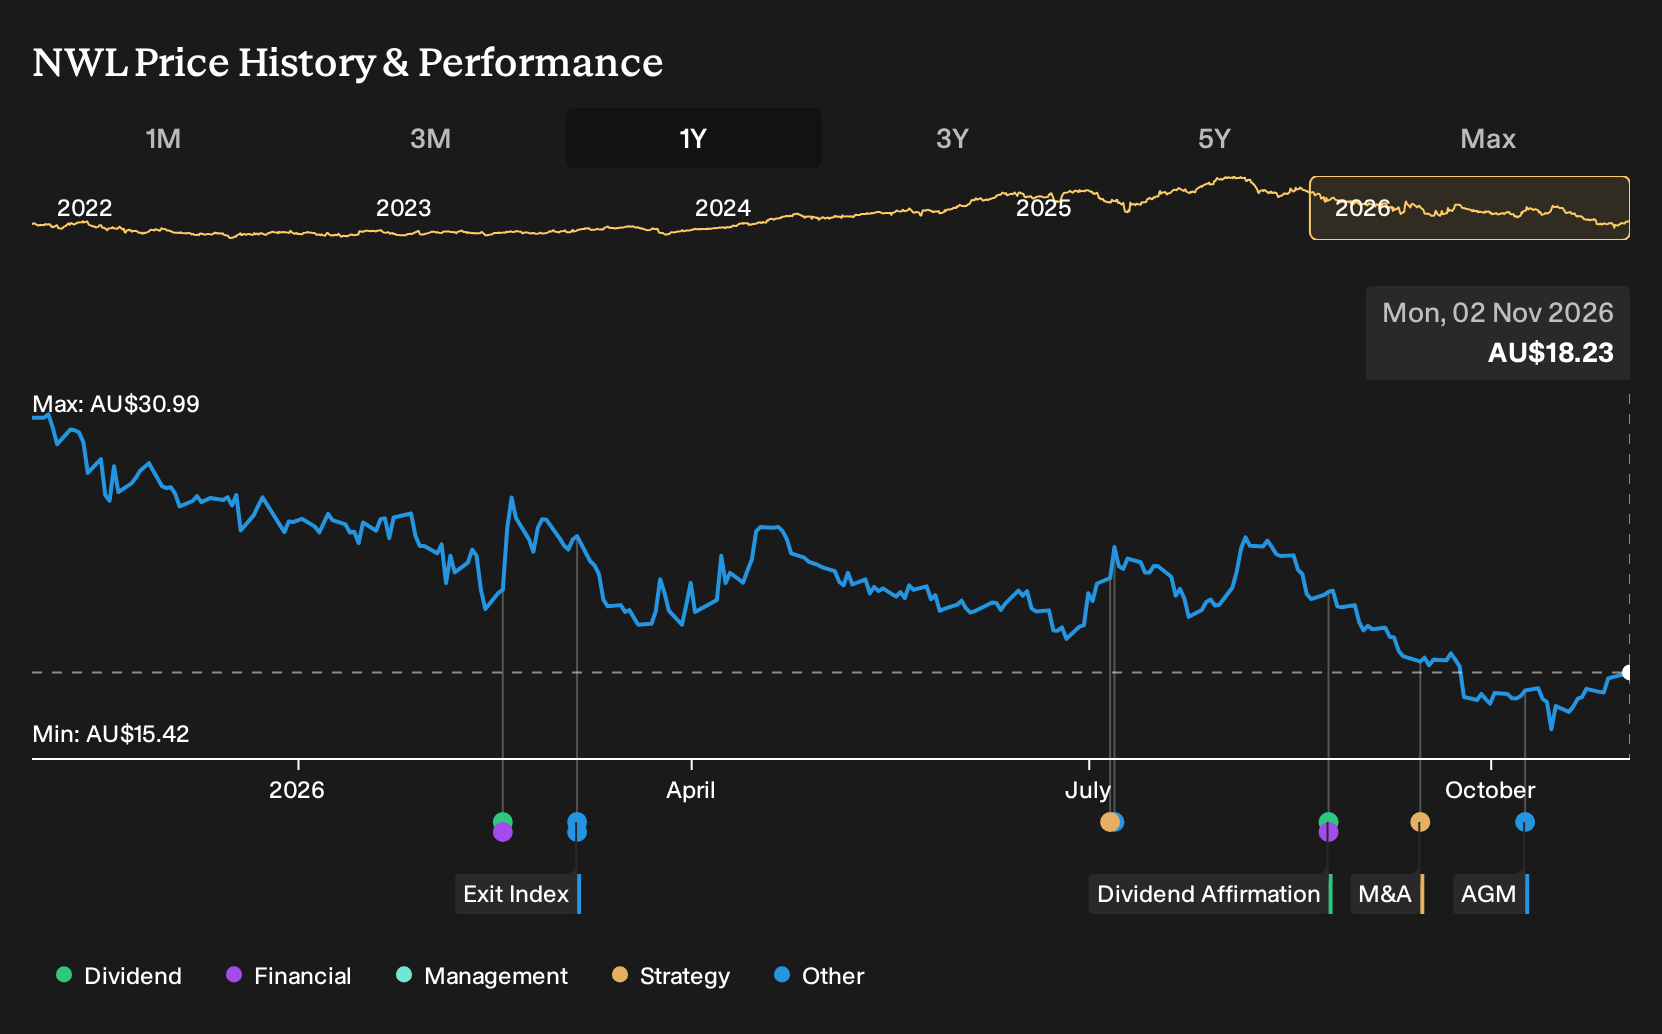
If you had looked at Netwealth Group in late 2025 and decided to sit it out while analysts argued over whether it was worth nearly double the most bearish target or only slightly above fair, the outcome over the next year might surprise you. Holding Netwealth Group over the past year would have meant a 39.7% loss, including dividends. If that decision were in front of you again, which assumptions on record at the time would you scrutinize most closely?
The easy part of this move is behind Netwealth Group. Zero in on 2 high quality undervalued stocks for companies trading below our estimates.
The Two Netwealth Group Stories Investors Were Arguing Over
The shares cost A$30.83 at the start of the period, and the debate around Netwealth Group hinged on which future investors considered more reasonable.
On the optimistic side, analysts pitched a Fair Value of A$32.98. This was a rough guide to what their assumptions implied the price could justify, built on revenue growth of 16.7% a year and profit margins at 36.2%.
The cautious view anchored to a Fair Value of A$15.20 and focused on rising compliance obligations and fee pressure that could erode margins even if revenue still grew.
What The Results Changed For The Netwealth Group Debate
Netwealth Group secured an expanded domestic platform solution for Morgan Stanley Wealth Management Australia, which supported the optimistic case that adviser relationships and technology investment could attract more funds under administration. Reported results showed revenue and net income higher in H2 2026 than H2 2025, yet the net margin slipped from 34.9% to 31.8%. The evidence cut both ways.
For future decisions, focus on which assumption really matters. For Netwealth Group, that was whether higher flows and new contracts translated into stable or rising net margins. When assessing another platform stock, track margin trends against any big partnership wins rather than assuming new mandates automatically support profitability.
What Today’s Netwealth Group Price Already Bakes In
Today Netwealth Group trades at A$18.23, and the selected Narrative’s Fair Value sits above that mark based on its own modelling and assumptions rather than any settled truth.
The Narrative leans on adviser focused technology, ancillary fee mix and current funds under administration. A buyer today would need to believe these ingredients can support durable margins even as regulatory and compliance costs keep rising.
"Continued investment by Netwealth Group in adviser focused technology, including AI tools such as the Nova chatbot that is already handling a meaningful share of adviser inquiries, can keep lifting adviser productivity per head and support higher revenue per account and adviser over time."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Looking Beyond Netwealth Group
Netwealth Group sits in the world of advice, platforms and account flows.
Every portfolio on a platform still has to move money through global pipes.
Cards, wallets and bank links quietly carry those instructions between counterparties.
One global network business earns a slice whenever those electronic payments clear and focuses on routing, security and extra services.
Where Netwealth Group wrestles with compliance and fee pressure, this other player leans on scale and software, leaving open how those rails evolve as payments digitise.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 18% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com