


EN
Ahead of Astera Labs Earnings, Here's What Barchart Data Says Comes Next for ALAB Stock
Astera Labs (ALAB) is scheduled to report its fiscal Q3 earnings on Nov. 3. Consensus is for the semiconductor firm to report $0.83 in earnings per share (EPS), up 219% on a year-over-year basis.
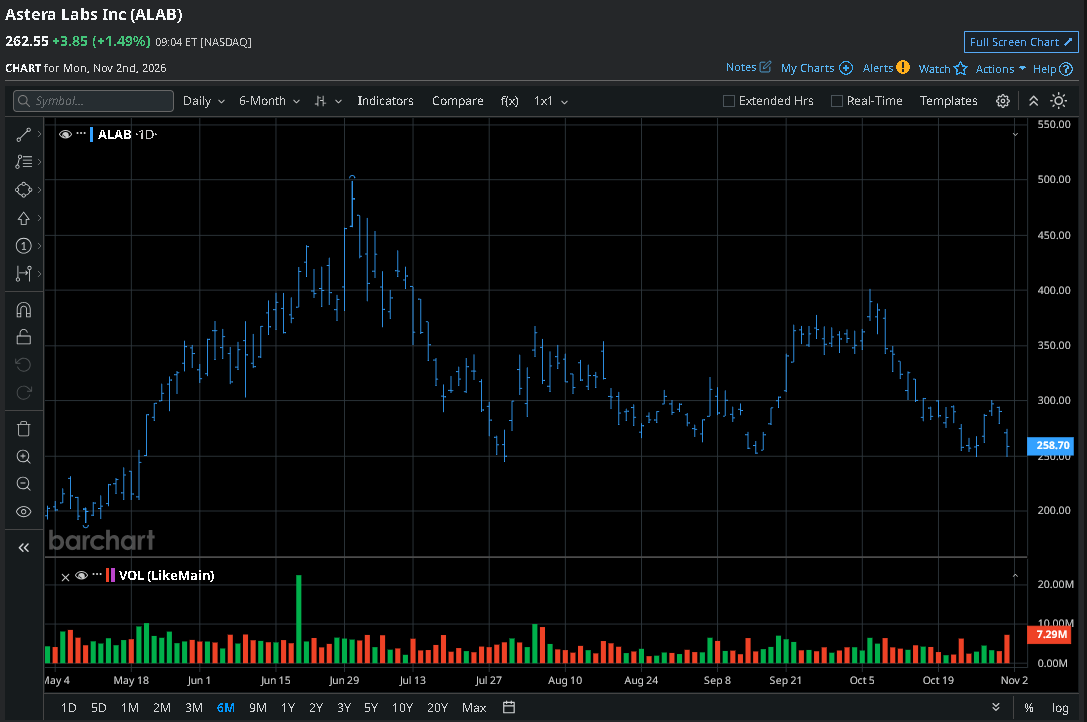
Heading into the quarterly release, ALAB shares are hovering around $260, which represents about a 47% discount to their YTD high in late June.
According to Barchart’s options data, though, some near-term recovery is likely after Astera Labs posts its third-quarter financial results on Tuesday.
Where Options Data Suggests Astera Labs Stock Is Headed
Options traders seem convinced that the recent selloff has already baked in much of the downside. A put-to-call ratio of 0.40x on contracts expiring Nov. 6 reflects the belief that 219% EPS growth will prove sufficient to trigger a near-term rally.
According to Barchart’s data, the upper price on those options contracts is set at nearly $291 as of writing, indicating potential for a more than 12% post-earnings surge.
That optimism isn’t particularly reflected in the technical setup, though. Astera Labs stock currently sits below its key moving averages (MAs), signaling bears are in control across multiple timeframes.
The Case for Owning ALAB Shares Heading Into 2027
Astera Labs strongest Q3 catalyst is its Scorpio fabric-switch business, which management expects to become its largest product family one quarter earlier than previously anticipated. That acceleration follows record quarterly revenue from Aries, suggesting growth extends across multiple product lines.
The investment case rests on a growing challenge for artificial intelligence (AI) infrastructure: moving data efficiently between increasingly powerful processors. ALAB’s connectivity portfolio addresses that bottleneck, giving investors exposure to spending beyond the processors themselves.
New customer design wins and expansion into optical interconnects and custom solutions provide additional growth opportunities. For buyers, evidence that these opportunities are translating into sustained orders would strengthen the case for an ALAB stock price recovery.
How Wall Street Recommends Playing Astera Labs
Wall Street analysts haven’t thrown in the towel on Astera Labs shares, either.
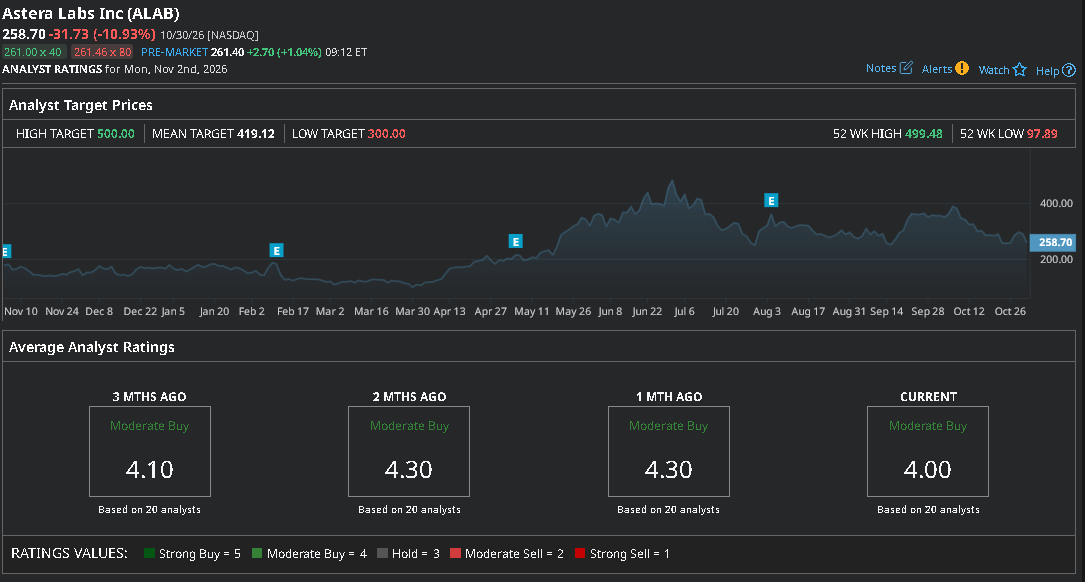
The consensus rating on ALAB remains at “Moderate Buy,” with the mean price target of about $419 indicating potential upside of more than 60% from here.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.