


EN
Worley (ASX:WOR) Nuclear Momentum Puts Valuation Back In Focus
Fresh commentary around Worley (ASX:WOR) has zeroed in on its nuclear work, with a 24% year-on-year uplift in the sales pipeline for design and decommissioning services drawing renewed attention from investors.
That renewed nuclear focus is landing against a mixed share price history for Worley, with the stock up over the past month but still showing a year to date share price decline of about 21% and a 1 year total shareholder return fall of roughly 27%. This signals improving short term momentum after a tougher recent period.
Scan beyond Worley and this single nuclear story by comparing it with 16 nuclear energy infrastructure stocks that could also be riding renewed interest in nuclear infrastructure and long-term project pipelines.
Worley shares have bounced in the past month while still trading below both analyst targets and one intrinsic value estimate. Where does a fair entry price really land in that gap?
Most Popular Narrative: 15% Undervalued
Against Worley’s last close at A$9.96, the most followed narrative anchors fair value at A$11.67, using a 10.14% discount rate to weigh future cash flows against current risks.
The accelerating global push for decarbonisation and energy transition is expanding Worley’s addressable market, and the current factored sales pipeline of future work is 24% higher year-on-year with more than $10b of recent wins in areas such as LNG, power and energy transition materials, which can support future revenue and backlog growth.
See why 36 investors see Worley as 15% undervalued.
Result: Fair Value of A$11.67 (UNDERVALUED)
Still, the Worley story depends on delayed Middle East project awards improving, and on weakness in the chemicals sector not dragging backlog and earnings visibility for longer.
Find out about the key risks to this Worley narrative.
Another View: Worley Through The P/E Lens
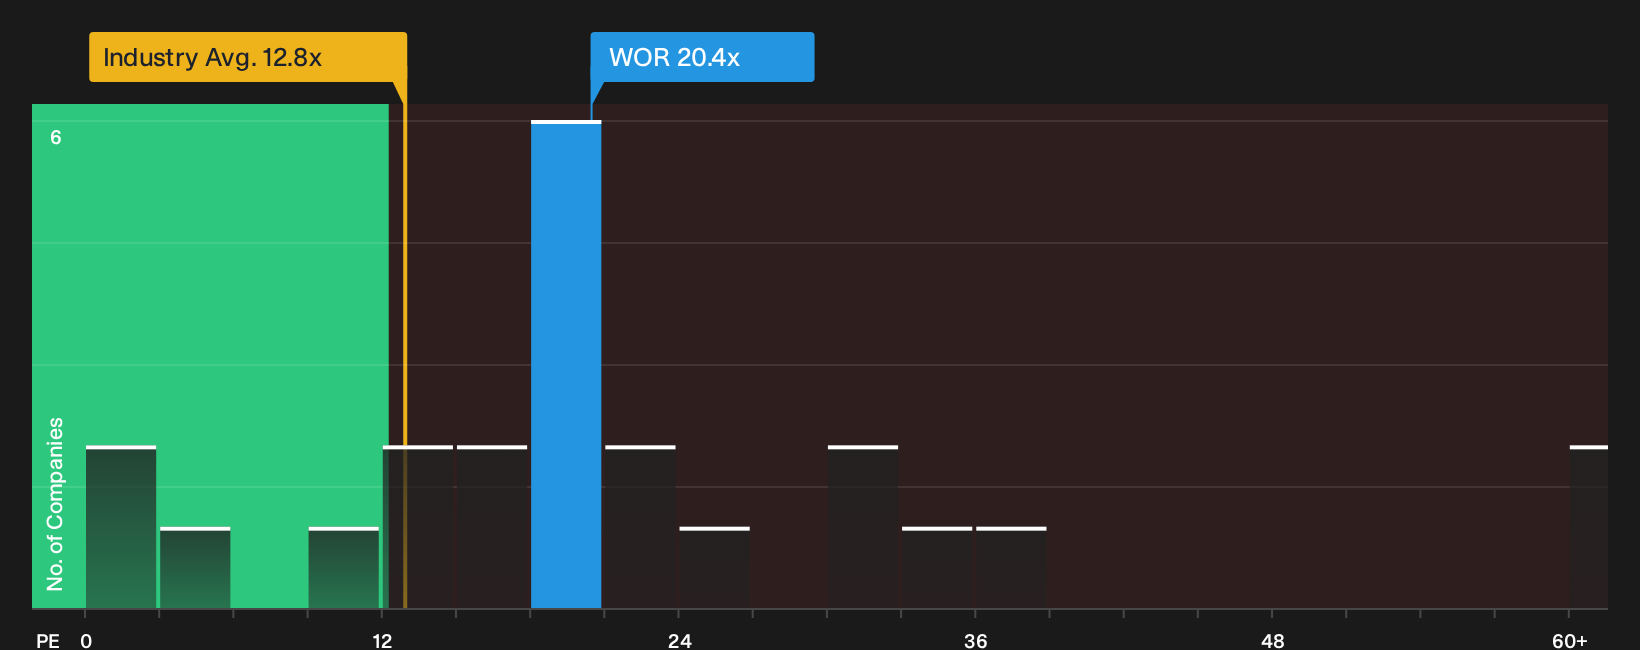
Step away from fair value models for a moment and look at Worley through its P/E. The stock trades around 20.4x earnings, a touch higher than peer averages at 20x and well above the global construction group on 12.8x, while the fair ratio sits higher again at 23.3x.
This mix means investors are paying more than the wider industry today, yet the fair ratio suggests the market could still shift toward a richer multiple over time. Is that a pricing cushion or extra valuation risk if sentiment cools?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the mixed signals around Worley tilt more positive or negative right now? Take a moment to weigh the data for yourself, then check the full balance of 2 key rewards and 2 important warning signs
Looking For More Investment Ideas Beyond Worley?
If Worley has your attention but you want a broader watchlist, use the Simply Wall St screener to identify other opportunities before the crowd does.
Explore these tailored stock ideas and compare how their fundamentals stack up against Worley, then build a short list that fits your own approach.
- Target value and quality by reviewing companies highlighted in the 2 high quality undervalued stocks that combine solid balance sheets with appealing valuations.
- Find income-focused opportunities by checking out the 4 dividend fortresses that feature higher yields supported by robust financial profiles.
- Manage portfolio risk by focusing on the 6 resilient stocks with low risk scores that emphasize resilient businesses with fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com