


EN
Teleflex (TFX) Could Be 11% Undervalued Following FDA Breakthrough Device Designation
FDA Breakthrough Device Designation sparks fresh focus on Teleflex
Teleflex (TFX) drew new attention after the FDA granted Breakthrough Device Designation to its Freesolve Resorbable Magnesium Scaffold for percutaneous coronary intervention, highlighting an attempt to address unmet cardiovascular treatment needs.
Teleflex shares trade at US$139.77 after a 12.61% 30 day share price return and a 14.19% gain year to date. The 1 year total shareholder return of 15.04% contrasts with a 3 year total shareholder return decline of 32.59% and a 5 year decline of 58.82%. This suggests that recent momentum has picked up against a weaker longer term record as investors weigh the Breakthrough Device news alongside past performance.
Scan beyond Teleflex and see how this kind of cardiology catalyst compares with other hand picked medical stocks in the list of solid balance sheet and fundamentals (24 results).
Bulls point to Teleflex's breakthrough device and valuation discount, while bears focus on the recent loss and long stretch of weak total returns. Which story do the current numbers support?
Most Popular Narrative: 10% Undervalued
The most followed narrative values Teleflex at $154.73 per share, above the last close of $139.77. This frames the current price as a discount that hinges on execution in margins, R&D and capital returns.
The multiyear restructuring program that targets about US$50 million in annual pretax cost savings by mid 2028, combined with plans to offset roughly US$90 million of stranded costs and move steady state adjusted operating margin from about 19% toward roughly 23%, provides a clear path to higher operating margins.
The integration work on the BIOTRONIK Vascular Intervention acquisition, including order to cash and sales channel adjustments that have weighed on current Interventional revenue guidance, still offers upside potential if Teleflex restores growth in these coronary and peripheral products and lifts both segment revenue and overall operating margin.
See why 8 investors see Teleflex as 10% undervalued.
Result: Fair Value of $154.73 (UNDERVALUED)
Still, if BIOTRONIK integration drags on or the planned stranded cost offsets and restructuring savings fall short, the Teleflex margin and valuation story could look very different.
Find out about the key risks to this Teleflex narrative.
Another View: Teleflex Through a Sales Multiple Lens
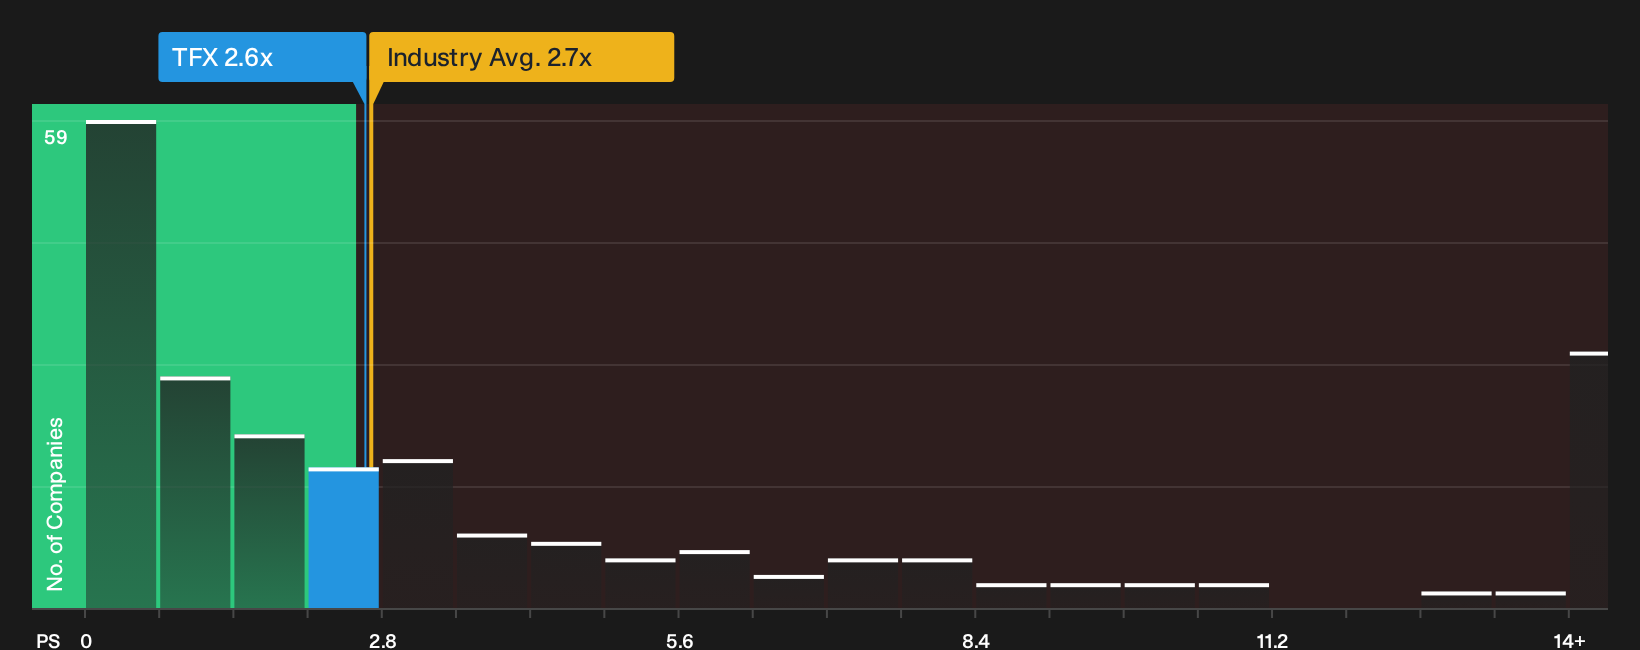
The SWS DCF model points to upside for Teleflex, yet the price tag on current sales tells a different story. At a P/S of 2.6x, the stock is slightly cheaper than the US Medical Equipment industry on 2.7x, but above the SWS fair ratio of 2.2x. That gap suggests investors are still paying a premium to the fair ratio even while the shares screen as cheap on cash flow. How comfortable are you with that trade off?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the data can cut both ways, so if Teleflex looks intriguing or concerning, consider acting while this FDA catalyst is fresh and carefully weigh the 2 key rewards and 1 important warning sign
Looking for more Teleflex sized investment ideas?
If Teleflex has your attention, do not stop here. Use this momentum to refresh your watchlist with fresh ideas that match your risk and return preferences.
- Target potential mispricing by scanning a focused pool of companies that screen as attractively valued in the 36 high quality undervalued stocks.
- Strengthen your income stream by hunting for reliable high yield opportunities highlighted in the 5 dividend fortresses.
- Lock in peace of mind by filtering for financially robust businesses through the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com