


EN
Burke & Herbert Financial Services (BHRB) Could Be 1% Below Fair Value After Mixed Earnings
Burke & Herbert Financial Services earnings spark mixed reaction
Burke & Herbert Financial Services (BHRB) drew fresh attention after its third quarter report paired higher net interest income and net income with lower earnings per share and a sharp rise in net loan charge offs.
The third quarter update and fresh dividend declaration landed against a share price that has eased 5.57% over the past 90 days but still shows a 14.10% year to date share price return and a 22.99% total shareholder return over 1 year, suggesting that longer term momentum remains intact even as near term sentiment cools around credit risk and earnings per share pressure.
Compare how Burke & Herbert Financial Services stacks up against other regional lenders facing similar credit trends by reviewing our hand picked list of solid balance sheet and fundamentals (24 results)
Burke & Herbert Financial Services now trades only modestly below both its estimated intrinsic value and the analyst target, even after the recent wobble on credit costs. Is that discount a sign of caution or an opportunity?
Price-to-Earnings of 13.9x: Is it justified for Burke & Herbert Financial Services?
Burke & Herbert Financial Services trades on a P/E of 13.9x, which sits slightly above both its peer group on 13.7x and the broader US Banks industry on 11.3x, even though the stock is only 1.4% below an estimated intrinsic value of $71.50 and modestly below an $80 analyst target.
The P/E ratio compares the current share price with earnings per share and helps you gauge how much investors are paying for each dollar of profit. For a lender like Burke & Herbert Financial Services, that yardstick often reflects expectations around credit quality, loan growth and the durability of fee and interest income.
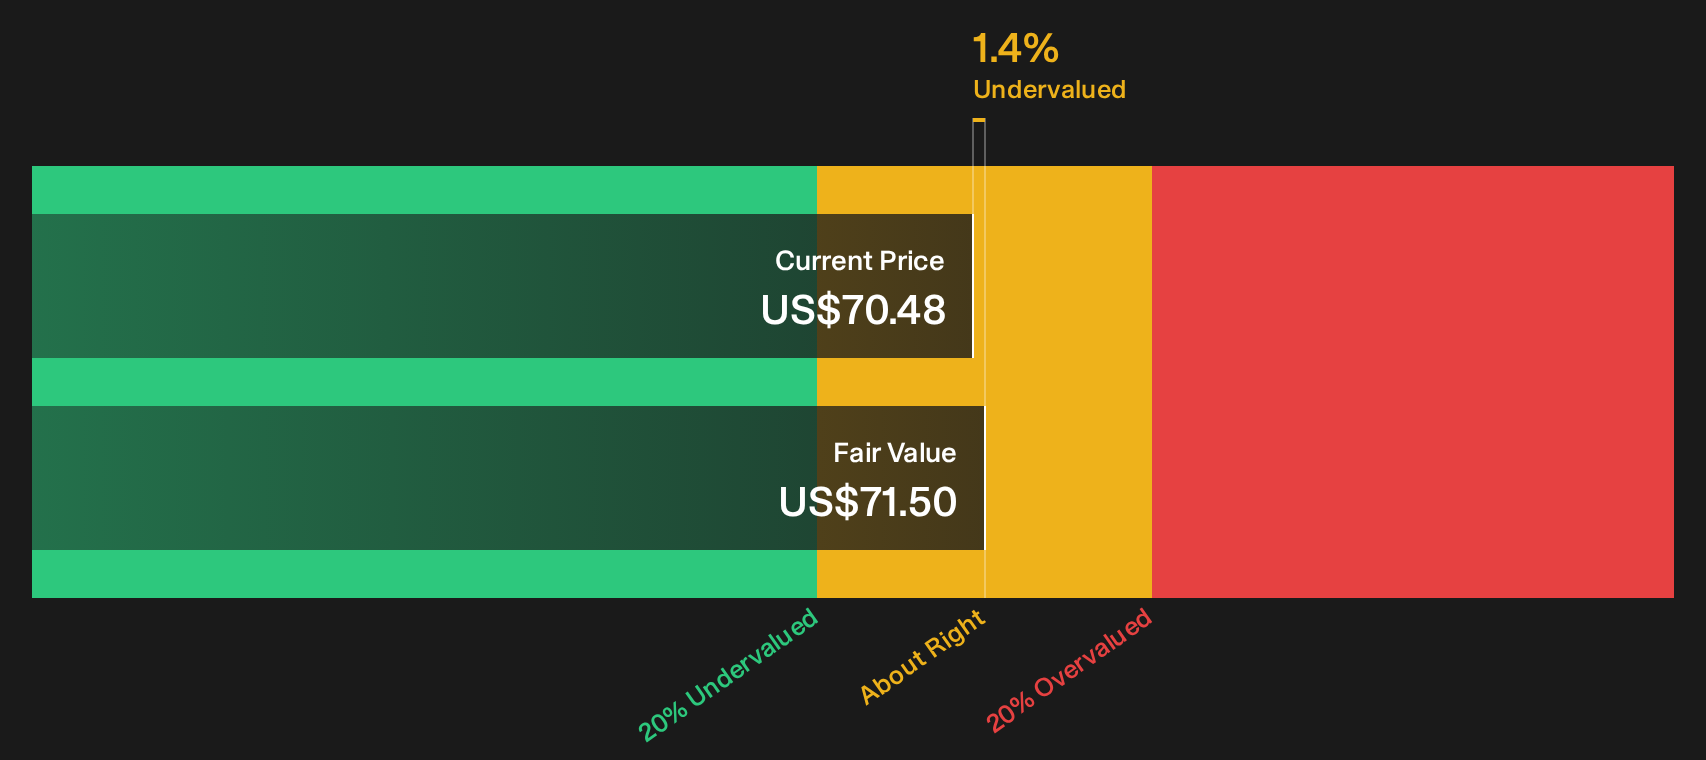
Here the picture is mixed. The SWS DCF model suggests BHRB at $70.48 sits just under the projected future cash flow value of $71.50, which indicates only a small discount on a cash flow basis. Yet the current P/E of 13.9x is above the US Banks average of 11.3x, while also below an estimated fair P/E of 15.9x. That combination implies the market is paying a premium to the typical bank, but still leaving room for the valuation multiple to move closer to that higher fair ratio level if earnings and dividend delivery match expectations.
Against direct peers, the 13.9x P/E is only fractionally higher than the 13.7x group average, so the premium within that tighter comparison set is very small. The stronger 1 year and multi year total returns relative to both the US Banks industry and the wider US market align with this slightly richer earnings multiple, even as recent dilution and increased loan losses keep some investors cautious around how much more they are willing to pay.
Explore the SWS fair ratio for Burke & Herbert Financial Services.
Result: Price-to-Earnings of 13.9x (ABOUT RIGHT)
Still, higher net loan charge offs and recent dilution leave Burke & Herbert Financial Services exposed if credit conditions tighten or earnings per share trends soften further.
Find out about the key risks to this Burke & Herbert Financial Services narrative.
Another view on Burke & Herbert Financial Services valuation
The earnings multiple paints one picture, yet the SWS DCF model adds a slightly different angle. On that cash flow view, Burke & Herbert Financial Services at $70.48 is only 1.4% below an estimated future value of $71.50, so the stock appears closer to fairly priced than deeply misjudged. If earnings forecasts stay on track, does that slim gap feel like enough of a margin for you?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Burke & Herbert Financial Services for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Burke & Herbert Financial Services can tempt you to lean hard in one direction. Instead, move quickly, review the full picture of both caution and optimism, and ground your call on the 3 key rewards and 3 important warning signs.
Looking for more Burke & Herbert Financial Services style ideas?
Do not stop with Burke & Herbert Financial Services. A few minutes with targeted screeners can surface other opportunities that fit your risk, income, and value preferences.
- Target resilient balance sheets that may handle stress better by reviewing our hand picked list of solid balance sheet and fundamentals (24 results).
- Hunt for quality at a discount by scanning companies on our data driven 36 high quality undervalued stocks.
- Build a cash flow focused watchlist by zeroing in on income ideas using our curated 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com