


EN
How Raised Earnings Guidance Will Impact OGE Energy (OGE) Investors
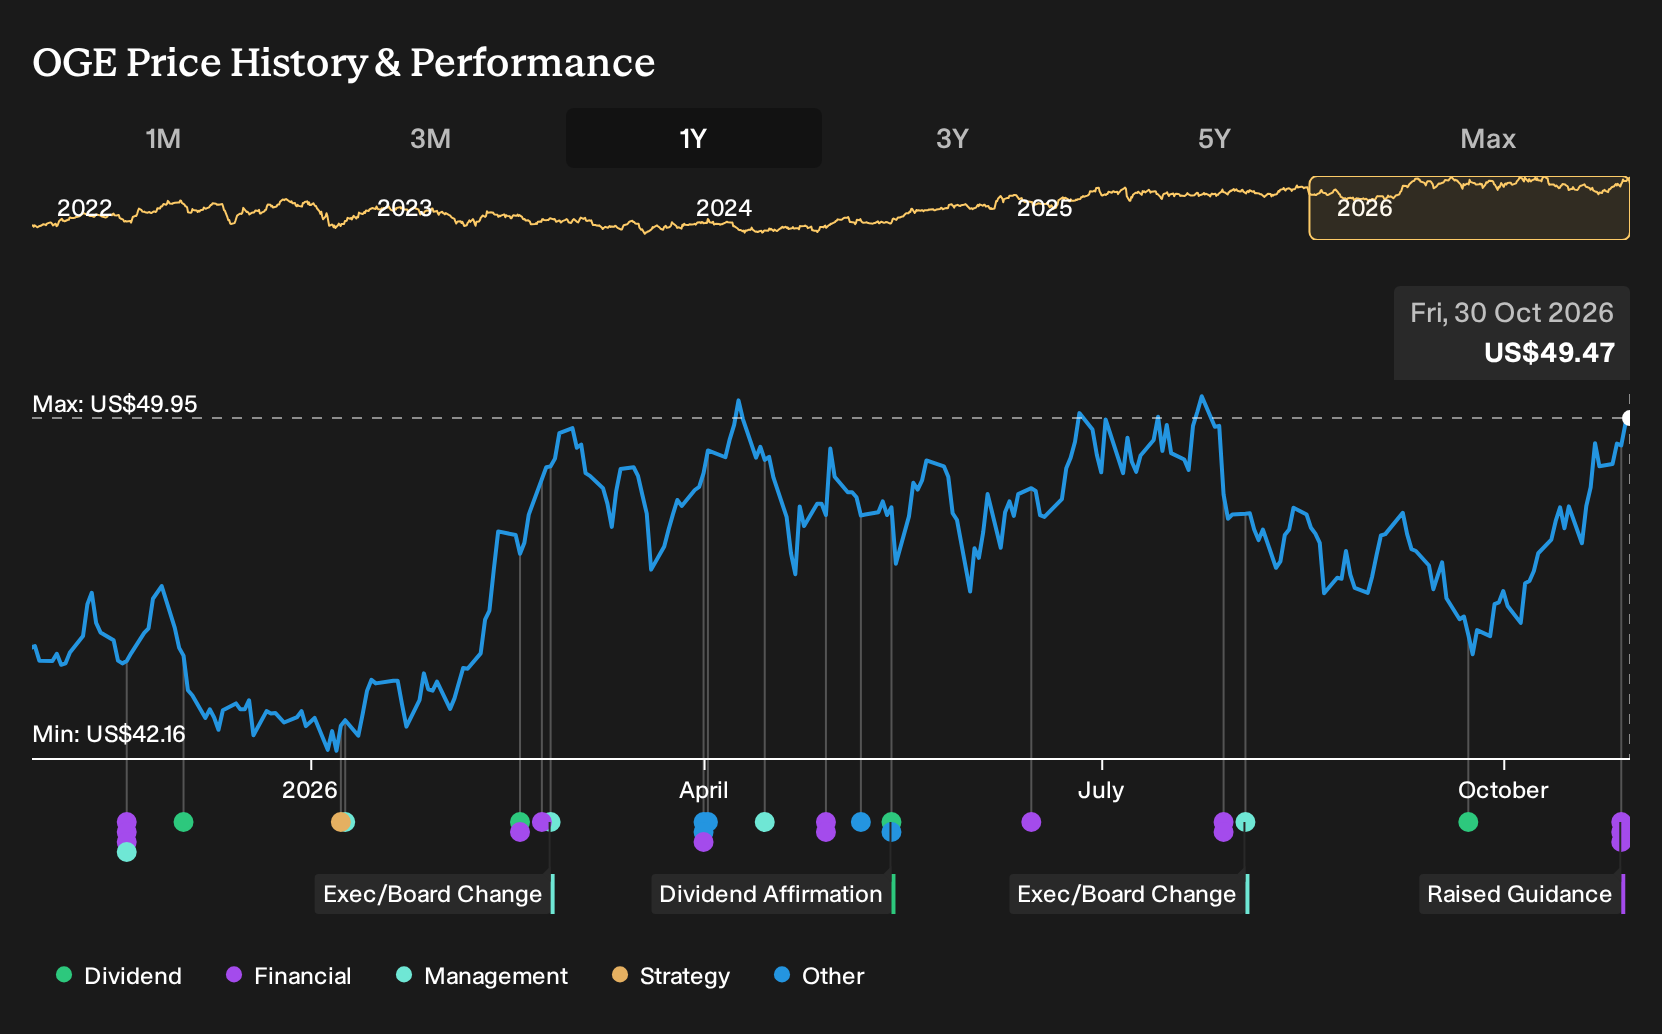
- OGE Energy raised its 2026 consolidated earnings guidance to US$2.62 to US$2.68 per diluted share after warmer than normal weather supported stronger than expected results, alongside reporting higher third quarter and nine month sales, revenue, and net income compared with a year earlier.
- The company paired this upgraded outlook and improved earnings per share with a US$750 million at the market equity offering. This signals a focus on funding its capital plans while managing balance sheet needs through additional common stock issuance.
- Next comes a look at how OGE Energy's higher 2026 earnings guidance could reshape the existing investment narrative around capital growth.
Scan how OGE Energy's guidance shift compares with other grid and power plays by reviewing the hand picked 42 power grid technology and infrastructure stocks in the same corner of the market.
OGE Energy Investment Narrative Recap
To own OGE Energy, you need to be comfortable with a regulated utility that leans on long term capital spending and large load customers such as data centers. The raised 2026 earnings guidance leans on recent weather benefits, so it does not fundamentally change the story. However, it does show the business handling current demand well.
The near term swing factor remains execution on the multi year build program and timely cost recovery with regulators. The biggest risk still sits in project approvals, legal disputes and any prolonged softness in industrial and oilfield usage, which could offset data center and large load wins if those segments stay weak.
The 2026 earnings outlook revision is the hinge point for this update because it ties directly into how you think about near term execution risk. Management is now pointing to consolidated earnings of US$2.62 to US$2.68 per diluted share for 2026, assuming normal weather for the rest of the year.
This guidance interacts directly with the planned US$7.3b capital program and the US$750 million at the market equity offering. Higher projected earnings can help support funding flexibility. At the same time, the extra equity issuance still matters for dilution, returns and the firm’s ability to keep financing costs and debt levels aligned with its targeted FFO to debt ratio.
What The Long Term OGE Energy Forecasts Assume
OGE Energy's longer range analyst narrative rests on a clear set of building blocks that tie near term guidance to where earnings could land by the end of the decade. The focus is on how fast revenue is expected to climb, how much profit conversion might improve, and what that combination implies for future earnings power.
Consensus expectations point to revenue growing at 7.5% a year over the next three years, with profit margins modeled to move from 14.4% today to 15.8% by around 2029. Analysts currently frame earnings today at about US$467.0 million and are projecting US$636.6 million of profit, or US$2.96 per share, by 2029, with more cautious views closer to US$569.8 million.
That shift from US$467.0 million to US$636.6 million implies an earnings increase of roughly US$169.6 million over the forecast window. This is before considering the effect of share count growth of about 2.54% annually that could dilute per share outcomes. For readers tracking OGE Energy closely, this forecast earnings bridge is as important as the top line growth rate, because it underpins both the 2026 guidance debate and the longer term capital plan.
On the valuation side, analysts are tying these operating assumptions to a 2029 revenue marker of about US$4.0b and the same US$636.6 million earnings figure, paired with a P/E of 21.2x. This compares with an implied current P/E around 20.7x and an industry level near 20.5x. In other words, the outlook assumes OGE Energy commands a modestly richer multiple in future if the thesis holds together.
The current analyst consensus price target of US$49.17 sits only about 5.0% above the recent share price of US$46.72, with published targets spread between US$44.0 and US$54.0. That relatively tight gap suggests analysts as a group see OGE Energy as roughly in line with their modeled fair value. This puts more attention on how readers judge the 7.5% annual revenue growth path, the margin lift, and the capital execution risks discussed earlier.
OGE Energy's narrative projects US$4.0b revenue and US$636.6 million earnings by 2029. This requires 7.5% yearly revenue growth and an earnings increase of about US$169.6 million from US$467.0 million today.
Uncover why OGE Energy's fair value is essentially in line with its current price.
Exploring Other Perspectives
Fair value guesses from three Simply Wall St Community members range from about US$36 to more than US$101,000, showing how widely private forecasts on OGE Energy can diverge. You are weighing those views against fresh 2026 guidance, the US$7.3b capital plan and the US$750 million equity raise, so it helps to browse several competing angles before deciding how convincing the story feels.
Explore 2 other OGE Energy fair value estimates, including one that suggests as much as 205066% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your OGE Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for OGE Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OGE Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond OGE Energy?
If OGE Energy helps you frame what a regulated utility story can look like, it often pays to widen the lens and compare it with other companies that fit different risk and income profiles. The Simply Wall St Screener can surface a wide range of stocks that match your preferences so you can stress test your thesis and avoid anchoring on a single ticker.
- If you want potential value with quality fundamentals, scan a curated 36 high quality undervalued stocks that already screen for strong cash generation and balance sheets.
- If capital preservation and steadier profiles matter more to you, filter for 29 resilient stocks with low risk scores that score well on resilience and financial strength.
- If you are hunting for under followed stories, cast a wider net across 19 high quality undiscovered gems that combine solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com