


EN
WESCO International (WCC) Dropped, So What Is Behind the Attention Now?
WESCO International (WCC) is back in focus after reporting third quarter 2026 results alongside fresh guidance, with data center demand, higher earnings and an upgraded full year outlook driving renewed investor attention.
The raised outlook and record third quarter have arrived in a volatile tape. WESCO International’s share price fell 6.44% on the day to US$343.11 and is down 10.12% over the past month. However, the year-to-date share price return is 36.09% and the five-year total shareholder return is 160.86%, suggesting long-term holders have still seen strong compounding even as near-term momentum cools.
Capitalize on the data center momentum around WESCO International by scanning a curated set of infrastructure-focused opportunities in our 42 power grid technology and infrastructure stocks.After a record quarter, an upgraded 2026 outlook, and a pullback that leaves WESCO International well off recent highs, the puzzle for investors now is whether the current price still compensates for the risks ahead.
Most Popular Narrative: 16% Undervalued
The dominant narrative around WESCO International pegs fair value at about $407.73, above the last close at $343.11. This puts the recent pullback in a very different light when stacked against long dated project visibility and data center exposure.
Power intensive AI and cloud data centers are a growing share of customer projects, and WESCO International now sells across the full data center life cycle through its Power to Compute model and recent Newark Engineering acquisition. This can influence revenue growth and support EBITDA margins through higher value solutions and services.
See why 1 investors see WESCO International as 16% undervalued.
Result: Fair Value of $407.73 (UNDERVALUED)
Still, the bullish WESCO International story leans on ongoing AI data center build outs and large grid projects, so any slowdown or project delays could quickly challenge that optimism.
Find out about the key risks to this WESCO International narrative.
Another View: What WESCO International’s P/E Is Telling You
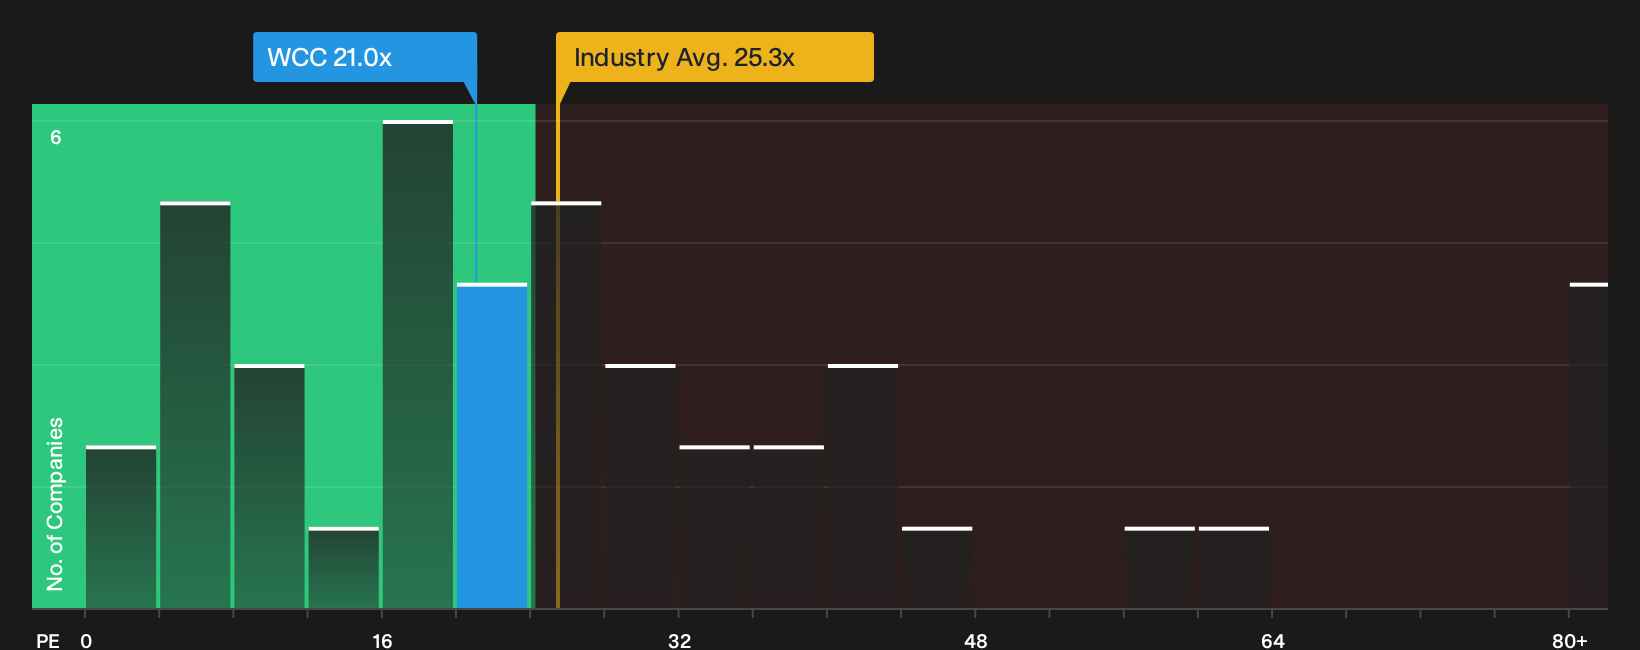
On the flip side of that fair value story, WESCO International trades on a P/E of about 21x, which is richer than peers at 19.4x but below the US Trade Distributors sector on 25.3x and under a fair ratio of 27.6x that the market could eventually lean toward. That mix of premium to direct competitors yet discount to the broader industry and fair ratio raises a simple question for investors: Is the current multiple a cushion or a warning sign if expectations reset.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in the WESCO International story so far. If you want to move quickly and build your own view from the ground up, start by weighing the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond WESCO International?
Do not stop your research with WESCO International. A few minutes with the right screeners can surface opportunities you might regret missing later.
- Target durable businesses with financial cushions by running a list of solid balance sheet and fundamentals (24 results) that can help you stress test ideas before committing real money.
- Hunt for value where quality and price still meet by scanning our 19 high quality undiscovered gems before they attract wider market attention.
- Stack your portfolio toward resilience by filtering for 29 resilient stocks with low risk scores that may help smooth returns when sentiment swings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com