


EN
How Investors May Respond To Jeronimo Martins Stock As Earnings Weaken
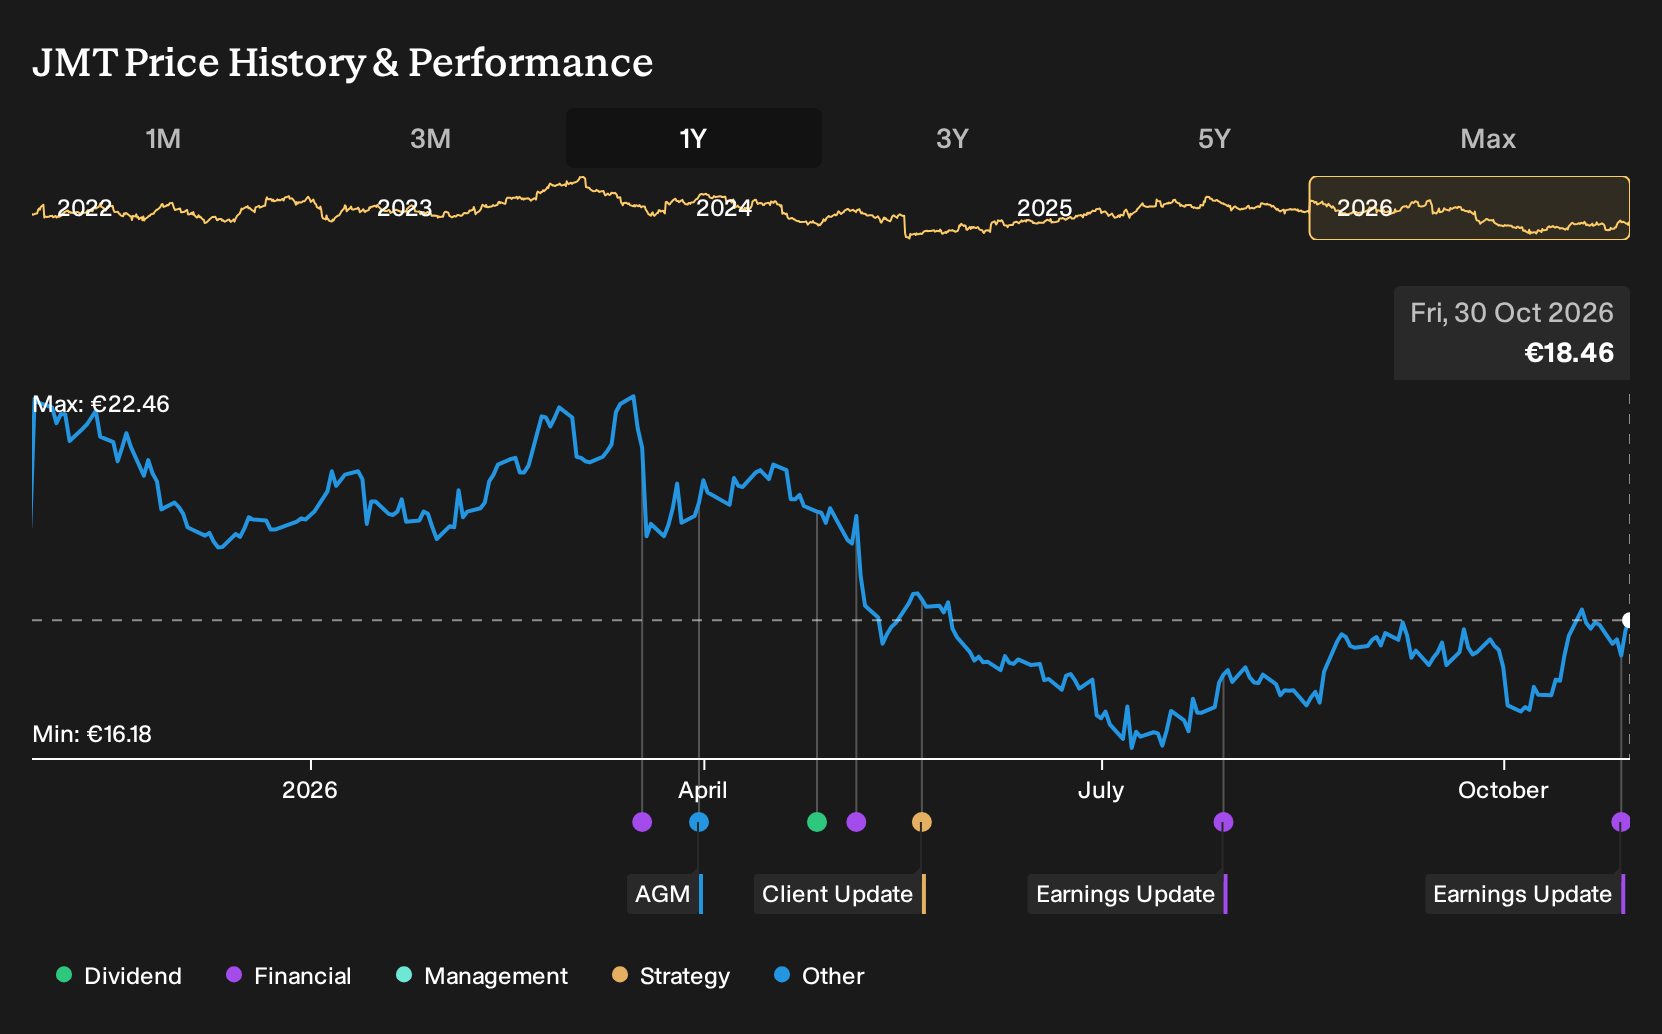
- Jerónimo Martins SGPS reported third quarter 2026 sales of €9,533 million and net income of €154 million, with nine month sales of €27,815 million and net income of €414 million, alongside lower basic earnings per share than a year earlier.
- The combination of higher sales and reduced earnings suggests cost pressures or mix effects are weighing on profitability, even as the retail footprint continues to generate more revenue.
- We will now look at how the Jerónimo Martins SGPS investment narrative is affected by higher sales alongside weaker earnings and earnings per share.
Compare Jerónimo Martins SGPS with other retailers facing similar margin pressure and find ideas with sturdier profitability profiles using our hand picked list of solid balance sheet and fundamentals (197 results).
Jerónimo Martins SGPS Investment Narrative Recap
To own Jerónimo Martins SGPS, you need to be comfortable with a value focused food retailer that leans on volume, tight cost control and heavy store investment rather than rich margins. The latest quarter fits that story. Sales moved higher while profit and earnings per share softened, which keeps the spotlight on operating costs and pricing discipline.
The key short term swing factor is whether ongoing efficiency programs can limit wage and logistics pressure without dulling the price appeal at Biedronka, Ara and Pingo Doce. The main risk is that labor and promotion heavy markets, especially Poland, keep eroding margins faster than store expansion and process improvements can offset.
The third quarter 2026 earnings release is the clearest operational signal right now. Jerónimo Martins SGPS reported €9,533 million of sales and €154 million of net income for the quarter, with nine month sales of €27,815 million and profit of €414 million. Earnings per share were lower than a year earlier, which puts more focus on unit economics than on sheer scale.
For catalysts, that same update ties directly into the ongoing capex and efficiency narrative. Management is still funding new stores and logistics capacity, and programs to tighten store processes are intended to support EBITDA margins over time. Against that, recent periods of weaker cash generation and high annual capex around €1.2b leave less room if trading conditions soften further.
What The Current Jerónimo Martins SGPS Forecasts Assume
Analyst models anchor the Jerónimo Martins SGPS story in steady top line expansion and a modest lift in profitability rather than a dramatic reset. Consensus points to revenue growing by 6.1% each year over the next few years, with profit margins moving from 1.7% today to 2.1% by around 2029 as efficiency work and mix shift are expected to add some support to the bottom line.
On earnings, the group is currently generating €637.0 million of profit, and the analyst midpoint points to €916.6 million by around 2029, with earnings per share of €1.49. That is a sizeable move, although the spread is wide, with the most optimistic forecasts at about €1.2b of earnings and the most cautious view at €767.2 million. This leaves plenty of room for your own view on how wage costs, promotions and tax might trend.
The valuation assumptions build on that earnings path. For the present share price to line up with the analyst target, Jerónimo Martins SGPS would need to trade on a P/E of 19.3x those projected 2029 earnings, compared with 18.2x today and a current sector read across of 18.6x. That implies investors paying a slightly richer multiple for what analysts see as higher profits and firmer margins, while share count is expected to remain broadly static over the period.
Consensus modelling uses a discount rate of 7.89% to bring those future cash flows back to today. That rate is an input rather than a fact, and it matters because even small tweaks to the cost of capital can change what looks reasonable on a long dated earnings stream, especially for a retailer with material ongoing capex and exposure to cost inflation across several countries.
Jerónimo Martins SGPS' narrative projects €44.0b revenue and €916.6 million earnings by 2029. This assumes 6.1% yearly revenue growth and implies earnings rising by about €279.6 million from €637.0 million today.
Uncover why Jerónimo Martins SGPS' fair value indicates a 21% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One bullish twist on the Jerónimo Martins SGPS story leans on Ara’s improving profitability as a key earnings swing factor. The most optimistic analysts were pencilling in about €45.8b of revenue and €1.2b of earnings by 2029 before this quarterly miss on EPS. You can treat those pre news projections as one end of a wide opinion range that may shift as you weigh this latest margin squeeze against those earlier assumptions.
Explore 2 other Jerónimo Martins SGPS fair value estimates, including one that suggests as much as 72% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Jerónimo Martins SGPS research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Jerónimo Martins SGPS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jerónimo Martins SGPS' overall financial health at a glance.
Looking for more Jerónimo Martins SGPS sized investment ideas?
If the Jerónimo Martins SGPS story has sharpened your focus on quality, you can use the Simply Wall St Screener to surface other opportunities that better fit your risk tolerance, yield needs, or balance sheet preferences.
- For investors who want financial resilience front and center, filter for companies with robust balance sheets and consistent fundamentals through our curated list of solid balance sheet and fundamentals (197 results).
- If dependable cash payouts matter most to you, narrow your search to stocks with higher yields and more established distributions using the dedicated 221 dividend fortresses.
- When you are hunting for under the radar opportunities with stronger quality markers, scan a focused 603 high quality undiscovered gems that many investors may be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com