


EN
Did Healthcare Device Deal Just Shift AT&T's (T) Investment Narrative?
- AT&T reported that its long running collaboration with Smart Meter has expanded to use AT&T Global SIM Advanced, aiming to keep remote patient monitoring devices connected across more of the United States, including rural and underserved areas.
- The deeper Smart Meter alliance highlights how AT&T is using its core connectivity platform to support healthcare device reliability, remote data transmission and simpler large scale deployments for hospitals and clinics.
- We will now look at how AT&T's investment narrative could be influenced by the expanded Smart Meter remote monitoring collaboration.
Look beyond AT&T and this Smart Meter partnership by comparing it with other hand picked connectivity and infrastructure plays in healthcare and adjacent sectors using our 54 AI infrastructure stocks
AT&T Investment Narrative Recap
To own AT&T, you need to believe the heavy spend on 5G, fiber and convergence will translate into steadier service revenue and better earnings quality, while debt and legacy copper costs get worked down. The Smart Meter expansion fits that story but is small next to the scale of AT&T's network and cost reset goals.
Over the next year, the key swing factor is execution on copper retirement and expense removal, because that drives room for margins to rebuild after recent compression. The biggest near term risk is that high device subsidies and slower cost takeout keep profit growth muted, which would limit flexibility around capital returns.
The clearest reference point for this healthcare connectivity news is AT&T's latest numbers and guidance on October 21, 2026. Management reported Q3 2026 revenue of US$32.3b and net income of US$891m, with nine month revenue at US$95.4b and net income of US$9.3b, and reiterated an outlook for low single digit consolidated service revenue growth in 2026.
Against that backdrop, the Smart Meter deal looks like an incremental proof point that AT&T is leaning on its core wireless network to support connected healthcare use cases, not a needle mover on its own. For you as an investor, the more relevant question is whether similar enterprise wins can layer on top of disciplined capital allocation and cost removal to support the earnings path implied by current expectations.
AT&T's current analyst narrative points to US$137.5b in revenue and US$19.9b in earnings by 2029, built on an assumed 2.2% yearly revenue growth rate, and an earnings increase of about US$6.8b from US$13.1b today.
Uncover why AT&T's fair value indicates a 33% potential upside to its current price that may not last much longer.
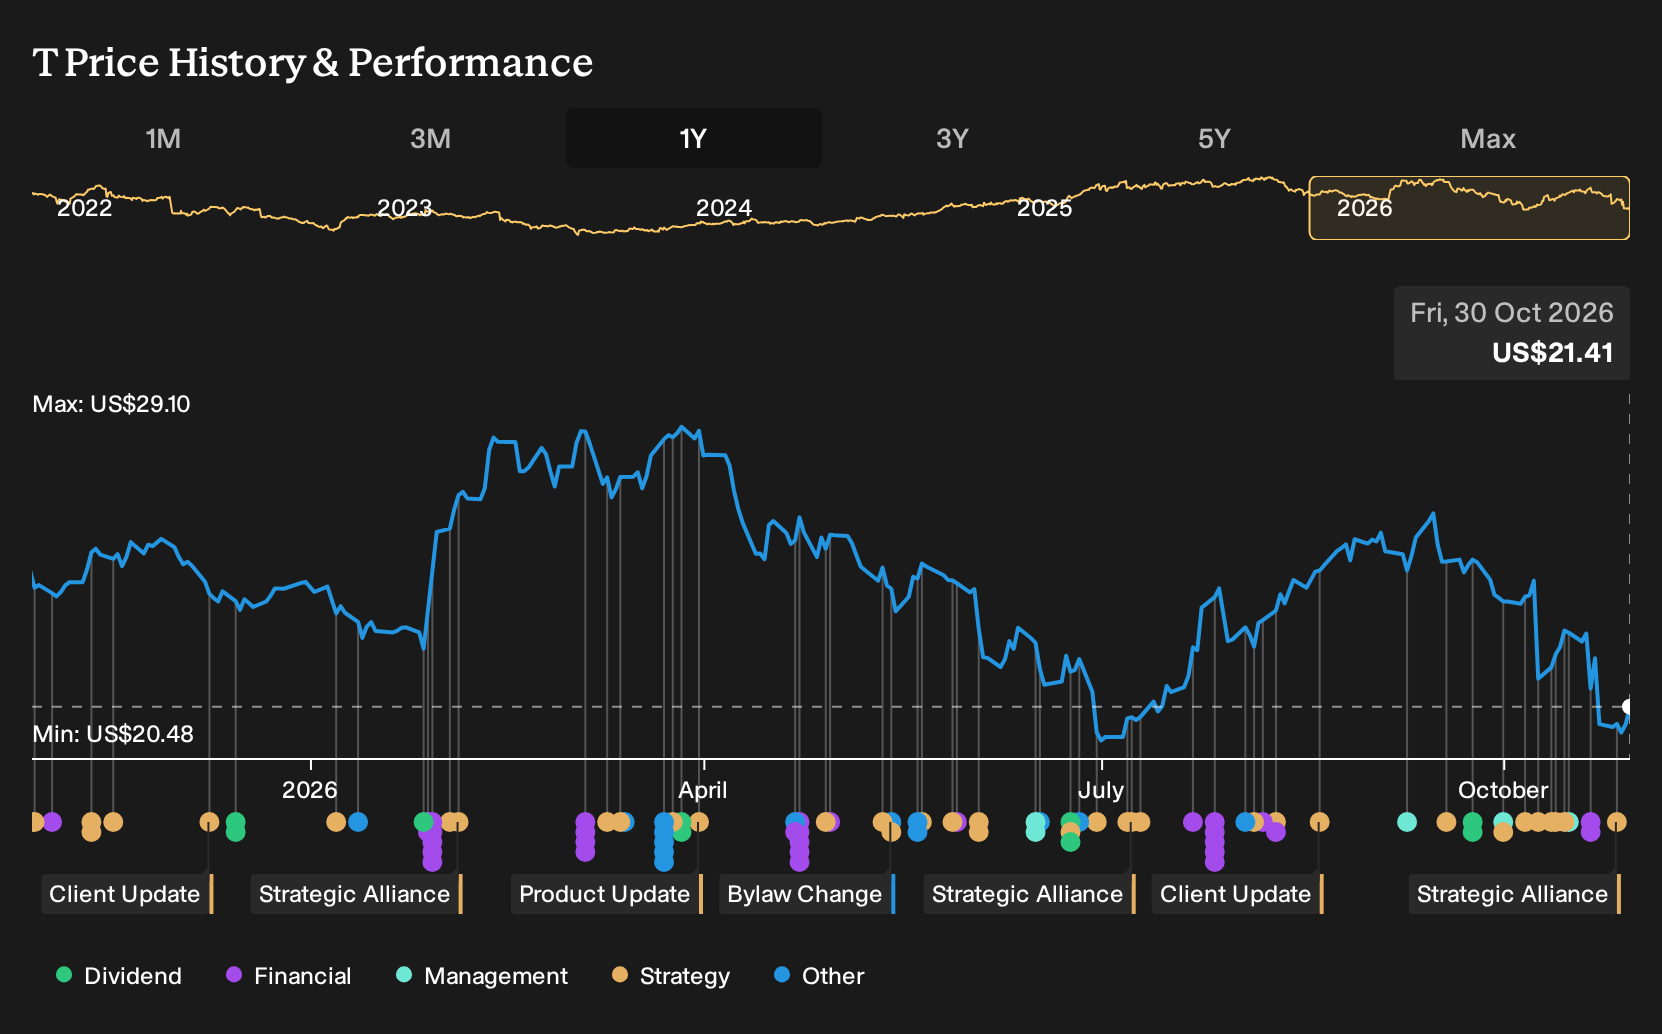
Exploring Other Perspectives
Some of the most optimistic analysts treat AT&T’s Smart Meter style wins as early proof that advanced connectivity can support a richer mix of services. Before this news, they were already penciling in about US$141.8b of revenue and US$21.4b of earnings by 2029. You can compare that upbeat view with more cautious forecasts and decide which storyline you find more convincing.
Explore 6 other AT&T fair value estimates, including one that indicates as much as 59% potential upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AT&T research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for AT&T. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AT&T's overall financial health at a glance.
Looking for more investment ideas beyond AT&T?
Once you have a view on AT&T, it can help to widen the lens and compare it with other opportunities using the Simply Wall St Screener.
- If you want to focus on potential mispricings with quality behind them, scan through 36 high quality undervalued stocks that match strict fundamentals and valuation checks.
- For readers who care most about capital preservation and a smoother ride, filter the market using a 29 resilient stocks with low risk scores that scores well on balance sheet strength and volatility.
- If you are hunting for less crowded opportunities, sort through a 19 high quality undiscovered gems that combine solid business metrics with relatively low investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com