


EN
Learn Why The Bull Case For Zebra Technologies Stock Could Change Following AI Lens Inspection Win
- Zebra Technologies reported that ORAFOL Fresnel Optics has automated inspection of more than 1.5 million complex optical lenses using Zebra’s Aurora Vision Studio with deep learning, replacing manual checks that previously relied on up to 15 operators.
- The switch to Aurora Vision Studio, using standard cameras plus a custom turret, cut inspection times in half and enabled 24/7 workflows with full component traceability. This highlights how Zebra’s software can support labor reallocation and process efficiency in high precision manufacturing.
- We will now look at how Zebra Technologies’ AI powered inspection of 1.5 million lenses could influence the broader investment narrative.
Scan beyond Zebra Technologies and this single factory win by reviewing the hand picked 95 robotics and automation stocks now reshaping how industrial work gets automated from end to end.
Zebra Technologies Investment Narrative Recap
To own Zebra Technologies, you need to believe its mix of automation, data capture and AI software can keep pulling more spend from under automated warehouses, factories and frontline workflows. The ORAFOL win fits that thesis, showing Aurora machine vision doing real work in a complex setting, although one deployment of 1.5 million parts inspected is not a major near term swing factor on its own.
The more immediate swing factor still sits in execution on higher value automation, AI capable devices and software, while keeping a grip on memory costs and tariffs so margins hold near management’s targets. The biggest near term risk remains external cost pressure, from renewed trade friction or memory pricing, which could weigh on gross margin even if demand for Zebra’s automation stack holds up.
The ORAFOL Fresnel Optics deployment lines up tightly with Zebra’s push into machine vision and AI software that feeds data into wider automation systems. It shows Aurora Vision Studio and deep learning running on standard cameras with a custom turret, which points to a flexible, software heavy model. That kind of proof point helps the Asset Visibility and Automation segment story, where modular tools such as RFID, vision and scanners are expected to do more of the heavy lifting.
For catalysts, what matters is whether more customers adopt similar AI based inspection and traceability projects and whether Zebra can price these higher end solutions in a way that offsets cost headwinds such as the projected US$120 million memory expense in 2026. If adoption in use cases like ORAFOL scales across warehouses and manufacturing, it supports the idea that Zebra’s capital light model, ongoing R&D spend just over 9% of sales and acquisitions such as Photoneo can keep earnings growing in line with current forecasts.
Zebra Technologies' narrative projects US$7.2b revenue and US$1.0b earnings by 2029. This assumes 7.0% yearly revenue growth and an earnings increase of about US$461.0m from current earnings of US$539.0m.
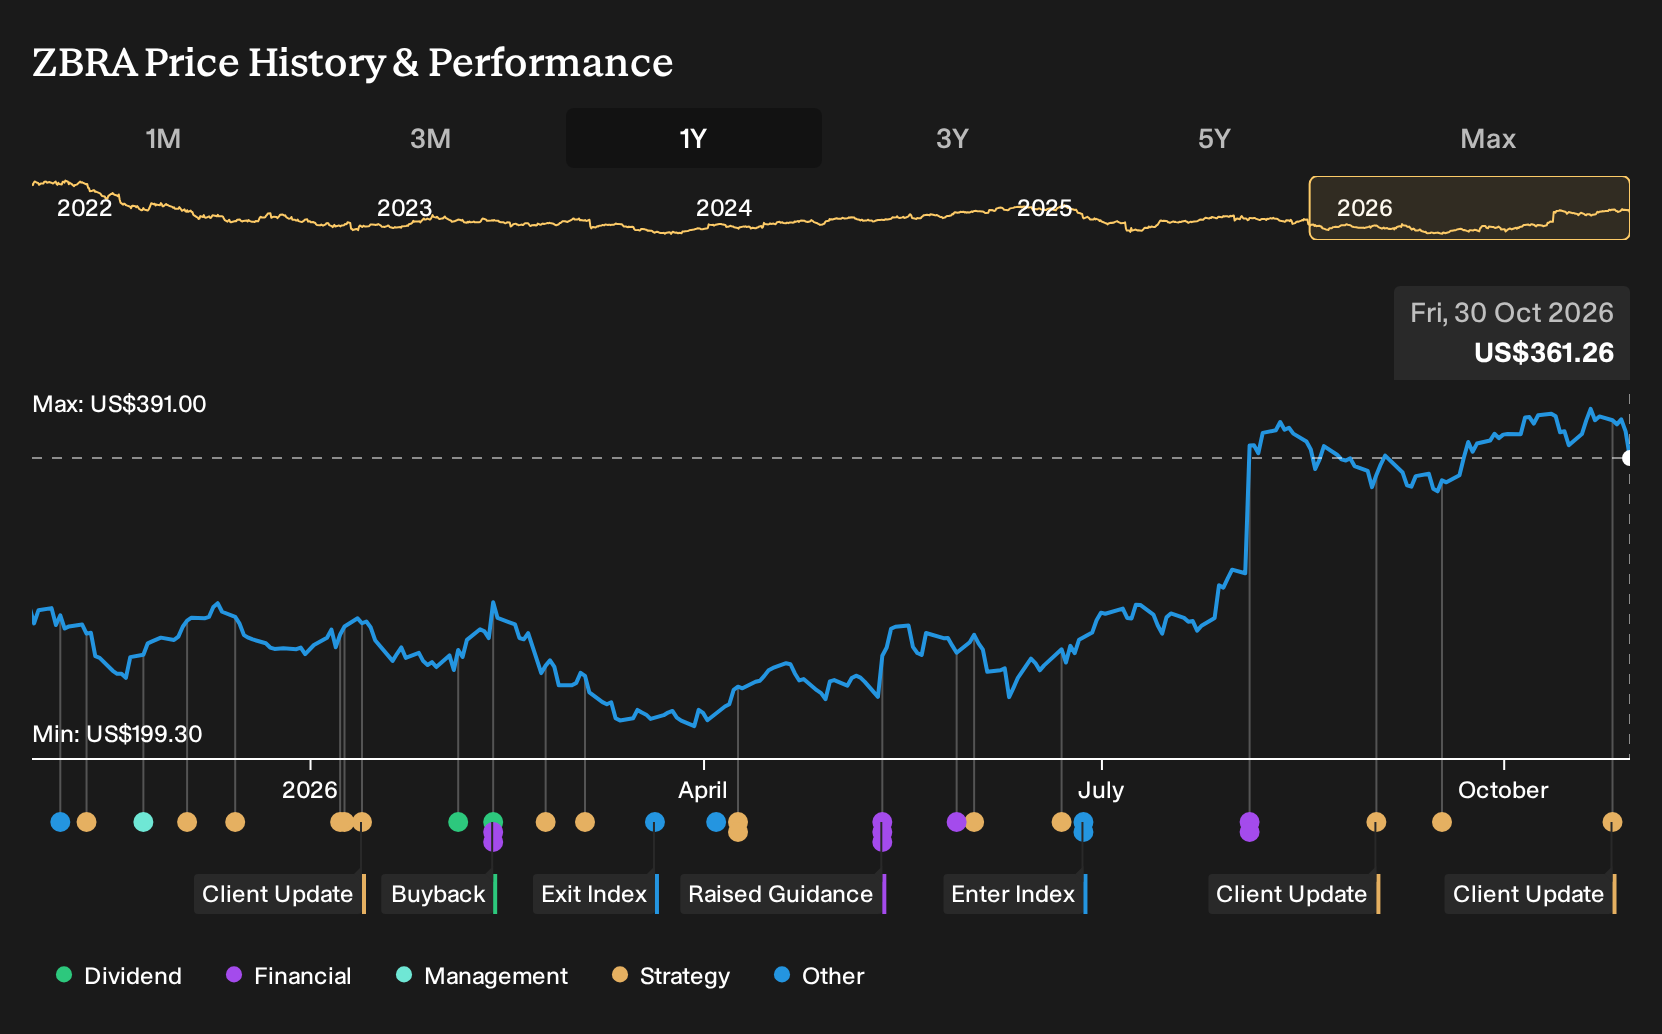
Uncover why Zebra Technologies' fair value indicates a 15% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some bullish analysts treat Zebra Technologies as a much bigger AI and machine vision story than the baseline suggests, assuming revenue could reach about US$7.5b and earnings about US$1.1b by 2029. You can now ask whether this ORAFOL win nudges your view closer to that optimistic scenario or not, and explore both paths.
Explore 4 other Zebra Technologies fair value estimates, including one that suggests as much as 52% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Zebra Technologies research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Zebra Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zebra Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Zebra Technologies?
If the Zebra Technologies story has sharpened your sense of what you want from an automation or AI related stock, the next step is to widen your watchlist with a few targeted stock searches using the Simply Wall St Screener.
- If you want potential mispricing combined with solid fundamentals, start with a curated set of 36 high quality undervalued stocks that might fit a value focused approach.
- Income orientated investors can zero in on reliable cash returns through a group of 5 dividend fortresses that pair higher yields with business resilience.
- For a focus on resilience and capital protection, filter for 29 resilient stocks with low risk scores that score well on financial strength and volatility checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com