


EN
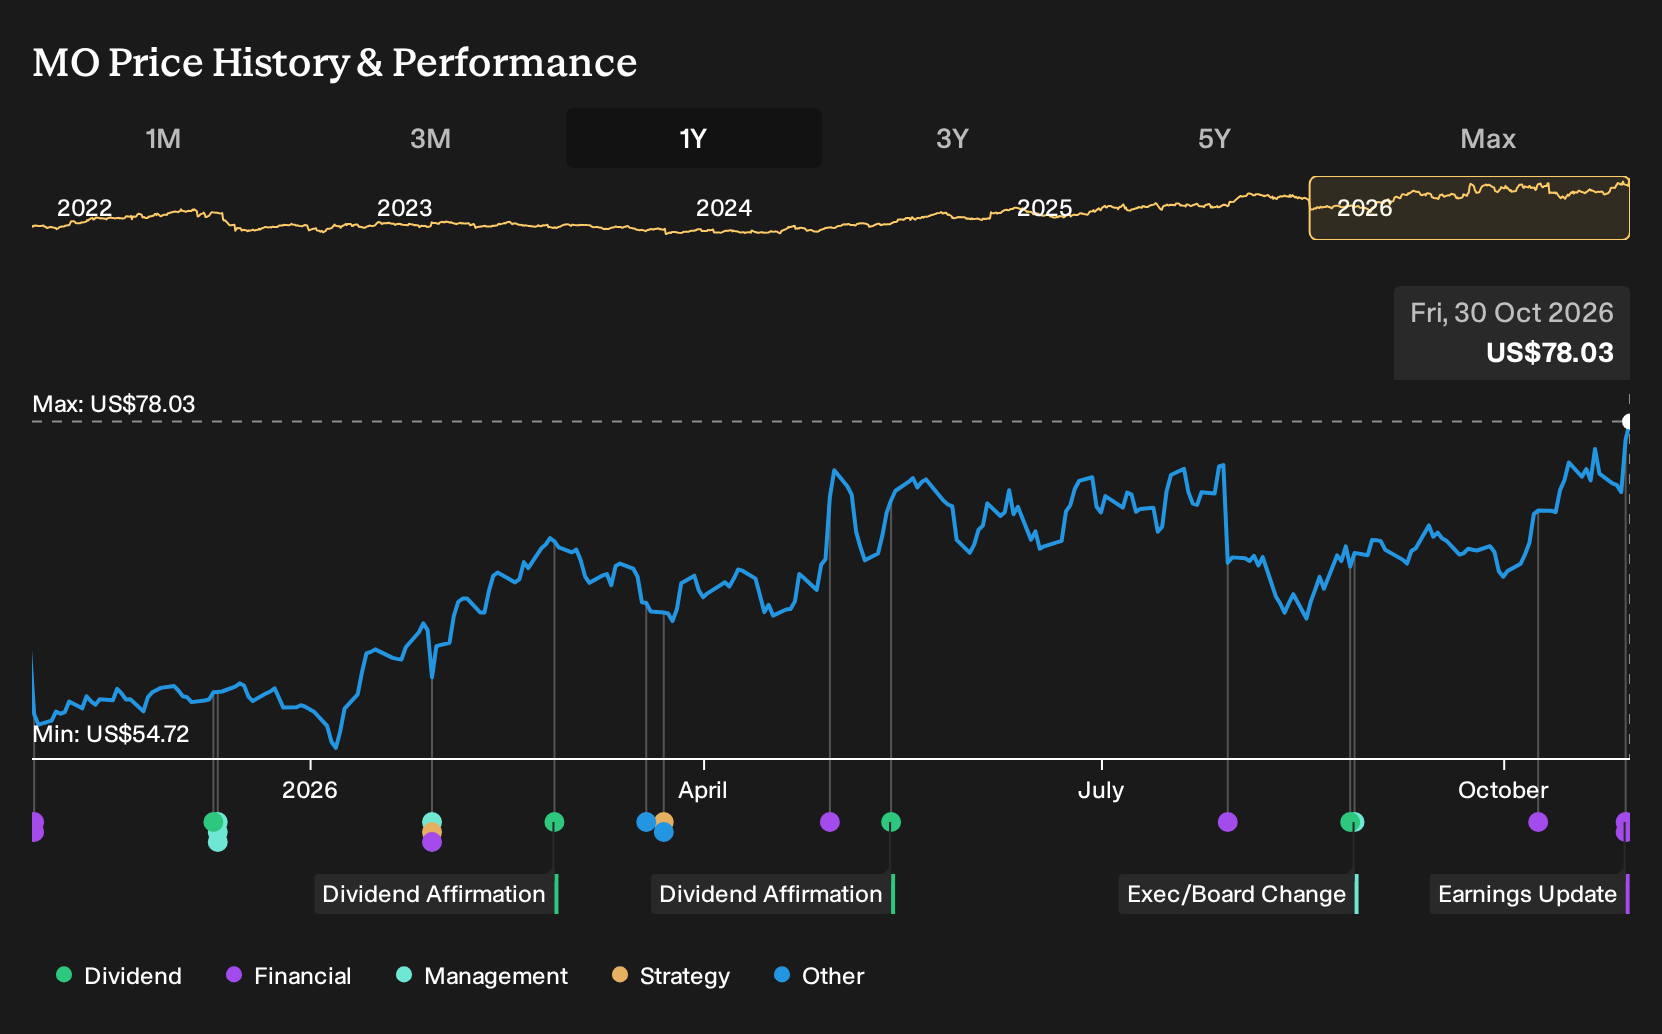
Earnings Beat Could Be A Big Moment For Altria Stock (MO)
- Altria Group reported third quarter 2026 sales of US$5,441 million and net income of US$2,518 million, with basic and diluted EPS from continuing operations of US$1.51, alongside a new shelf registration for potential debt and warrant issuance.
- The combination of higher year to date net income of US$6,999 million and fresh shelf capacity indicates that Altria Group is pairing recent operating performance with added financing flexibility for potential future corporate needs.
- We will now look at how Altria Group's higher earnings per share could influence the investment narrative that analysts built before this update.
Scan how Altria Group's latest earnings and financing moves compare with other income-focused plays by reviewing the 5 dividend fortresses in the market today.
Altria Group Investment Narrative Recap
For an investor to stay with Altria Group, the core belief is that its high margin tobacco portfolio can keep throwing off cash while smoke free products like on! and on! PLUS gradually matter more. The latest quarter shows higher sales and earnings per share versus a year ago, which supports that income story in the near term.
The biggest near term swing factor still looks like execution in smoke free and managing the consumer shift toward discount cigarettes. Trade down pressure, regulatory scrutiny and legal costs remain very real risks. The fresh results help confidence in operations, but they do not remove those pressure points.
The most relevant new piece of information for that thesis is the shelf registration for potential debt securities and warrants. Extra funding capacity gives Altria Group more room to support on! and on! PLUS, the NJOY platform or other portfolio moves if management decides that extra capital is useful.
For you as a shareholder, this tool cuts both ways. Access to funding could support investment in smoke free catalysts and ongoing cash returns, while a higher reliance on borrowing would add to an already meaningful debt load. Execution discipline around when and how that shelf is used now becomes part of the near term watch list.
Altria Group's analyst narrative points to revenues of US$21.3b and earnings of US$10.0b by 2029, based on an assumed yearly revenue decline of 2.2% and an increase in earnings of US$1.9b from the current US$8.1b level.
Uncover why Altria Group's fair value indicates a 7% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate view leans hard into Altria Group’s smoke free momentum as a potential upside surprise. Those analysts were pencilling in about US$21.4b of revenue and US$10.6b of earnings by 2029, compared with the baseline US$21.3b and US$10.0b. The fresh earnings beat and new shelf registration could push that optimistic story in either direction. You can compare both sets of assumptions and decide which feels closer to how you see the business evolving.
Explore 5 other Altria Group fair value estimates, including one that suggests the potential for as much as 82% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Altria Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Altria Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Altria Group's overall financial health at a glance.
Looking for more Altria Group style investment ideas?
Once you have a view on Altria Group, it can help to line it up against a wider watchlist of income, value and quality focused stocks using the Simply Wall St Screener.
- If you want potential income pillars beyond Altria Group, scan for yield focused opportunities by checking out the 5 dividend fortresses.
- For readers who care most about quality at a fair entry point, compare Altria Group with the 36 high quality undervalued stocks that pair strong fundamentals with pricing that may still be reasonable.
- If balance sheet resilience sits at the top of your checklist, broaden your research beyond this stock by reviewing a list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com