


EN
Golar LNG (GLNG) Could Be 30% Undervalued Following 20 Year FLNG Charters
Why 20-year FLNG contracts have put Golar LNG back in focus
Golar LNG (GLNG) has drawn fresh attention after securing 20 year contracts for its floating liquefied natural gas units, locking in long dated EBITDA backlog while geopolitical and marine risks remain a live consideration for investors.
Recent trading reflects that reassessment. Golar LNG’s share price is US$46.24, with a year to date share price return of 21.84%. The 1 year total shareholder return of 14.64% and a very large 5 year total shareholder return of about 3.8x suggest longer term momentum has been strong, even as the 30 day share price return declined 6.04% and the 90 day share price return fell 6.45%. This hints that enthusiasm around those 20 year FLNG contracts is being balanced against ongoing geopolitical and marine risk.
Scan beyond Golar LNG and consider other long-contract, cash flow-focused infrastructure plays using our curated list of solid balance sheet and fundamentals (24 results)
Bulls point to 20 year FLNG cash flows and recent earnings growth, while bears focus on war risk and funding costs. On today’s numbers, which side does Golar LNG’s valuation actually support?
Most Popular Narrative: 30% Undervalued
Golar LNG’s most followed valuation view pegs fair value at about $66.31 per share, well above the recent $46.24 close. This puts those long dated FLNG contracts and funding choices under a brighter spotlight.
The company has secured long term 20 year charters for its existing FLNG units, providing $17b in contracted EBITDA backlog and 20 years of cash flow visibility. This is expected to drive a significant 4x increase in EBITDA and contracted free cash flow by 2028, and the market may still be underestimating how this earnings visibility could support higher revenue and net margins.
See why 26 investors see Golar LNG as 30% undervalued.
Result: Fair Value of $66.31 (UNDERVALUED)
Still, the story around Golar LNG can change quickly if higher cost debt starts to bite into cash flow or if FLNG execution slips on timing and reliability.
Find out about the key risks to this Golar LNG narrative.
Another View: What Golar LNG’s P/E Is Telling You
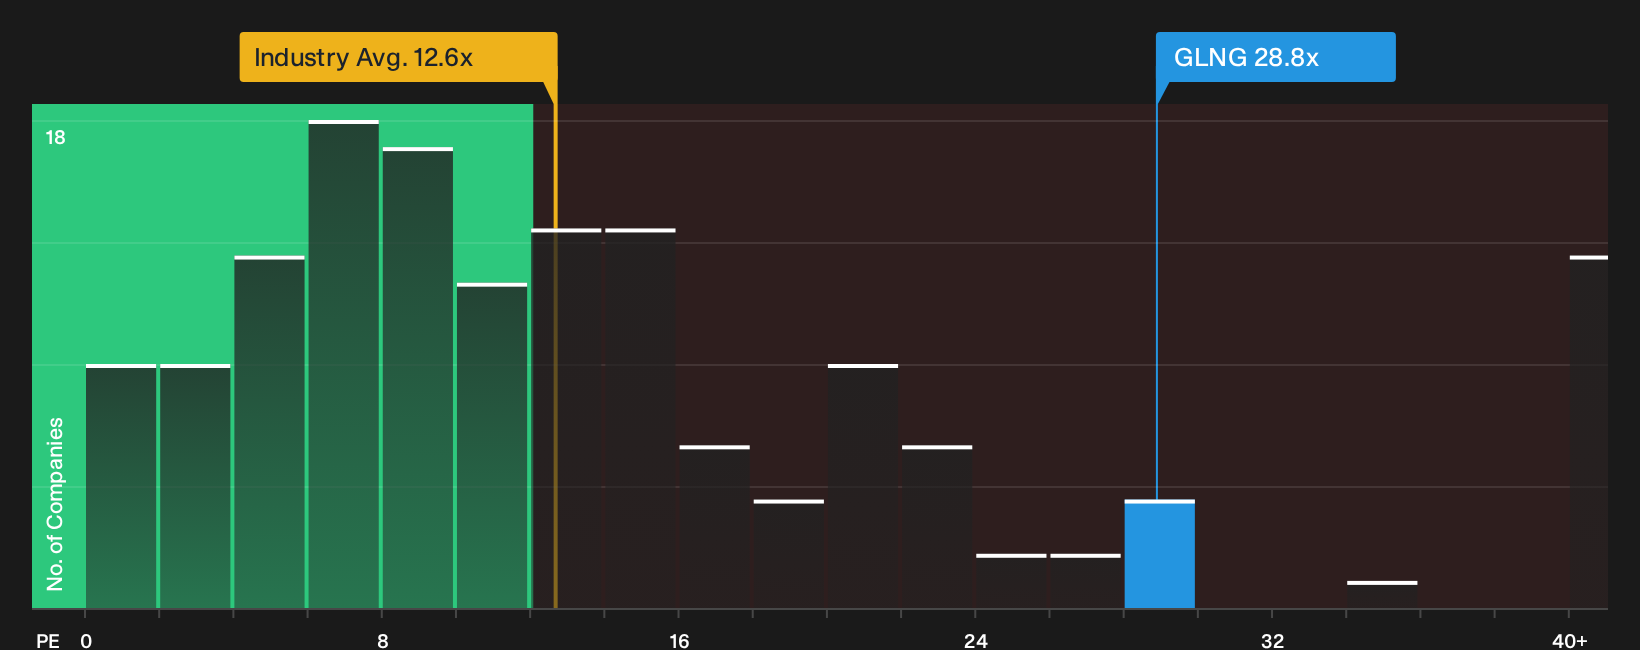
The fair value work around Golar LNG points to upside. The P/E picture is less generous. At 28.8x, the stock trades richer than both its peer group on 16.9x and the US Oil and Gas sector on 12.6x, and even a touch above its 28.2x fair ratio. That gap suggests investors are already paying up for the long term FLNG story. The open question is whether that premium thins out or the earnings catch up first.
For a closer look at how this price stacks up against earnings power, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Golar LNG story can be useful if you use them as a prompt to inspect the numbers yourself and move quickly while sentiment is still split. To see how those concerns and bright spots line up in one place, review the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Golar LNG?
If Golar LNG has sharpened your focus on valuation and risk, use that momentum. Line up a few other candidates now instead of waiting for the next headline.
- Target resilient compounding by reviewing companies with dependable balance sheets and fundamentals through our curated list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced opportunities by scanning a focused 36 high quality undervalued stocks that already combine quality metrics with attractive pricing signals.
- Strengthen your income layer by assessing a hand picked pool of 5 dividend fortresses that already clear a 5% yield hurdle.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com