


EN
Surprised By UTI Asset Management's Slide? What Investors Overlooked
If you backed UTI Asset Management for its 68 new branches, digital tools and global push into New York, the outcome has been harsh. Investors who held UTI Asset Management over the past year are down 31.9%, including dividends. If you were weighing that decision in November 2025, the key issue is clear. Which part of the original case, built on 9.1% revenue growth, a 45.3% margin target and a 19.6x future P/E, failed to account for what actually unfolded?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind UTI Asset Management. Zero in on 200 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Were Balancing On UTI Asset Management
The shares cost ₹1,248 at the start of the period, and UTI Asset Management sat between two very different stories that both sounded reasonable.
On the upbeat side, the bull narrative argued for Fair Value of ₹1,402. It leaned on 9.1% revenue growth and a profit margin rising to 45.3%, helped by 68 new branches plus digital tools like Salesforce and UTI HART.
The bear view pinned Fair Value at ₹965. It focused on rising passive products compressing fee yields and on digital platforms that could leave the physical branch build out as a high fixed cost risk.
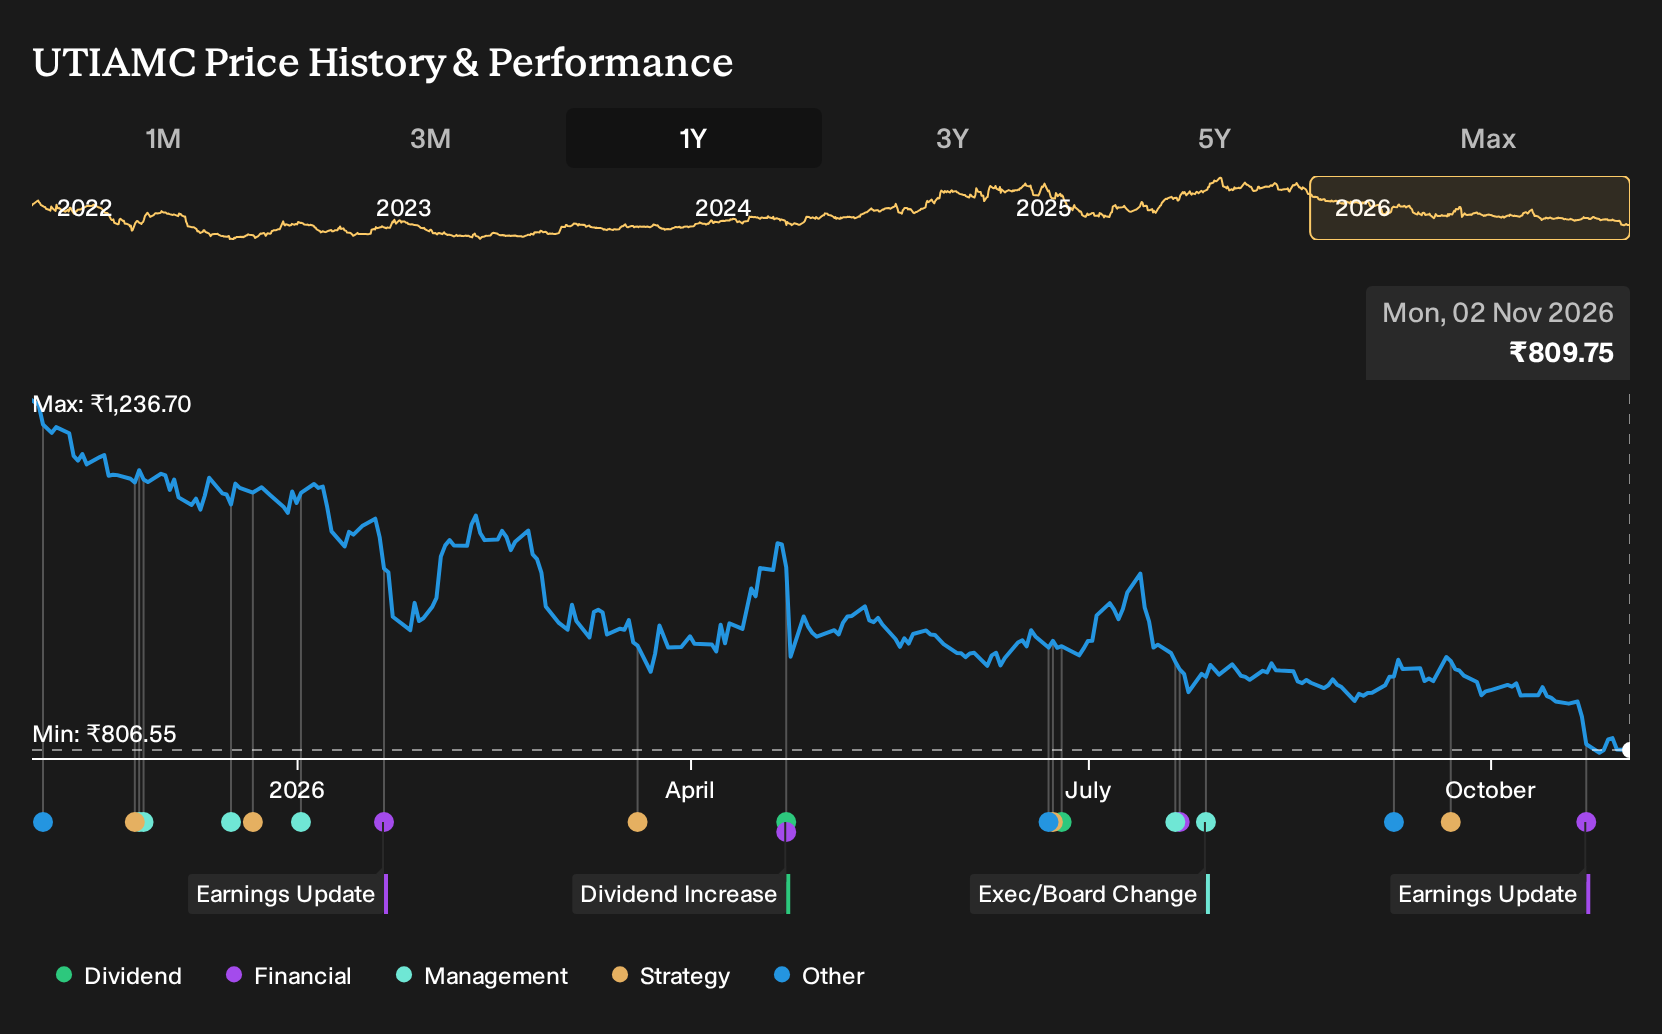
What The Results Changed For UTI Asset Management
The clearest new datapoint for UTI Asset Management was Q2 2027 earnings. Total revenue moved from ₹4,185.5m in Q2 2026 to ₹4,145.9m, while net income rose from ₹1,130.1m to ₹1,323.1m and net margin improved from 27.0% to 31.9%. That mix challenged the high growth bull story and leaned toward the more cautious case.
The key lesson is about which assumption to test. For any fund manager, track whether margin trends in filings match the claimed operating leverage, especially when top line progress is modest.
What You Are Paying For In UTI Asset Management Today
At today’s ₹810 share price, this Narrative’s Fair Value sits above the market and rests on UTI Asset Management turning branch reach plus digital infrastructure into a stronger fee engine.
A buyer today needs to believe UTI Asset Management can translate digital gains, pension AUM and alternatives into meaningfully higher, durable profitability.
"The main thing that has to go right is that UTI Asset Management converts its digital gains, workforce reshaping, and product expansion in pensions, ETFs, and alternatives into stronger and more durable profitability despite higher people and operating costs."
One Narrative disagrees with today's price. → See where this Narrative says UTI Asset Management should trade
How Could You Get There Earlier?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 16% below our estimate - uses a dispersed partner network and proprietary systems to attract senior legal talent.
- Company 2 - 15% below our estimate - expands clinics and wellness sites as health conscious customers adopt preventive ayurvedic services.
- Company 3 - 45% below our estimate - applies data analytics and automation to contain underwriting and claims expenses across offerings.
That is three of the list. See every one of the 198 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com