


EN
How Investors May Respond To AB InBev (ENXTBR:ABI) Earnings Beat
- Anheuser-Busch InBev reported third-quarter 2026 sales of US$16,512 million and net income of US$1,597 million, and the board approved an interim dividend of €0.40 per share, paid on November 23, 2026.
- The combination of higher year-on-year sales and net income for both the quarter and year to date, alongside the interim dividend, highlights how Anheuser-Busch InBev is prioritising cash returns while keeping financial discipline and deleveraging objectives in view.
- This article examines how Anheuser-Busch InBev's investment narrative is influenced by its reported earnings and the new interim dividend.
Compare Anheuser-Busch InBev's earnings strength and fresh dividend with other income opportunities by scanning the 223 dividend fortresses that have been filtered for yield and resilience.
Anheuser-Busch InBev Investment Narrative Recap
To own Anheuser-Busch InBev, you need to be comfortable with a simple idea. The group needs to keep turning its global brand portfolio, premium offerings and digital platforms like BEES and direct to consumer channels into steady revenue and earnings growth. Recent quarterly figures and the interim dividend support that profitability is currently tracking well, although they do not remove execution work in weaker regions.
The key near term swing factor remains how effectively management can improve trends in China while keeping emerging markets momentum intact. The biggest risk is that higher shareholder payouts, together with existing debt, limit flexibility if operating conditions soften. This could constrain investment in marketing, Beyond Beer products and digital capabilities.
The interim dividend of €0.40 per share approved for the 2026 fiscal year is the announcement that really matters here. It reinforces that Anheuser-Busch InBev is now leaning further into cash distributions after several years focused on reducing leverage. The group is still stating that financial discipline and deleveraging remain priorities.
For you as an income focused holder, this payout decision links directly to catalysts and risks. Capital flowing to shareholders can support the investment case as long as earnings, which have been growing, and cash generation stay robust enough to fund marketing, capacity and technology, and still service debt without putting pressure on future optionality.
What The Current Forecasts Assume For Anheuser-Busch InBev
Analysts are effectively anchoring their view of Anheuser-Busch InBev on a steady build in both sales and profitability. The current consensus assumes revenue increases of 4.3% per year over the next few years, and profit margins edging up from 14.9% today to 15.2% in roughly three years. On that basis, earnings are expected to rise from US$9.3b today to US$10.8b by around 2029, with share count gradually shrinking as buybacks offset issuance.
Those same forecasts underpin the headline price targets investors often see quoted. To line up with the consensus target around the stock, you would need to accept a scenario where Anheuser-Busch InBev is generating US$71.1b of revenue and US$10.8b of earnings in 2029 and the shares trade on a P/E of 20.3x, compared with 17.7x today. That valuation multiple also implies a lower P/E than the broader GB beverage peer group at 21.7x based on the figures provided.
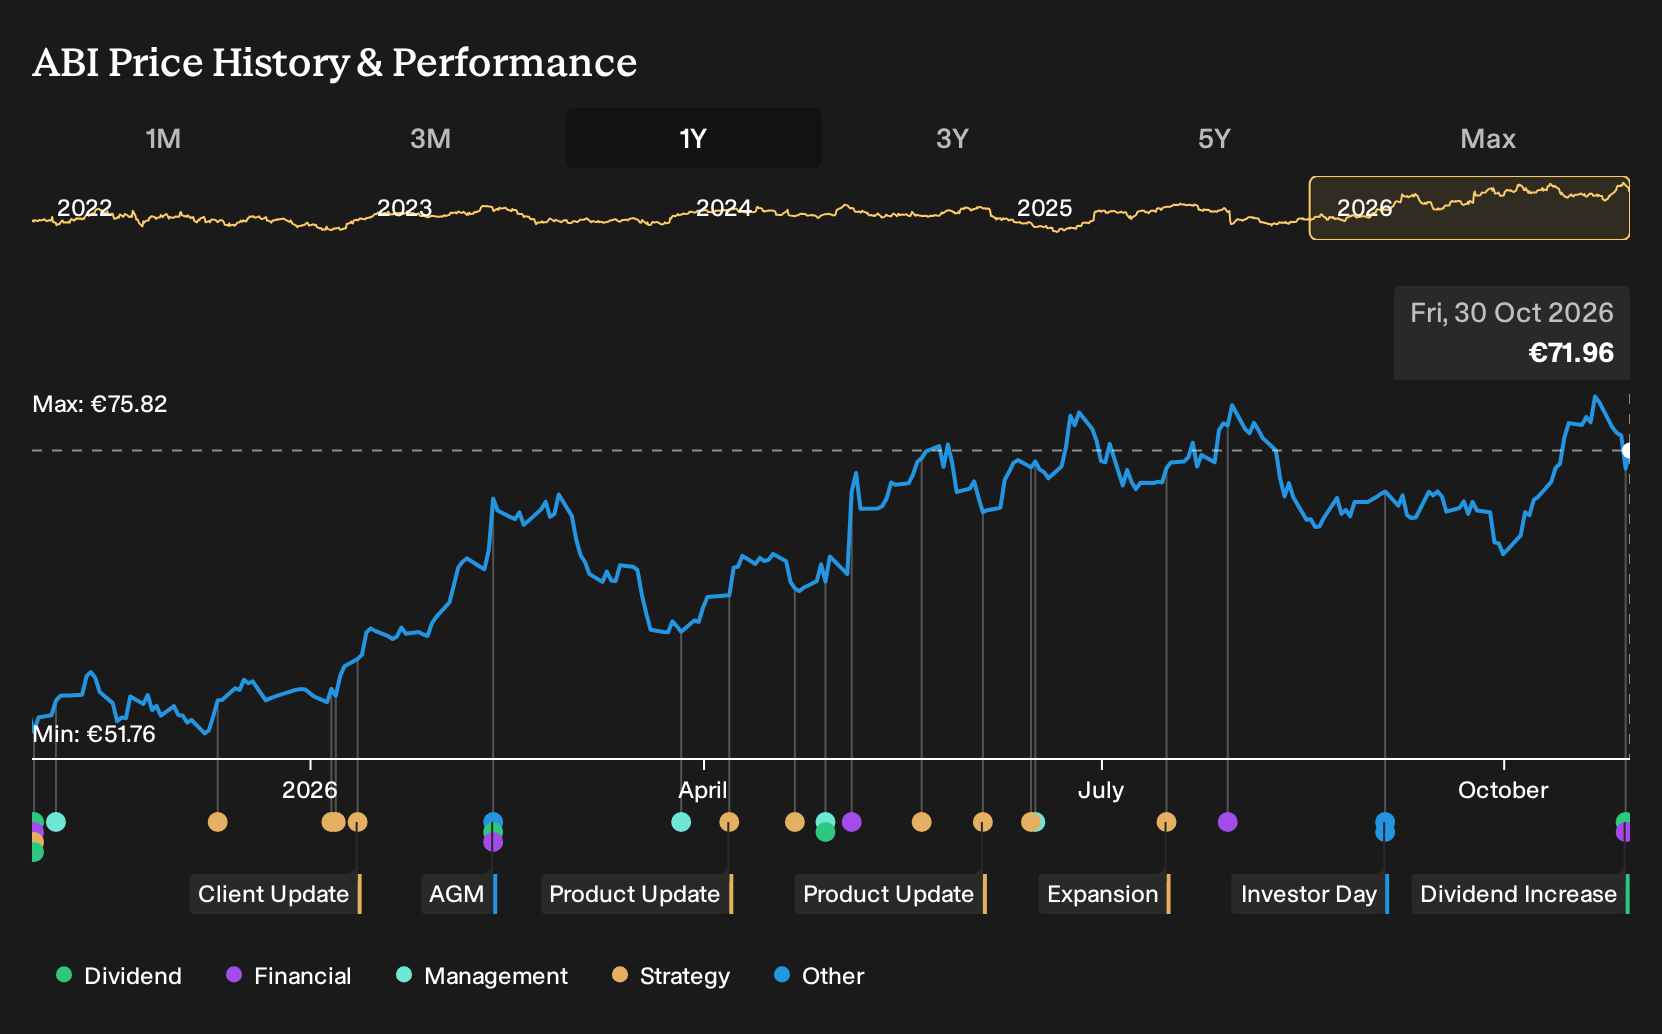
There is still a spread of opinion within those headline numbers, which matters if you are weighing income from the new dividend against the risk in the equity. The most optimistic analysts see scope for a higher outcome, with a price target of €96.34, while the most cautious sit at €68.79, leaving the current consensus at €83.36 versus a share price of €74.36 as of the latest data. That range underlines how different views on execution in China, premium brands and digital platforms can translate into materially different expectations for long run cash flows.
Anheuser-Busch InBev's narrative projects US$71.1b revenue and US$10.8b earnings by 2029. This requires 4.3% yearly revenue growth and roughly US$1.5b earnings increase from US$9.3b today.
Uncover how Anheuser-Busch InBev's fair value indicates a 16% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
The catalyst that bullish analysts focus on is cash generation. Before this dividend and earnings update, the most optimistic group already modelled revenue of about US$74.4b and earnings of US$11.4b by 2029 for Anheuser-Busch InBev. You can read this upbeat narrative as a contrast to more cautious views and consider whether today’s stronger dividend indicates the potential for further upgrades.
Explore 4 other Anheuser-Busch InBev fair value estimates, including one that suggests up to 171% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Anheuser-Busch InBev research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Anheuser-Busch InBev. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Anheuser-Busch InBev's overall financial health at a glance.
Looking For More Investment Ideas Beyond Anheuser-Busch InBev?
If you want to stress test your view on Anheuser-Busch InBev against other opportunities, it helps to scan a wider field of stocks that match the type of income, quality or risk profile you care about most.
- If resilience and balance sheet strength matter to you, start with companies that score well on debt and liquidity by checking the list of solid balance sheet and fundamentals (199 results).
- If you want potential value combined with quality fundamentals, compare Anheuser-Busch InBev with candidates highlighted in the 200 high quality undervalued stocks.
- If income is your priority, broaden your watchlist with the 223 dividend fortresses that meet higher yield thresholds while still screening for stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com