


EN
China Tower And 2 Other Top Undervalued Stocks
Rising interest rates have started to squeeze highly priced AI stories, as funding gets more expensive and lenders turn cautious. That shift puts quieter, cash rich businesses trading below their estimated worth in a more interesting spot for patient investors. This article looks at three companies that our cash flow focused value screen flags as potentially underpriced and explains how their future cash generation could matter for your portfolio.
The three stocks below are only a small sample, and the same cash flow screen currently flags another 459 companies that share similar valuation gaps and cash generation stories outside this article.
If you want to identify and analyze those opportunities for yourself, head straight into the Undervalued Stocks Based On Cash Flows screener
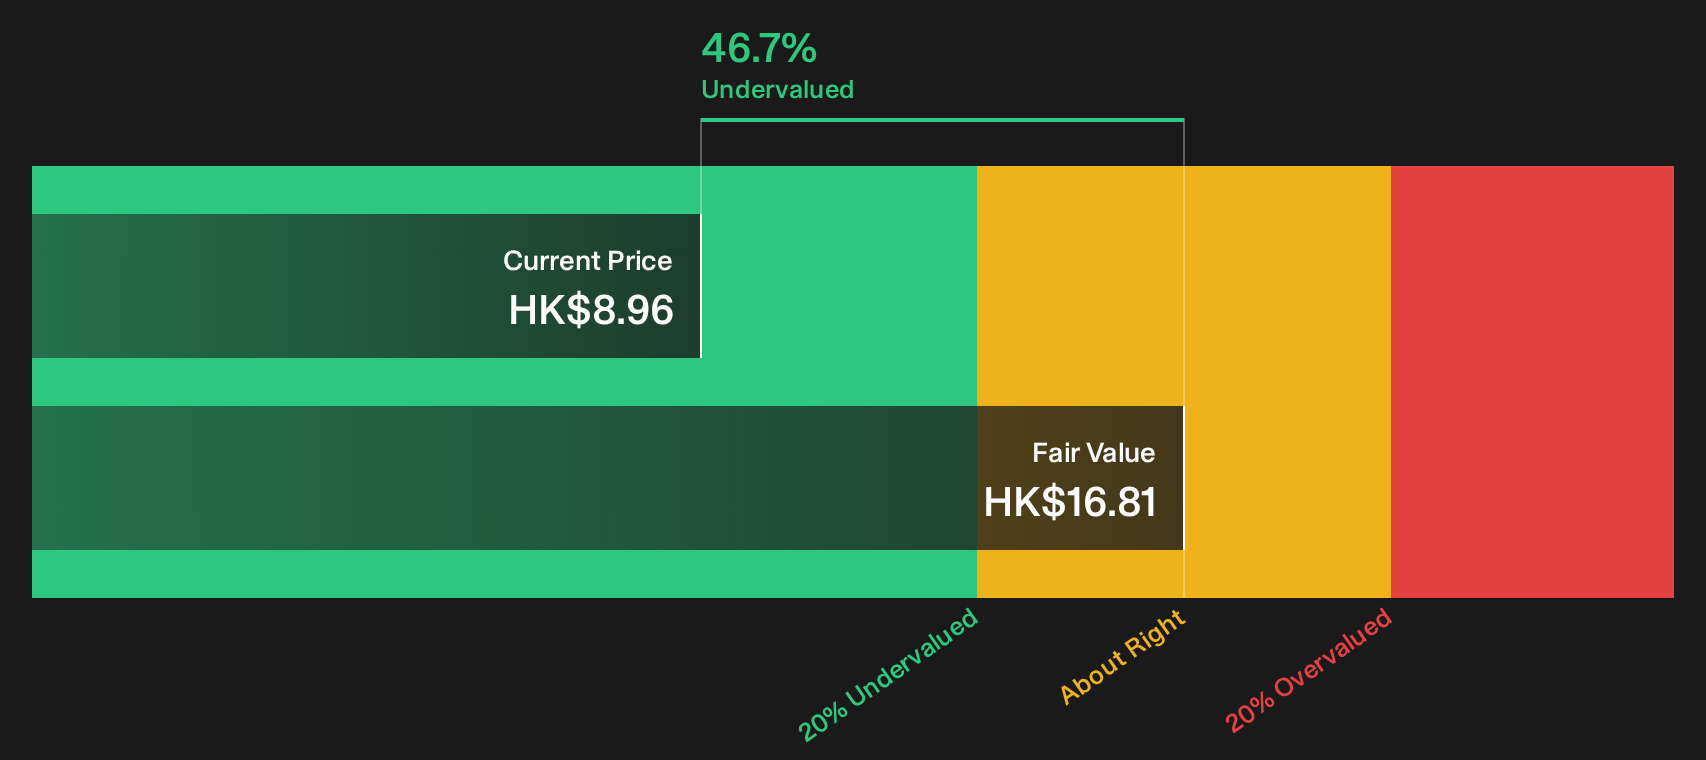
China Tower (SEHK:788)
China Tower plays directly into this screener’s focus on cash flow, since its core business is renting telecom towers and related infrastructure on long contracts. This gives investors a clearer line of sight on future cash generation than many AI heavy stories.
China Tower runs and maintains telecom towers and digital infrastructure across Mainland China, earning all of its CN¥98.1b in 2025 revenue from telecommunications tower infrastructure services and related businesses. The stock carries a market value of about HK$156.5b.
"The ongoing rollout and densification of 5G infrastructure in China, now reflected in China Tower adding 364,000 new 5G base stations in 2025 and 187,000 in the first half of 2026 with over 95% delivered through co-location, continues to support leasing demand that can help sustain tower and DAS revenue and support earnings."
The real swing factor is how one pressure on China Tower’s cash generation plays out against this expanding base of recurring tower income.
That tension is exactly what the full narrative for China Tower unpacks, highlighting where recurring tower cash flows could outweigh that pressure and where the risk could still surprise you.
MINEBEA MITSUMI (TSE:6479)
MINEBEA MITSUMI is a precision parts heavyweight whose bearings and motors fit this cash flow focused screen by producing repeat component sales that are easier to value on discounted cash flow models than one off projects or hype driven themes.
MINEBEA MITSUMI manufactures bearings, motors, electronics, sensors and access hardware. Revenue is spread across Semiconductors & Electronics at ¥613.5b, Motor, Lighting & Sensing at ¥491.2b, Precision Technologies at ¥305.1b and Access Solutions at ¥338.3b, and the company has a market value around ¥1.25t.
That cash flow link is clearest in the high volume bearings and motors that feed into everything from cars to data centers, which is exactly what the screen is trying to capture.
"MinebeaMitsumi is expanding monthly ball bearing capacity from roughly 404 million units to over 460 million by late 2028 to serve AI server and data center demand, which could lift group revenue and support operating margin leverage as higher value bearings scale."
The key question is how a relatively quiet shift in the way those higher value components are used ultimately affects long run profitability.
That profitability question is exactly where the full narrative for MINEBEA MITSUMI connects the capacity build out to cash flow, risk and where MINEBEA MITSUMI’s earnings profile could be quietly accelerating.

IHI (TSE:7013)
IHI is a long established Japanese engineering group. Its gas turbine power generation and cogeneration projects fit this cash flow focused screen, while larger operations in aero engines, defense and social infrastructure shape how those long term contracts feed through to overall earnings power.
IHI Corporation runs a broad mix of energy, infrastructure, industrial machinery and aerospace activities, with aero engine, space and defense bringing in about ¥678.6b, resources, energy and environment ¥394.6b, and industrial systems and general purpose machinery ¥448.2b, against a market value near ¥2.47t.
"Civil aero engines at IHI are in an investment and expansion phase, with management focusing on increasing the number of installed engines and growing higher margin aftermarket services."
What matters for this cash flow story is how one shift in the earnings mix affects the durability of margins over the next few years.
That margin story is only the start, and the full narrative for IHI shows how IHI’s aero engines, energy projects and risks could be quietly reshaping long term earnings power.

Curious About What You Might Be Missing?
Fresh ideas often move first, and some breakouts can gain momentum before most investors even notice. Spot what is still under the radar for now and consider your next steps.
- Look for steady compounders that may be hidden behind volatile headlines by scanning the 218 resilient stocks with low risk scores, which could help you stay invested when sentiment changes and prices move sharply.
- Focus on potential income opportunities while others chase hype by reviewing the 223 dividend fortresses, which aim to keep yields working for you even when share prices are dropping.
- Monitor early movers in industrial transformation by checking the 95 robotics and automation stocks, which may be positioned to benefit as automation trends develop.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com