


EN
What Comes Next For Equinor After A 92% Gain
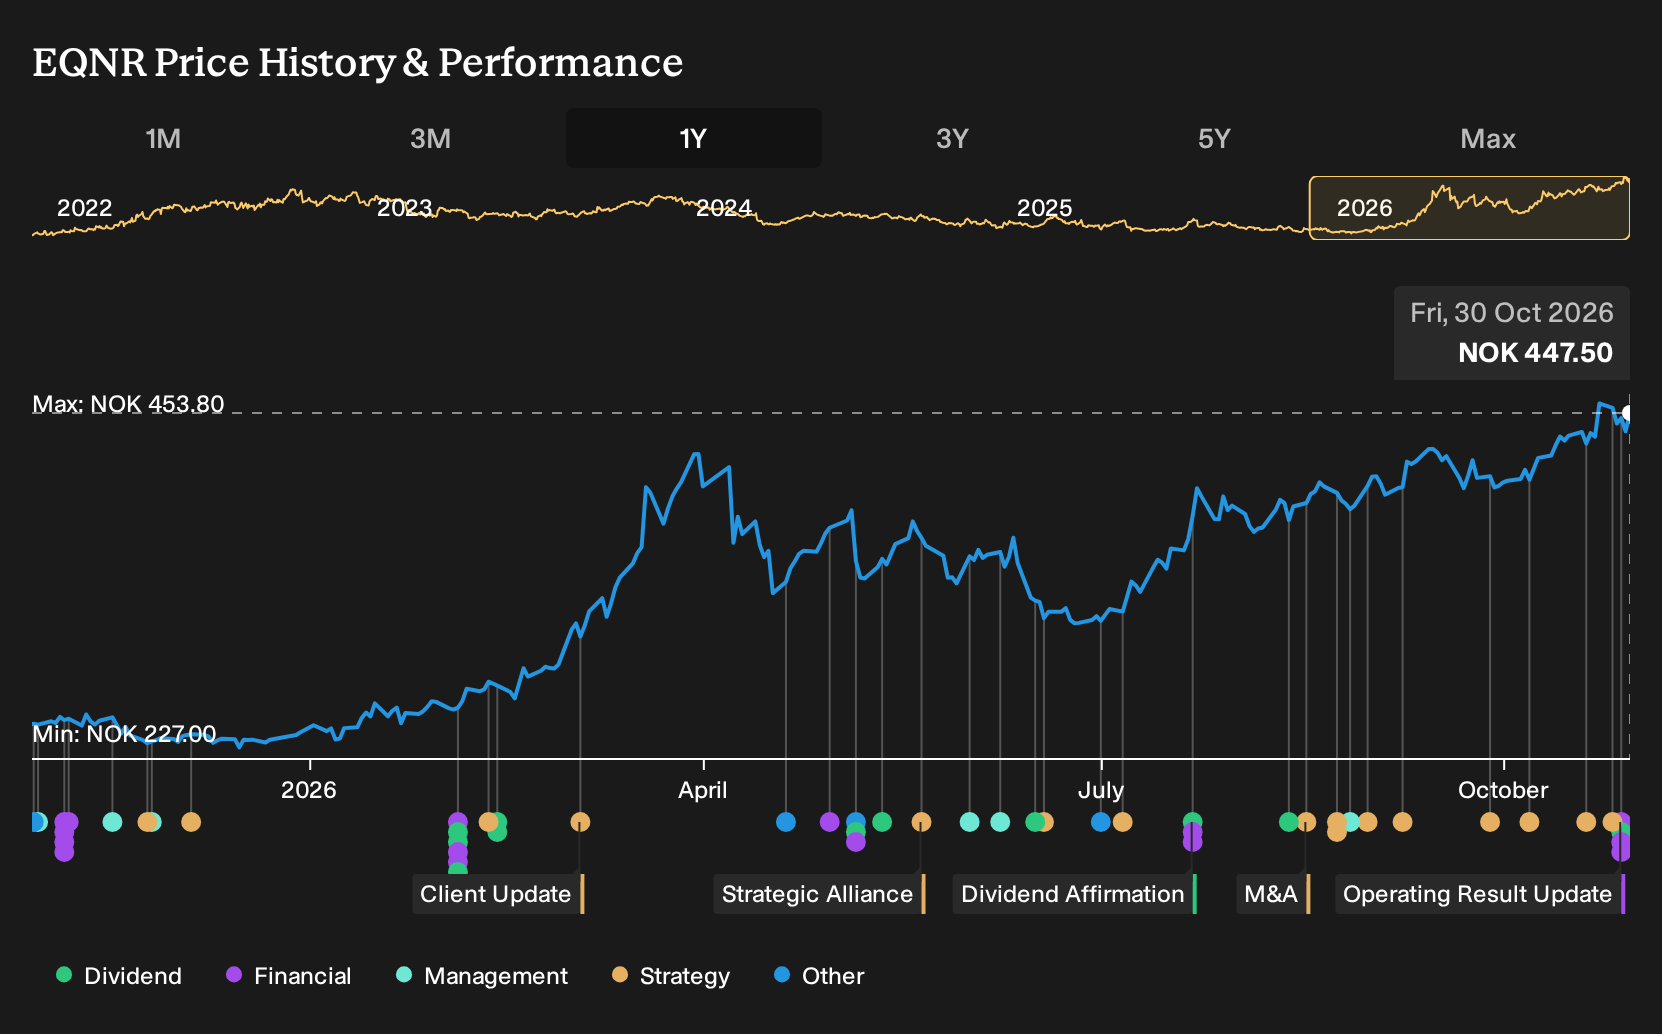
Holding Equinor over the past year would have returned 92.4%, including dividends. If you had been weighing a purchase on 30 October 2025, you were staring at two sharply different stories, from bullish forecasts of sustained cash generation to warnings that climate policy could erode future hydrocarbons demand. With today’s richer buybacks, production ambitions and renewables ambiguities on display, which of those early concerns or hopes would you focus on first now?
The easy part of this move is behind Equinor. Zero in on 203 high quality undervalued stocks for companies trading below our estimates.
Two Equinor Stories Investors Had To Weigh
The shares cost NOK243 at the start of the period, and investors in Equinor had to choose between two very different but plausible storylines.
On the optimistic side, the bullish view put Fair Value at NOK330. That level reflected what that camp saw as justified by assumptions about the future, anchored in expectations that aggressive natural gas expansion and a rapidly growing renewables arm could support resilient cash flow and slightly higher profit margins.
The bearish argument pointed to a Fair Value of NOK184. This view was built on the idea that faster climate policy, rising decommissioning costs in the North Sea, and further impairments in offshore wind could steadily erode future revenue and legacy asset values.
What The Results Changed For The Equinor Debate
Equinor’s Q3 2026 report showed revenue of US$32,936m and net income of US$2,535m, compared with a loss on US$26,017m of sales a year earlier. Net margin moved from a loss of 0.8% to a 7.7% profit. This supported the optimistic case that the business could convert its production plans into healthier profitability, although it did not address longer term climate policy concerns.
The key takeaway is straightforward: when an investment story depends on “resilient cash generation,” it is important to test that claim against net income and margin, not just production headlines or buyback announcements.
What Equinor's Run Up To NOK448 Already Assumes
Equinor shares trade at NOK448 today, after a 92.4% gain over the past year. The selected Narrative’s Fair Value sits below that level, which signals a more cautious stance on what the current quotation already prices in.
The Narrative leans on long term oil, gas and power projects plus new power and minerals ventures. A buyer today effectively banks on Equinor executing its NCS 2035 program and key international projects while keeping cost inflation and project complexity manageable. How does that square with the risk of capex overruns and rising engineering hours described in the source?
"The main thing that has to go right is Equinor successfully executing its NCS 2035 well and tieback program and major international projects while keeping capex overruns, operating cost inflation and rising engineering hours under control. The current valuation implies the market is placing a high value on Equinor’s ability to sustain strong cash flow, maintain increased buybacks and deliver on long term growth ambitions without material erosion of returns."
The price and this Narrative do not agree. → Uncover what this Narrative says Equinor is actually worth
How Could You Get There Earlier?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 36% below our estimate - supplies specialized GPU infrastructure when AI workloads exceed generic compute capabilities.
- Company 2 - 18% below our estimate - expands manufacturing capacity so new wellness lines reach more retail and online channels.
- Company 3 - 43% below our estimate - converts existing forensic software clients to premium subscriptions with additional AI-enhanced tools.
Three companies from the same screener. Open all 200 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com