


EN
What PARK24 (TSE:4666)'s Profit Cut Means For Shareholders
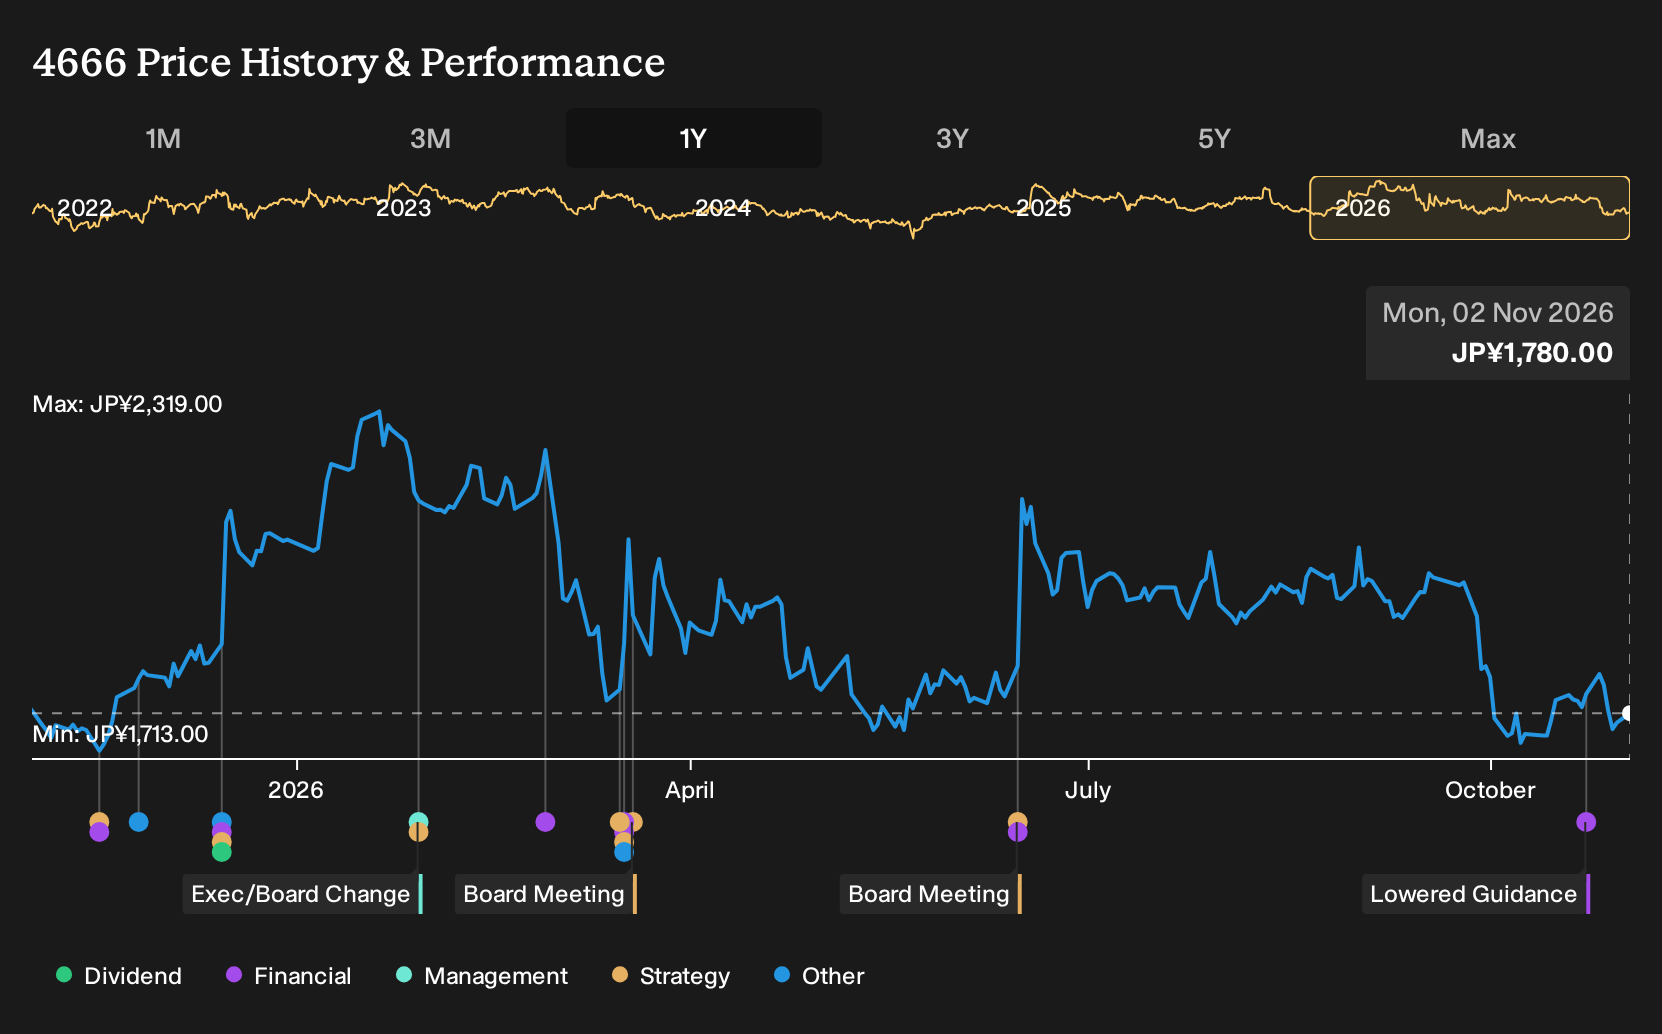
- PARK24 revised its full year 2026 guidance in October 2026, keeping net sales at ¥411,000 million and operating profit at ¥42,500 million, while cutting profit attributable to owners of parent to ¥38,500 million and profit per share guidance to ¥225.54 due to an expected extraordinary loss of ¥5,500 million.
- The unchanged sales and operating profit forecasts suggest the core parking and mobility operations are tracking prior expectations. The earnings downgrade is instead tied to a one off extraordinary loss that flows directly through to profit attributable to owners of parent.
- The investment narrative for PARK24 will next be tested against this one off ¥5,500 million extraordinary loss hitting full year profit guidance.
Scan how PARK24's revised profit outlook compares with peers facing one off hits by checking our hand picked list of 22 resilient stocks with low risk scores.
PARK24 Investment Narrative Recap
To own PARK24, you need to be comfortable with a parking and mobility business that is still leaning on restructuring overseas while using technology to squeeze more productivity from its network. The unchanged net sales and operating profit guidance point to a core operation that is broadly on track in the near term.
The extraordinary loss that triggered the cut to profit attributable to owners of parent looks material for this fiscal year’s bottom line but not for day to day trading or car sharing activity. The more immediate risk remains execution in the U.K. and Australia, where prior impairments and tax costs have already pressured profitability.
The most relevant update is the October 2026 guidance revision itself, since it clarifies where pressure is landing. Net sales of ¥411,000 million and operating profit of ¥42,500 million are unchanged. Profit attributable to owners of parent has been reduced to ¥38,500 million due to the planned ¥5,500 million extraordinary loss.
For you as a shareholder, that means the short term swing factor is the timing and scale of one off items rather than a visible shift in PARK24’s parking or Mobility Business trajectory. The key catalyst still sits in how efficiently unprofitable overseas sites are pruned and how reliably domestic usage fees and occupancy hold up against these ongoing restructuring efforts.
PARK24's current analyst story points to forecast revenue of ¥475.9b and earnings of ¥29.1b by 2028, based on an assumed 7.0% yearly revenue growth rate and an earnings increase of ¥14.5b from ¥14.6b today.
Uncover why PARK24's fair value indicates a 55% potential upside to its current price, a gap that could narrow quickly.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your PARK24 research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for PARK24. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PARK24's overall financial health at a glance.
Looking for more investment ideas beyond PARK24?
PARK24 might already be on your radar, but building a resilient portfolio usually means lining up a few different angles. The Simply Wall St Screener can help you quickly filter for companies that match the kind of risk, quality, or income profile you want to pair with this stock.
- For potential mispriced opportunities with strong quality markers, scan our hand picked 15 high quality undervalued stocks that may warrant a closer look.
- If capital preservation sits high on your list, narrow your search to companies on the 22 resilient stocks with low risk scores that combine lower risk scores with more resilient profiles.
- Income focused investors can put cash flows to work by reviewing the 30 dividend fortresses that match a preference for higher yields backed by fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com