


EN
Is Walmart (WMT) Cheap As Membership And Automation Spending Ramp Up?
Walmart (WMT) has put subscriptions and logistics in the spotlight after launching a combined Walmart+ and Sam's Club Plus membership for $120 a year and committing billions to new automation and robotics projects.
The recent membership bundle lands on top of a strong run for Walmart, with a 30 day share price return of 18.46% and a 1 year total shareholder return of 22.60%, while the 3 year total shareholder return of 131.91% points to momentum that has built over a longer stretch. Recent headlines around expanded automation with Symbotic, a planned US$400m robotics enabled distribution center in Texas, new healthcare marketplace services and the Base Power energy offering all contribute to a narrative in which investors appear to be reacting to execution on logistics, services and membership rather than to a single catalyst.
Scan other retailers that combine membership economics with logistics improvements by reviewing our hand picked 36 high quality undervalued stocks.
Walmart now looks like a stronger, more rounded business after its recent membership and automation push. The open question is whether that strength is already fully embedded in today’s near US$980b valuation.
Most Popular Narrative: 20.1% Undervalued
Walmart closed at $123.51 while the most followed valuation story on Simply Wall St pegs fair value at $154.58, which implies a sizeable gap that narrative driven investors are watching closely.
Walmart’s “Other” SBU is positioned to leverage innovation and agility to capture new market share. While risks exist, the segment’s current performance and strategic initiatives are key areas of focus. Investors and stakeholders may wish to monitor developments in digital integration and specialty category expansion as potential drivers of future growth.
See why 66 investors see Walmart as 20% undervalued.
Result: Fair Value of $154.58 (UNDERVALUED)
Still, if Walmart’s automation projects hit delays or its “Other” segment underdelivers on profit, that 20.1% undervalued narrative could unwind quickly.
Find out about the key risks to this Walmart narrative.
Another View On Walmart’s Valuation
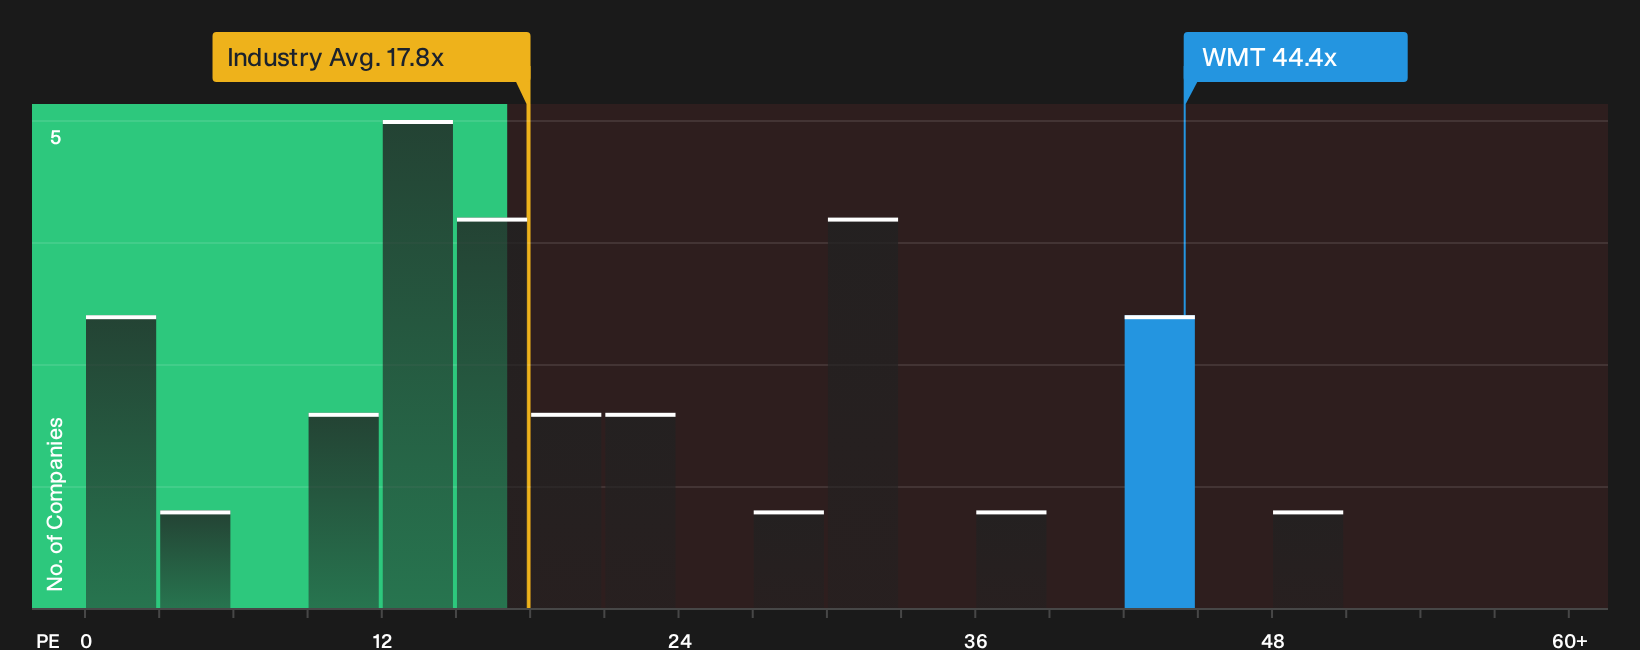
The story that Walmart is 20.1% undervalued looks very different once the earnings multiple is brought into focus. The stock trades on a P/E of 44.4x, compared with 17.8x for the US Consumer Retailing industry and 24.3x for direct peers, while the fair ratio sits at 42.7x.
This kind of premium raises the bar for future execution and leaves less room for mistakes before sentiment adjusts. The question for you is straightforward: Is Walmart priced for slightly better outcomes, or for perfection?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Walmart is strong and the numbers have given both bulls and skeptics plenty to chew on. If you want to move quickly from reading to deciding, spend a few minutes with the key positives that investors are focused on through 2 key rewards
Looking for more investment ideas beyond Walmart?
If you stop with Walmart, you miss the wider opportunity set. Put these screeners to work and pressure test whether your next move really earns a place in your portfolio.
- Target income first by scanning for companies that match your yield and stability preferences through 5 dividend fortresses.
- Hunt for mispriced quality by filtering for strong fundamentals and attractive entry points with the 36 high quality undervalued stocks.
- Prioritise resilience by zeroing in on businesses with robust finances using the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com