


EN
Raised Revenue Outlook Might Change The Case For Investing In IDEXX Stock (IDXX)
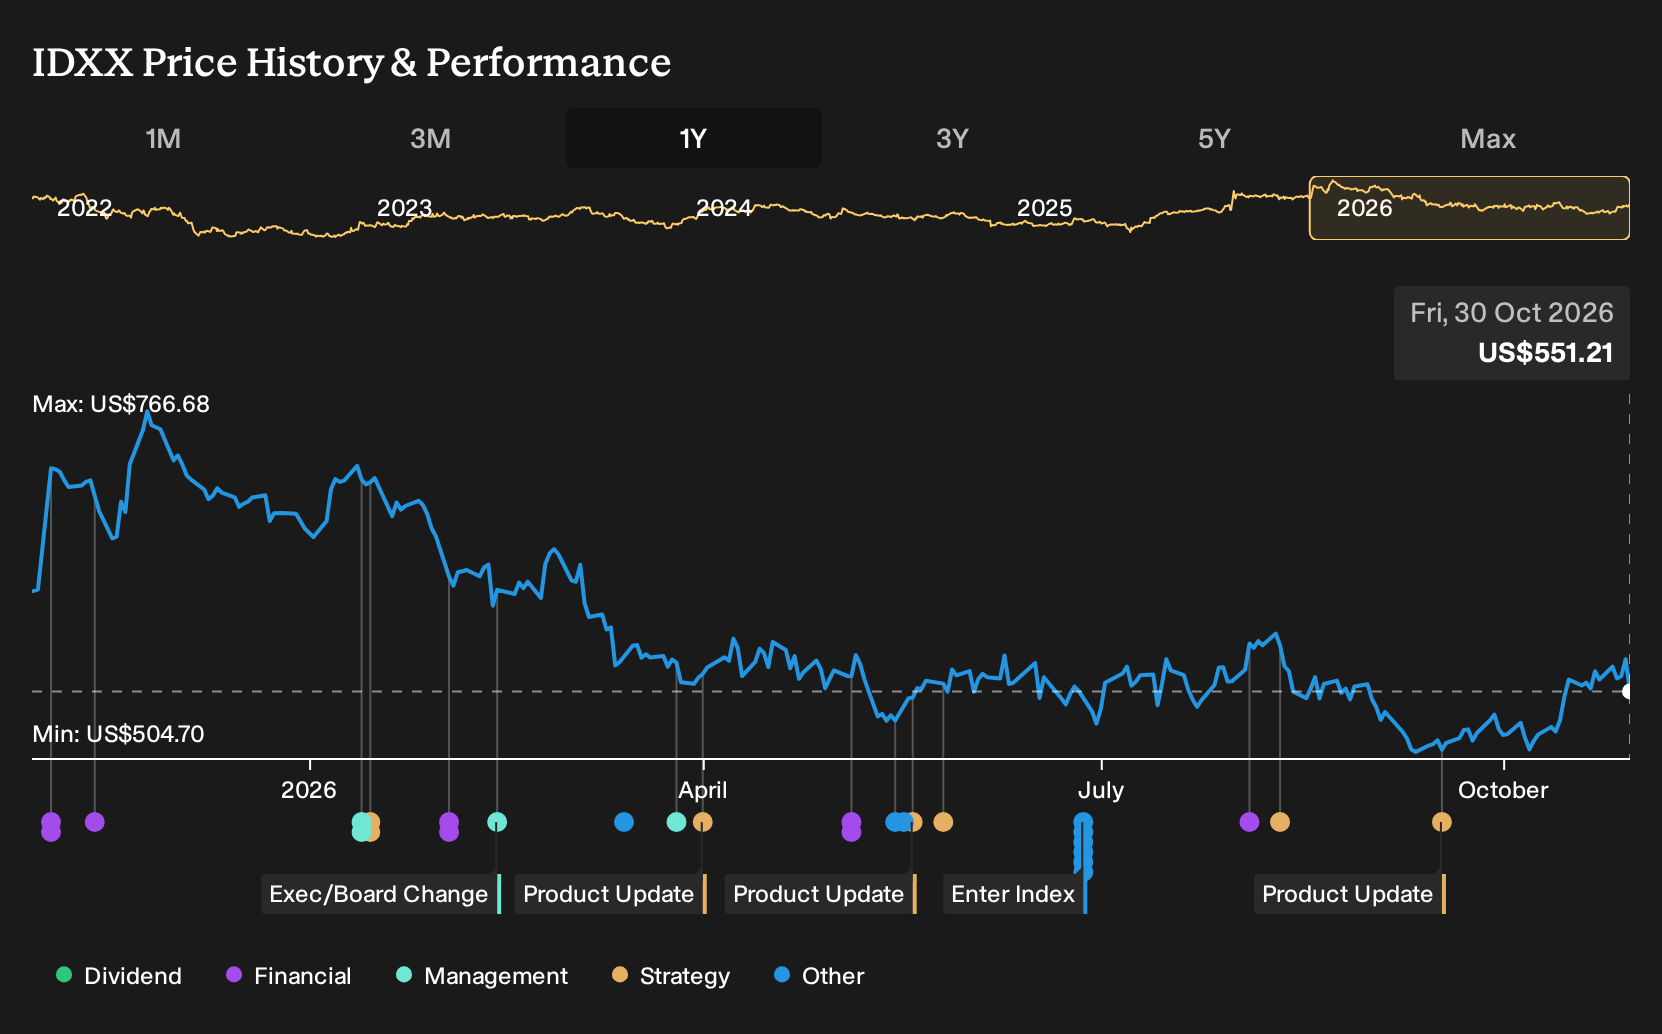
- IDEXX Laboratories recently raised its longer term revenue expectations and broadened its product suite with new diagnostic markers and digital imaging systems, aiming to deepen recurring diagnostics usage across its installed base.
- The richer menu of diagnostics and imaging tools creates more reasons for clinics to run tests through IDEXX Laboratories equipment, which can concentrate more of each practice’s ongoing spend inside the ecosystem.
- We will now look at how IDEXX Laboratories' higher long term revenue ambitions may reshape the existing investment narrative around diagnostics.
Scan beyond IDEXX Laboratories to compare its diagnostics-led model with other handpicked healthcare and AI players using the 34 healthcare AI stocks that fit a similar recurring revenue story.
IDEXX Laboratories Investment Narrative Recap
To own IDEXX Laboratories, you generally need to believe that underused diagnostics in companion animals, plus a larger installed base, can keep supporting recurring testing and software usage even while U.S. vet visits are a bit soft. The raised long term revenue ambition leans into that idea but does not suddenly remove the execution work required inside clinics.
In the near term, the key swing factor still sits in diagnostic volumes per practice and how quickly newer platforms like inVue Dx and Cancer Dx become everyday tools rather than occasional add ons. The biggest risk remains higher operating spend for international build out and R&D not being matched by a richer recurring diagnostics mix, which could pressure the margin trajectory.
The most relevant piece of recent news is IDEXX Laboratories lifting its longer term revenue expectations while adding fresh diagnostic markers and digital imaging systems. That move lines up directly with the existing catalyst that depends on deeper utilization of instruments like Catalyst, inVue Dx and Cancer Dx across a growing VetLab footprint and international footprint.
If clinics embrace the broader testing menu and integrated imaging, the same installed base can support more consumables and software usage per site, echoing the recurring revenue thesis already outlined. If adoption is slower or customers trade down to cheaper competitor options in response to inflation, the higher revenue bar could amplify sensitivities around pricing, mix and operating margin execution.
IDEXX Laboratories' current analyst narrative points to revenue of US$5.9b and earnings of US$1.6b by 2029, based on forecast top line growth of 8.8% a year and an earnings increase of about US$500m from the current US$1.1b level.
Uncover why IDEXX Laboratories' fair value indicates a 27% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on pricing risk. You might worry that IDEXX Laboratories leans too hard on bundled cancer and cytology tests that keep prices near US$15 per panel and reference a 33.4x P/E in the bearish case. Those analysts were pencilling in about US$5.8b of 2029 revenue and US$1.5b of earnings before this latest guidance shift, so the new revenue ambition could push those expectations higher or widen the debate.
Explore 6 other IDEXX Laboratories fair value estimates, including one that suggests as much as 39% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your IDEXX Laboratories research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for IDEXX Laboratories. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IDEXX Laboratories' overall financial health at a glance.
Looking For More Investment Ideas Beyond IDEXX Laboratories?
If this IDEXX Laboratories story has you thinking about portfolio gaps, it can help to line it up against other stocks with different strengths and risk profiles using the Simply Wall St Screener.
- For investors who want income that can potentially keep pace with inflation, start by reviewing 5 dividend fortresses offering substantial yields and robust payout histories.
- If capital preservation and steadier balance sheets matter most to you, filter for 29 resilient stocks with low risk scores that score well on financial resilience.
- When you are hunting for quality businesses that are not yet widely followed, sort through 19 high quality undiscovered gems that combine solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com